

By Sudeshna Ghoshal and Ragini Mathur
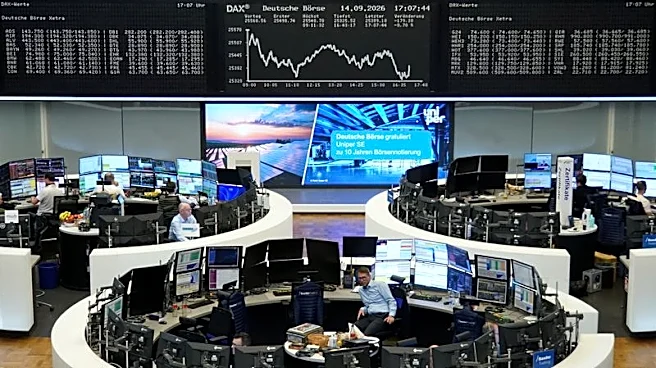
Sept 18 (Reuters) - Europe's STOXX 600 tumbled on Friday in broad-based losses led by automobile and telecom shares, while also logging a weekly decline in a week marked by retreating oil prices and interest-rate decisions by major central banks.
The pan-European index fell 1.1% to 635.45 points, giving up almost all the gains made in the last two sessions. It was down 0.6% for the week.
Regional bourses also ended the session in the red, with London's FTSE 100
and Germany's DAX down 1.5% and 1.6%, respectively.
The automobile and parts sector fell 3.4%, with Volkswagen leading the losses in its biggest one-day drop since September 2025, down 5.6%.
The company slashed its outlook, flagging €10 billion ($11.5 billion) in one-off items related to its stake in luxury sports car maker Porsche, provisions for job cuts and a weak Chinese market.
Porsche shares fell 4.9%.
Telecommunication stocks were down 3.3%, posting their biggest single-day fall since April 2025, with Airtel Africa dropping 11.3% to become the STOXX's top decliner after Bloomberg News reported that its unit Airtel Money is considering downsizing its London IPO.
Food and beverages lost 1.9%, with Nestle down 2.6% after Russia seized control of the Swiss food giant's local assets.
Oil prices pared earlier losses on Friday as markets assessed Saudi supply alongside concerns about a widening Middle East conflict. Still, energy shares shed 0.7% and fell 0.5% for the week. [O/R]
A respite in the selloff in the bond market, along with receding crude prices, helped risk sentiment this week. The moves came even as the US Federal Reserve increased rates, while the Bank of England left rates unchanged but warned that further tightening may be needed if the war in Iran drags on.
The central banks' headlines added to the sense that the policymakers were now getting the jump on inflation.
"The focus for next week will be whether this month's rate hikes represent insurance against an energy-driven inflation shock or the beginning of a lengthy global tightening cycle," said Daniela Hathorn, a senior market analyst at Capital.com.
"If yields stabilise and oil continues lower, equities could find some breathing room."
Meanwhile, the European healthcare sector was the best performer this week, followed by insurance, while banks and automobiles were the worst hit.
Also on the radar are developments ahead of next week's meeting between US President Donald Trump and his Chinese counterpart Xi Jinping.
Among other stocks, Orange dipped 5.8% after Morgan Stanley downgraded the French telecoms company to "underweight."
LPP climbed 8% after Poland's largest fashion retailer reported a 64% rise in second-quarter net profit.
(Reporting by Sudeshna Ghoshal in Bengaluru; Editing by Janane Venkatraman, Diti Pujara and Alex Richardson)