




Falling prices aren’t making metro Phoenix condominiums more affordable as rising HOA fees, insurance costs and mortgage rates squeeze buyers and owners.
The median condo price has fallen to $315,000, its lowest level since 2021. But the median monthly HOA fee has climbed about 40% since 2020, and the average 30-year mortgage rate is up to 7.4%, according to Freddie Mac.
Tougher lending rules coming in 2027 could drive dues higher and make some condos more difficult to finance. Beginning in January 2027, Fannie Mae and Freddie Mac will begin requiring condo HOAs to put aside more money for repairs. If the associations don't increase their emergency funds, the mortgage giants could charge more for loans in the complex or stop backing them.
All are
driving up the cost of buying and owning a condo.
“The Valley condo market is frigid,” said Tina Tamboer, senior housing analyst with The Cromford Report.
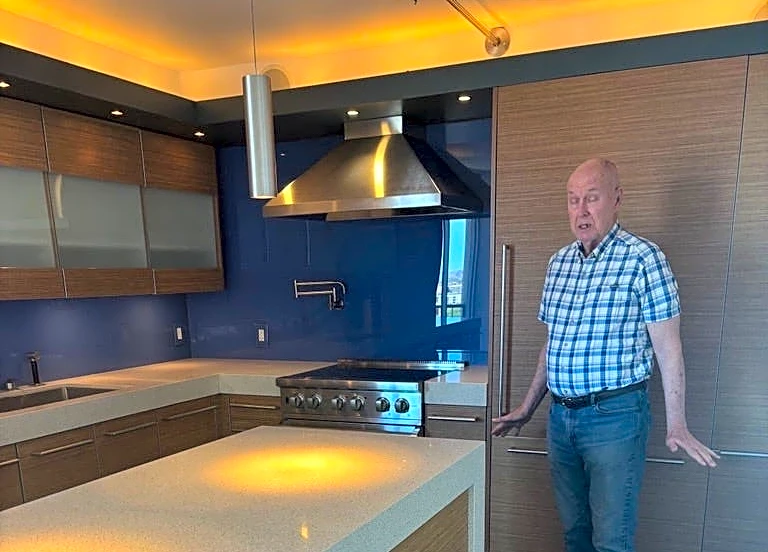
Tom and Mary Jeffries want to sell their upscale condo at central Phoenix’s 21-story Regency House. After trying for four months to find a buyer, the couple took it off the market. They just put it back on for $600,000, after originally listing it for $700,000.
“We pay higher HOA fees, but we get a pool, security at the front desk and other amenities,” said Tom Jeffries, who was on the Regency House HOA board and worked on increasing the building’s reserves. “What we get from the HOA is worth what we pay.”
The couple’s HOA fees are about $2,000 a month at the Regency House.
The Jeffries are still sold on condo living and bought one at Portland on the Park, nearer to downtown Phoenix. HOA fees are typically higher in that development next to Margaret T. Hance Park.
“I always tell condo buyers to figure out what they get from their HOA fees, so they aren’t surprised,” said Christa Lawcock, a Phoenix agent with Realty Executives, who has owned several Valley condos and recently bought another one in the Biltmore area. “Some HOA fees include electricity, water and security and can be a decent deal.”
Tougher to buy and own a condo
The median price of a Phoenix-area condo fell to $315,000 in mid-October, according to The Cromford Report, an Arizona real estate data and research firm. But lower condo prices don’t necessarily make them more affordable because of higher HOA and financing fees.
Metro Phoenix’s median monthly HOA fee is $374, reports Cromford. Valley HOA fees can range from a few hundred dollars to more than $2,000 a month in luxury complexes. The fees cover a development’s maintenance, insurance as well as amenities such as security, a clubhouse, a pool and landscaping.

Tamboer said the condo market’s woes are pushing more owners toward foreclosure, with condo notice of trustee sales inching up.
But she said the pre-foreclosure filings aren’t anywhere near the record high from the Great Recession and housing crash.
Home insurance rates jumped 71% across Arizona between 2020 and 2025 and now are higher than the state's annual property taxes, according to LendingTree’s most recent analysis of Quadrant Information Services data.
“Condo HOAs need to get up to speed financially,” said Tamboer, whose Phoenix condo fees climbed from $300 a month to $500 after her development got hit with an unexpected $15,000 water bill and didn’t have the reserves to cover it.
She’s hearing about condo HOAs across the Valley facing maintenance and other unexpected costs.
Condo sales have sagged to about 5,500 for the 12 months ended in August, according to Homes.com. That’s less than half the condo sales during the same period in 2021.
Due to sagging condo sales, the number of listings has climbed to about 2,700. That’s more than 1,000 higher than in 2021.
“Valley condo buyers and owners are getting knocked around in every direction, from insurance to financing,” said Trevor Halpern, real estate agent with Halpern Residential at eXp Realty. “It's the perfect storm and creating something of a bloodbath in the condo market."
Why the surprise HOA increases
Condo owners are getting hit with thousands of dollars in special assessments they didn’t expect.
Recent increases in condo HOA fees are mostly due to higher insurance rates and insufficient reserves for major improvements to roads, roofs and landscaping, particularly at older developments.
That’s why government-backed mortgage giants Fannie Mae and Freddie Mac are going to start requiring condo associations to set aside at least 15% of their annual dues in reserves to cover big repair costs starting in January 2027. Currently, the federal agencies only require condo HOAs to set aside 10%.
The new rules could mean higher dues for condo owners.
The new Fannie Mae and Freddie Mac rules could also keep condo buyers from getting conventional financing. If a condo complex can’t show it has 15% in reserves or get an exemption from the rule, the government agencies may not back mortgages or refinancing loans in the development.
The changes come after the 2021 Surfside condo collapse in Florida, which killed 98 people. Long-term maintenance problems were cited as part the reason behind the development collapse.
Lawcock said she’s seeing more Valley condos purchased with selling financing because it’s tougher for buyers to get conventional mortgages.
“When buyers can't get financing, sales don’t go through and prices go down,” she said.
What condo buyers should do
Condos are still some of the most affordable homes in metro Phoenix, and experts say buyers who do their homework can still find good deals.
Halpern said condos are still a great option but advises buyers to:
- Check the HOA’s reserve account.
- Find out about any planned special assessments.
- Research how often dues are increased.
- Find out what major repairs could be coming in the next five to 10 years.
Lawcock tells her clients to research what they actually get for their HOA fees and look into different types of financing to get the best deal.
This article originally appeared on Arizona Republic: Why falling prices aren’t making Valley condos more affordable