


The Upgrade: What Is FedNow?
First, let’s clear something up: FedNow is not a new currency, a digital dollar, or the government snooping on your coffee purchases. It’s best to think of it as an upgrade to the banking system's plumbing. For decades, moving money between banks was
often a slow, clunky process, especially on nights and weekends. FedNow, launched by the Federal Reserve, is a modern payment "rail" that allows banks and credit unions to process payments instantly, 24/7. The money you send to a friend for pizza on a Saturday night can now arrive in their account in seconds, not days. For individuals and small businesses, this means better cash flow and fewer worries about checks clearing. However, you don't use FedNow directly; it's a service your bank must choose to adopt to offer you instant payment features. It’s a welcome modernization, but it’s an evolution, not a revolution.
The Concept: What Is a CBDC?
A Central Bank Digital Currency, or CBDC, is where things get more futuristic and far more controversial. Unlike FedNow, which just moves existing commercial bank money faster, a CBDC would be a new form of money altogether—a direct liability of the Federal Reserve, just like physical cash. Imagine a "digital dollar" you could hold in a wallet managed by the Fed or a designated commercial bank. Proponents argue a CBDC could make payments more efficient, promote financial inclusion for the unbanked, and help the U.S. dollar maintain its global dominance. But critics raise serious red flags. The primary concern is privacy. A government-issued digital currency could create a permanent, searchable record of every transaction a person makes. It also raises questions about financial freedom and the potential for government overreach. The Federal Reserve has stated it would not issue a CBDC without clear support from Congress and has made no decision to do so.
The Disruptor: What About Crypto?
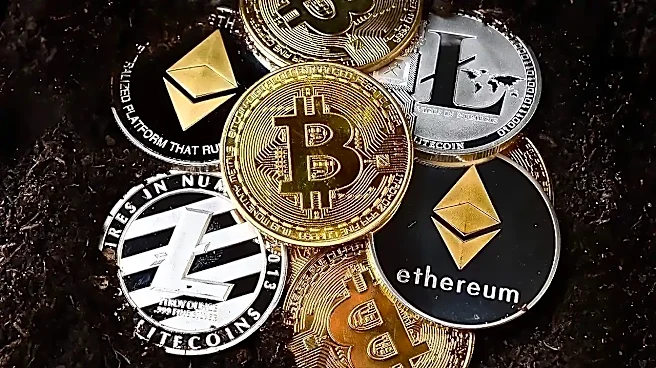
Cryptocurrencies like Bitcoin and Ethereum were born from a deep skepticism of the very institutions behind FedNow and CBDCs. Their core promise is decentralization: a financial system without banks or governments acting as intermediaries. Transactions are recorded on a public ledger called a blockchain, secured by a distributed network of computers. For advocates, this means more privacy (though transactions are often pseudonymous, not fully anonymous), censorship resistance, and freedom from the policies of central banks. However, the crypto world is plagued by its own set of problems. Extreme price volatility, high-profile collapses of exchanges like FTX, security risks, and its use in illicit activities have made many potential users wary. Furthermore, the promise of true decentralization is often undercut by the reality of a few large players controlling exchanges and mining operations.
The One Thing Critics Got Right
So, what’s the single truth the critics have nailed? It's that FedNow, CBDCs, and Crypto are all solutions driven by institutional or ideological goals, not by a pressing, widespread demand from the average American. None of them, in their current form, are primarily designed to solve the everyday financial problems of most people. FedNow is a necessary, but backend, modernization for banks. A potential CBDC is largely a government tool to maintain control over monetary policy in a digital age. And cryptocurrency is an ideological project aimed at opting out of the traditional system. Polls show that while people want faster payments, their main financial struggles are not about settlement times. They are about high banking fees, lack of access to credit, and the difficulty of building wealth. These new technologies are fascinating tools, but they are tools in search of a problem for the median consumer. Critics are right to point out that the debate is dominated by technologists and policymakers, while the actual needs of the public—simplicity, affordability, and trust—are often treated as an afterthought.