
What's Happening?
The U.S. trucking industry experiences predictable seasonal fluctuations in freight demand, significantly impacting capacity and spot rates. These patterns are driven by weather, agricultural harvests,
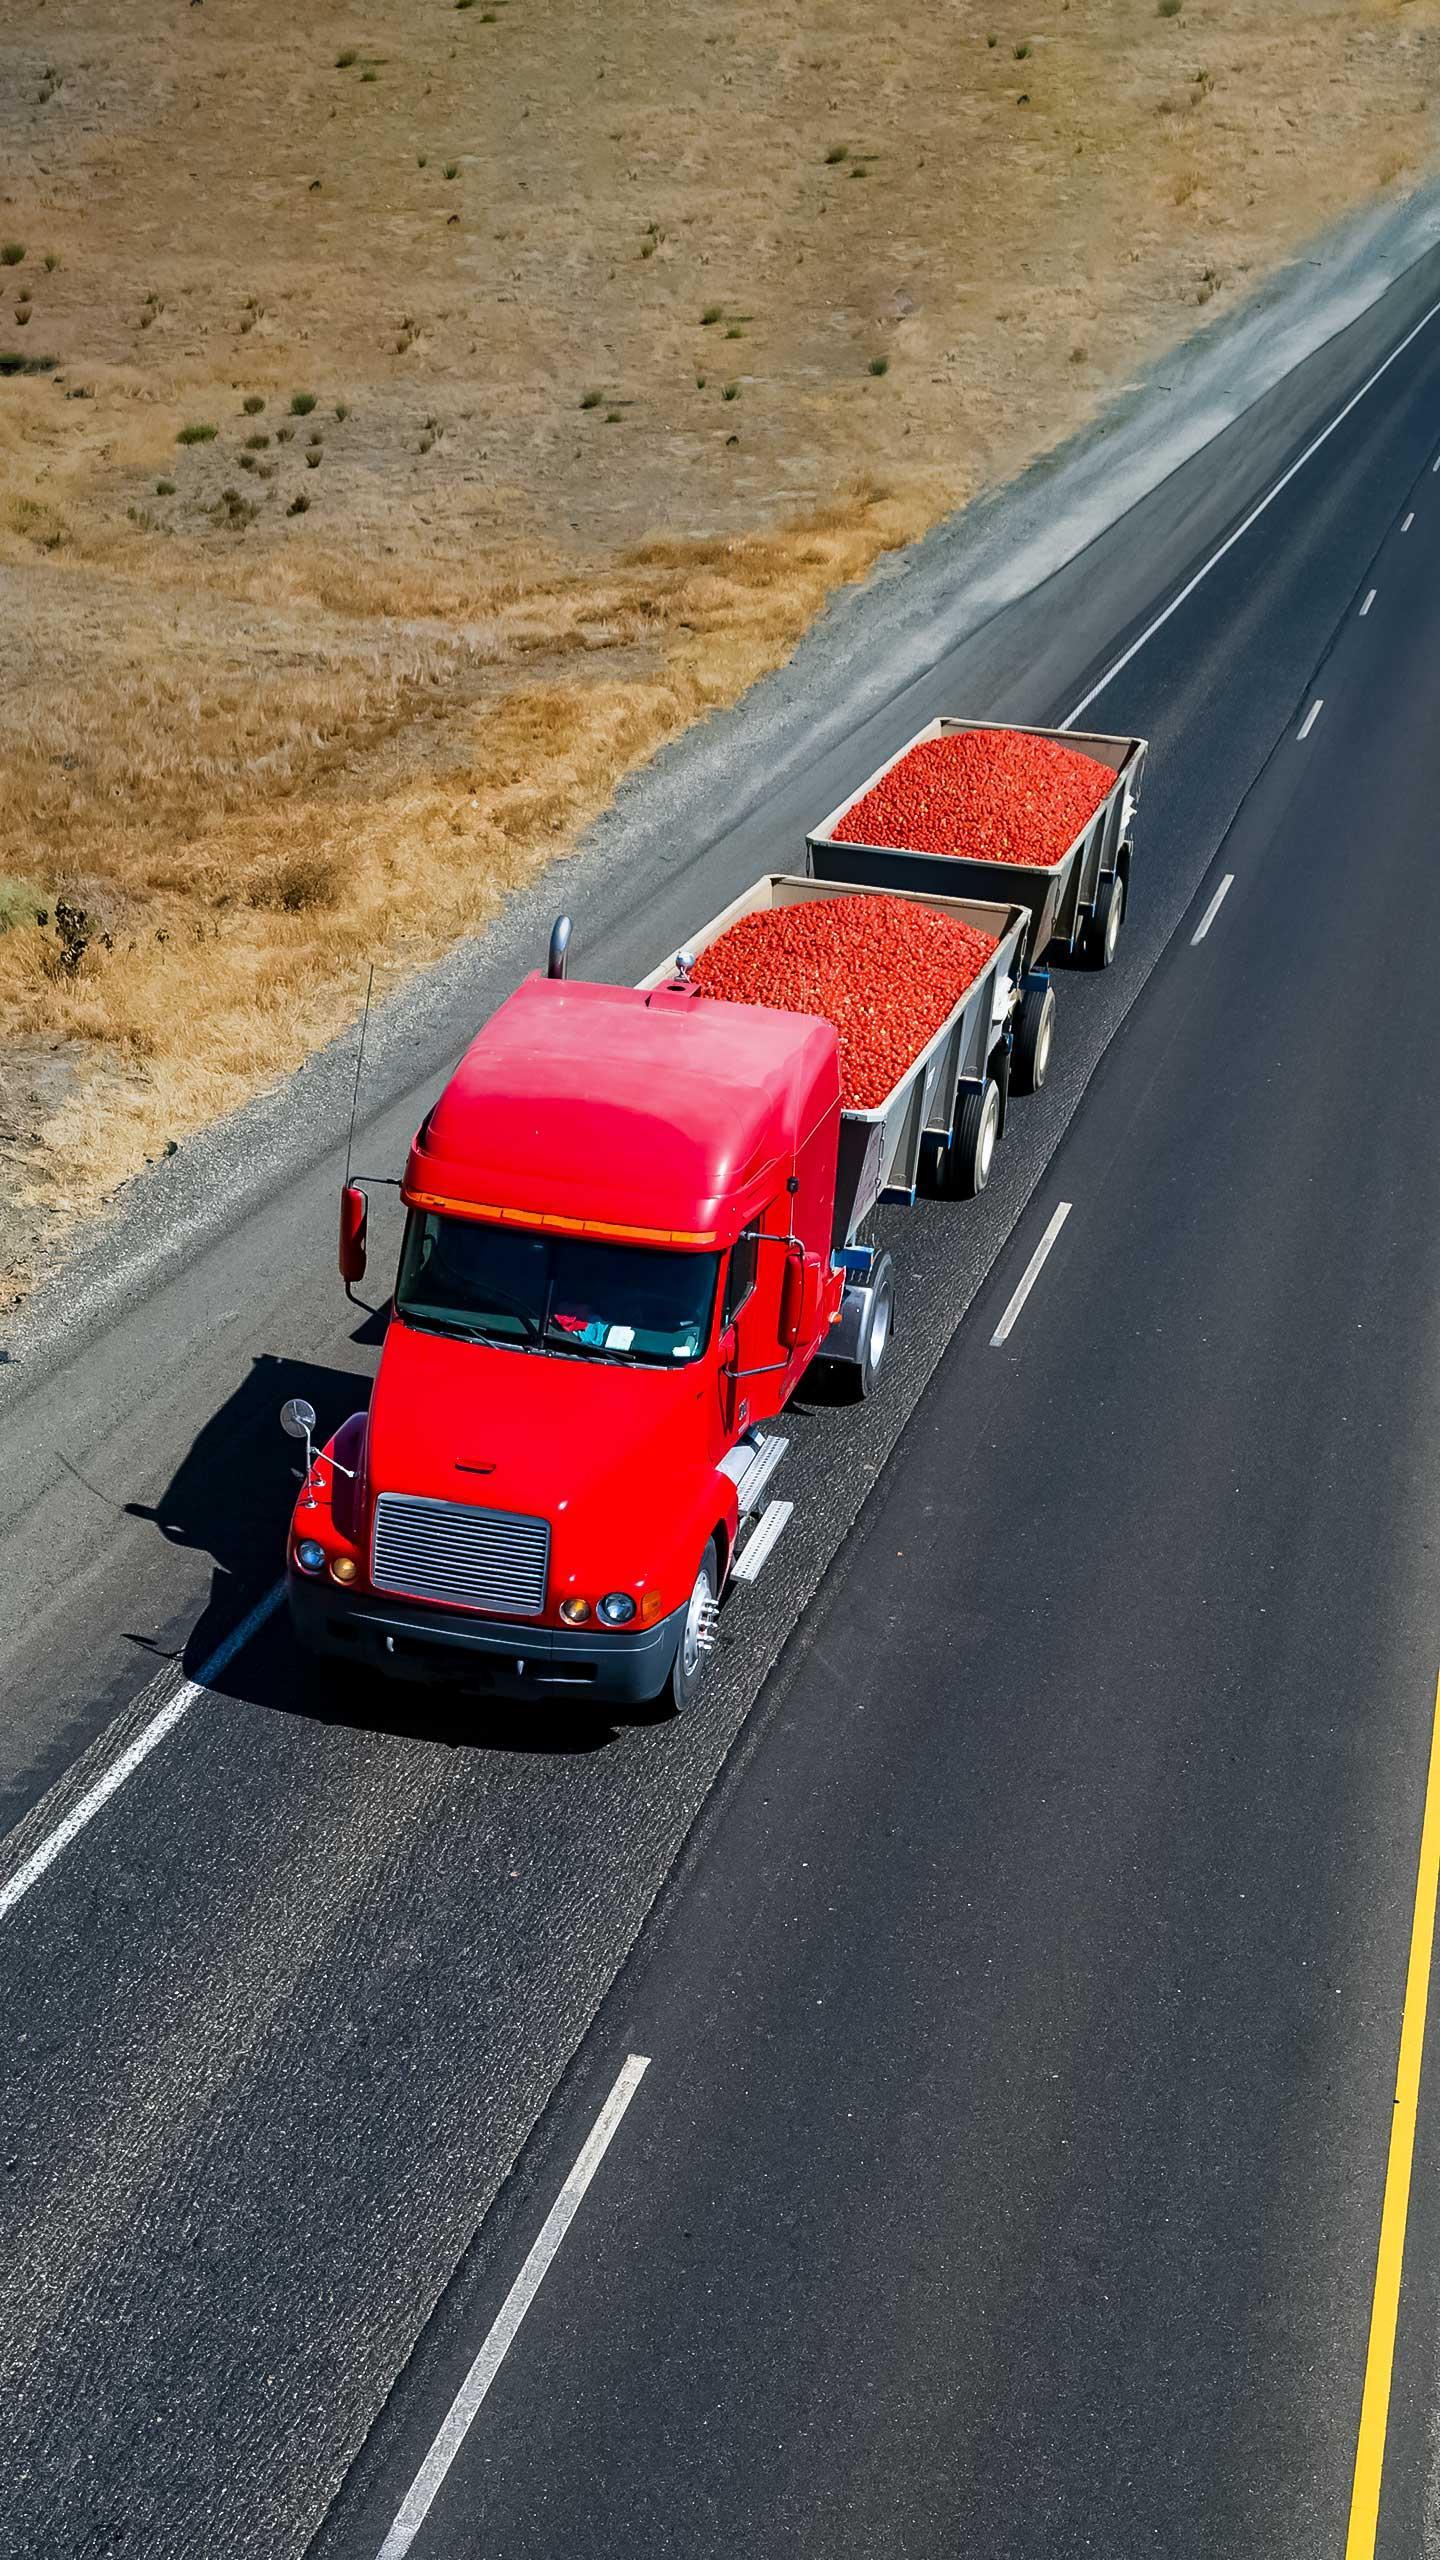
and consumer habits. Produce harvests create regional surges in demand for refrigerated trailers, starting in the South and moving northward. Construction seasons, typically warmer months, increase demand for flatbed capacity to transport raw materials and heavy machinery, with stronger volatility in northern regions. Retail seasons, including back-to-school shopping (June-September) and holiday shopping (October-December), tighten dry van capacity as shippers rush to stock shelves and fulfill online orders. The period from November to December is considered 'peak shipping season,' where autumnal harvests, construction closeouts, and holiday shopping overlap, creating the year's greatest strain on for-hire capacity and leading to high utilization and strong spot rates. Conversely, late December through Q1 often sees lower demand and rates.
Why It's Important?
Understanding these seasonal freight demand patterns is crucial for the U.S. trucking industry, including carriers, shippers, and logistics providers. For carriers, it allows for strategic positioning of equipment, effective cash flow management, and optimized freight pricing throughout the year. During peak seasons, carriers can maximize revenue, while slower periods can be used for training or technology pilots. Shippers need to anticipate these fluctuations to plan their logistics and avoid higher costs or capacity shortages. The interplay between different trucking segments (reefer, flatbed, dry van) means that tightness in one area can create a domino effect across the entire market. These patterns directly influence the cost of goods, supply chain efficiency, and ultimately, consumer prices across the nation.
What's Next?
As the industry moves through the calendar year, stakeholders will continue to monitor these seasonal trends to make informed operational and financial decisions. Carriers will adjust their fleet deployment and pricing strategies in anticipation of upcoming demand spikes or lulls. Shippers will negotiate contracts and plan inventory movements with these seasonal pressures in mind. The period immediately following peak season (late December through Q1) will likely see carriers focusing on internal improvements and preparing for contract bid season (January-March). The industry will also continue to adapt to external factors like economic shifts or unexpected events that can alter typical seasonal patterns, requiring flexibility and real-time adjustments to logistics and capacity management.
Beyond the Headlines
The cyclical nature of freight demand highlights the intricate connection between various sectors of the U.S. economy—agriculture, construction, and retail—and the critical role of the trucking industry as their backbone. These seasonal rhythms underscore the vulnerability of supply chains to disruptions, as peak demand periods leave little room for error. Furthermore, the impact on truck drivers is significant; many plan their availability around these demand spikes, working intensely during peak season and taking time off during slower periods. This can affect driver retention and recruitment, as carriers must balance the need for capacity with driver welfare. The predictability of these patterns also drives innovation in logistics technology, with companies developing advanced analytics and forecasting tools to better manage capacity and demand fluctuations.