
What's Happening?
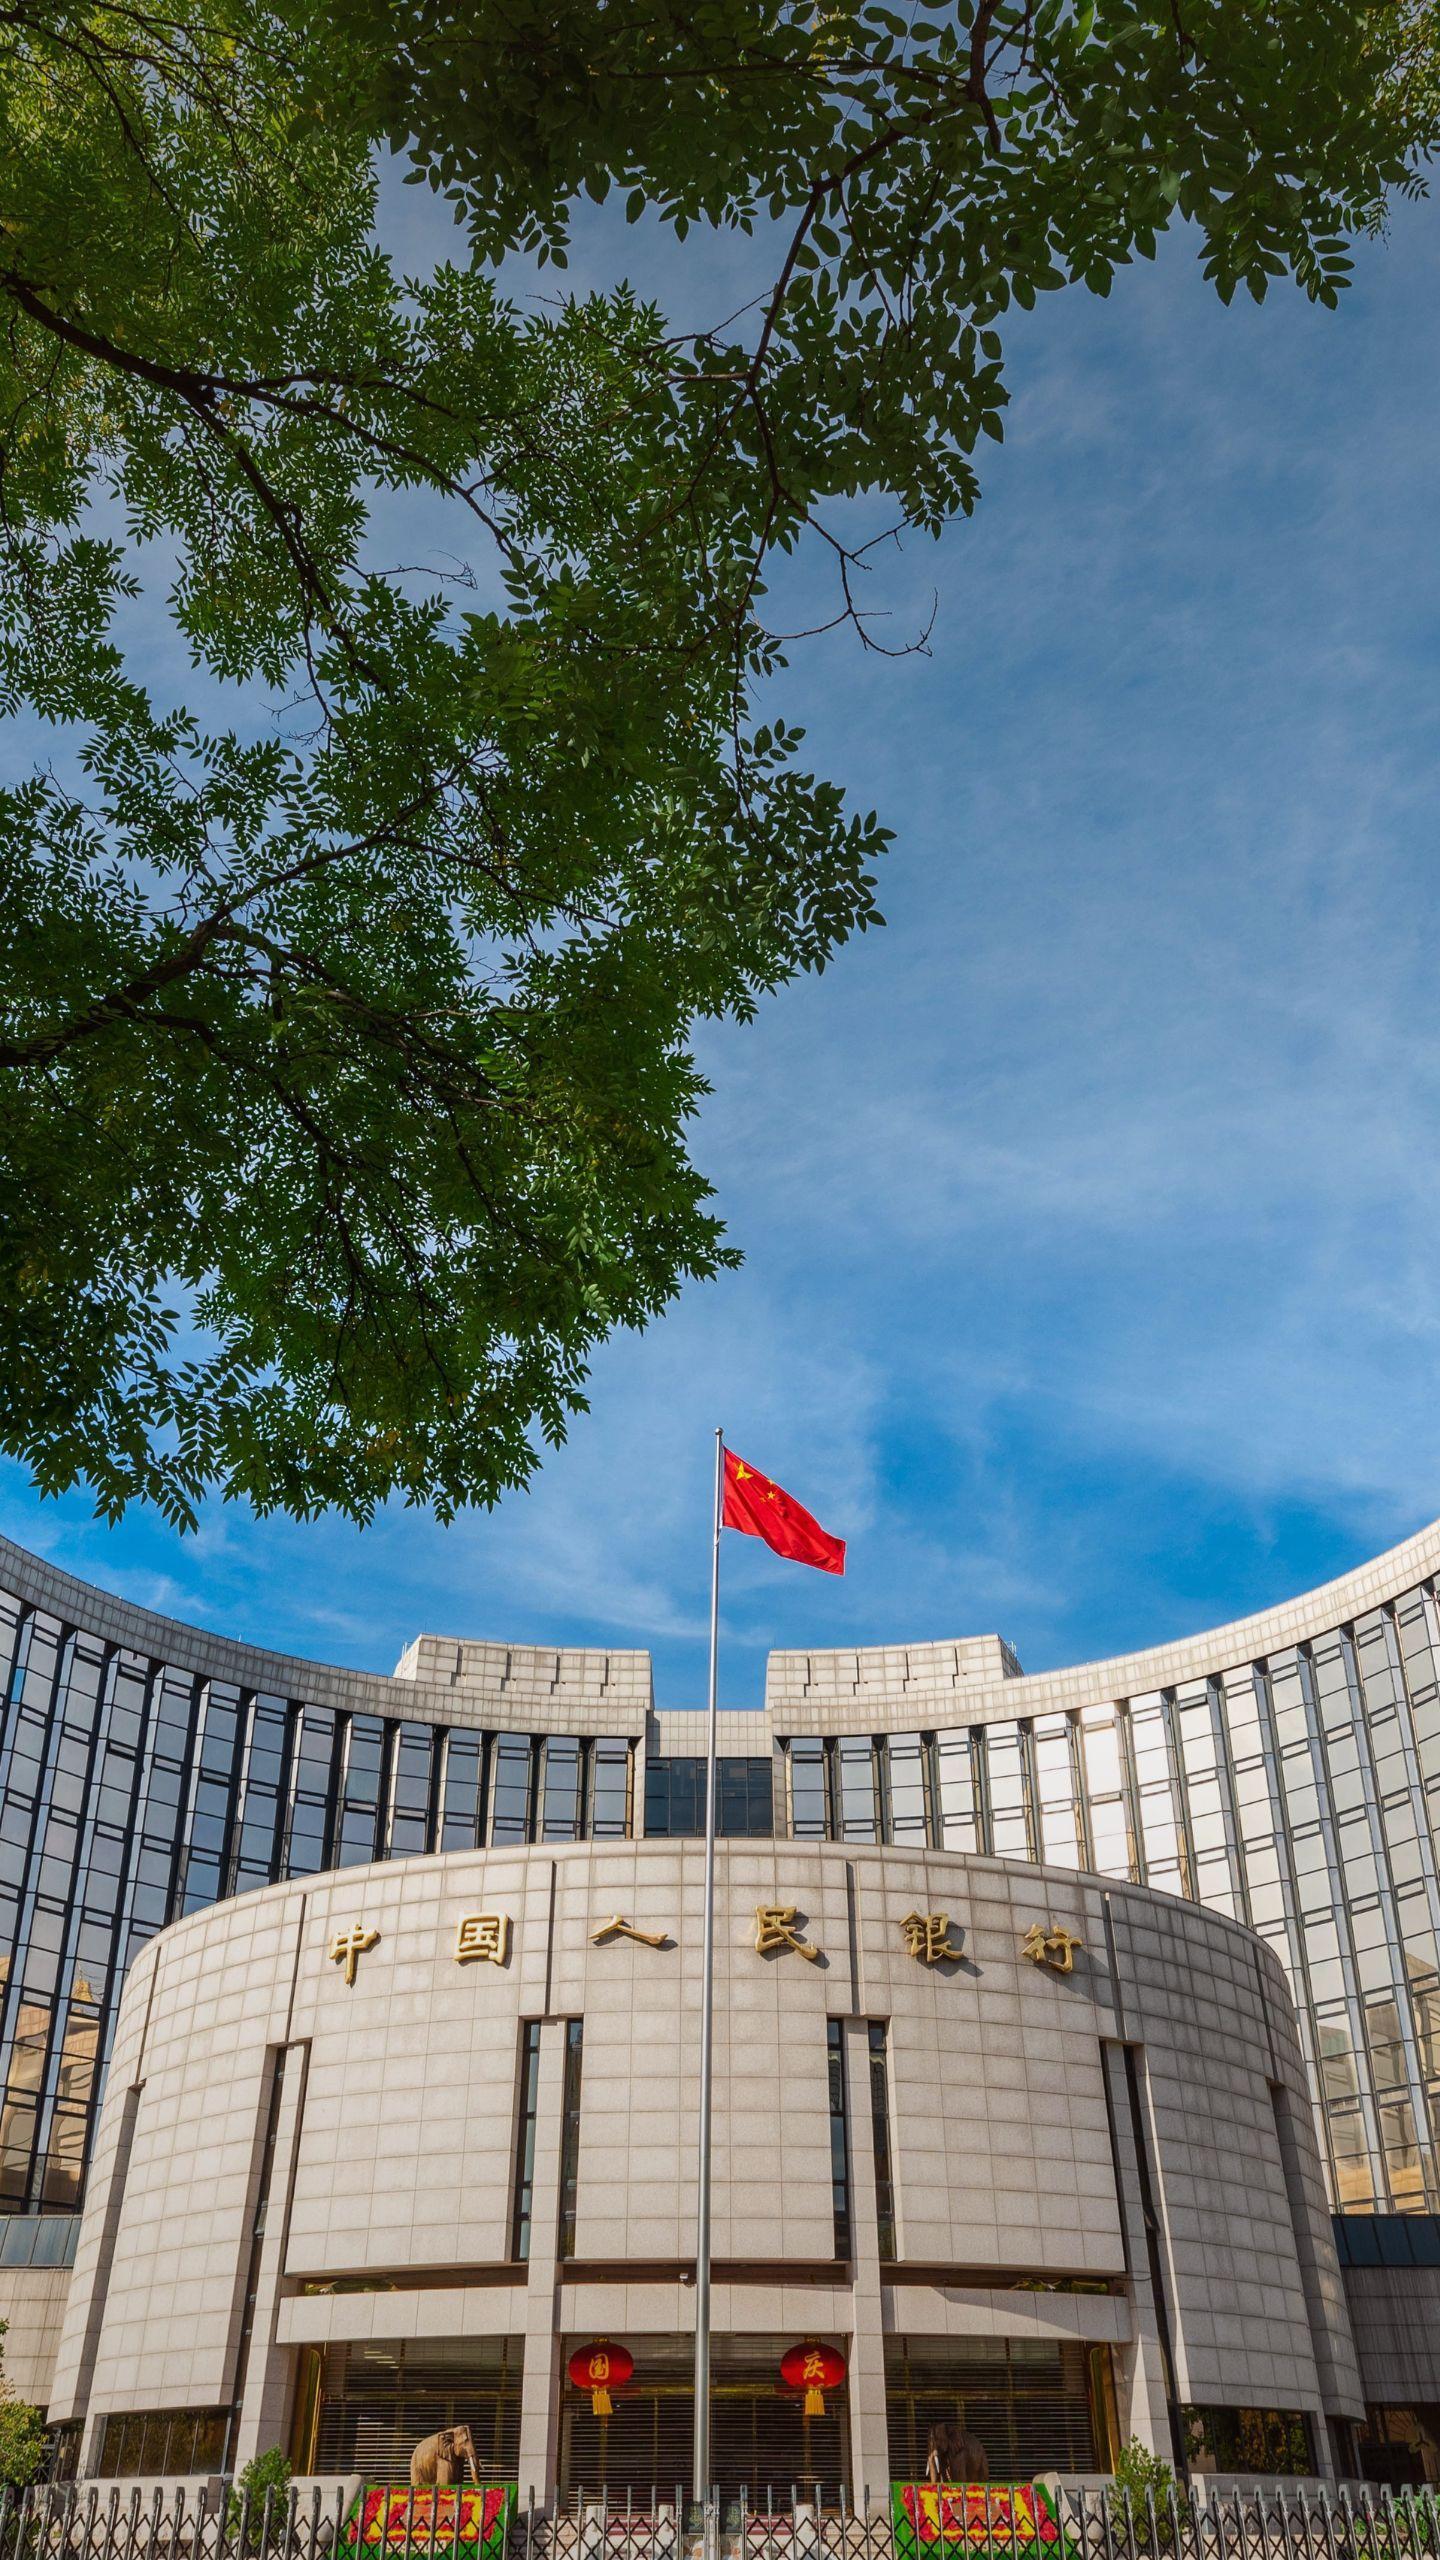
China's central bank is reportedly gauging market interest in a potential tax on income derived from government bonds. This move comes as yields on these bonds are hovering near historical lows. The People's
Bank of China (PBOC) conducted a survey last month, questioning several lenders about the potential impact of a 25% tax on interest income from their holdings of central and local government bonds. The survey aimed to understand how such a tax would influence their appetite for these securities. This initiative suggests that Chinese authorities are exploring measures to potentially increase bond yields, which have been a concern due to their low levels. The discussions are currently not public, with sources requesting anonymity due to the sensitive nature of the information. The exploration of such a tax indicates a potential shift in China's financial policy regarding its domestic bond market.
Why It's Important?
A tax on government bond interest in China could have significant implications for both domestic and international financial markets. For China, it could lead to an increase in bond yields, making these securities more attractive to investors and potentially helping to manage the country's debt profile. However, it could also deter some investors, impacting liquidity and demand for Chinese government bonds. Globally, as China is a major player in the bond market, any significant policy change could ripple through international financial systems. Investors holding or considering Chinese government bonds would need to reassess their strategies, potentially leading to shifts in capital flows. The move could also set a precedent for other nations facing similar challenges with low bond yields, influencing global financial policy discussions and investment trends. The outcome of these explorations will be closely watched by financial institutions and governments worldwide.
What's Next?
The immediate next step involves further internal discussions and assessments by Chinese authorities based on the feedback from market participants. It is unclear when or if a formal proposal for a bond interest tax will be introduced. Should China decide to proceed, it would likely involve a phased implementation or a pilot program to gauge market reaction and mitigate potential disruptions. Financial institutions and investors will be closely monitoring official announcements from the People's Bank of China and other relevant government bodies for any indications of policy changes. The introduction of such a tax would necessitate adjustments in investment strategies for both domestic and foreign entities with exposure to Chinese government bonds, potentially leading to reallocations of portfolios and a re-evaluation of risk-reward profiles in the Chinese market.
Beyond the Headlines
The potential tax on bond interest in China could signal a broader strategic shift in how the country manages its financial markets and economic growth. It might reflect a desire to rebalance investment incentives, potentially encouraging capital to flow into other sectors of the economy or to stimulate domestic consumption. Ethically, such a tax could be viewed as a way to generate revenue for public services or to address wealth inequality, depending on its design and implementation. Legally, the framework for such a tax would need to be carefully constructed to ensure fairness and avoid unintended consequences for market stability. Culturally, it could represent a move towards greater state intervention in financial markets, aligning with China's unique economic model. In the long term, this development could contribute to a more complex and regulated financial landscape in China, influencing its integration with global financial systems and its attractiveness as an investment destination.