

Understanding the Repo Rate Hike
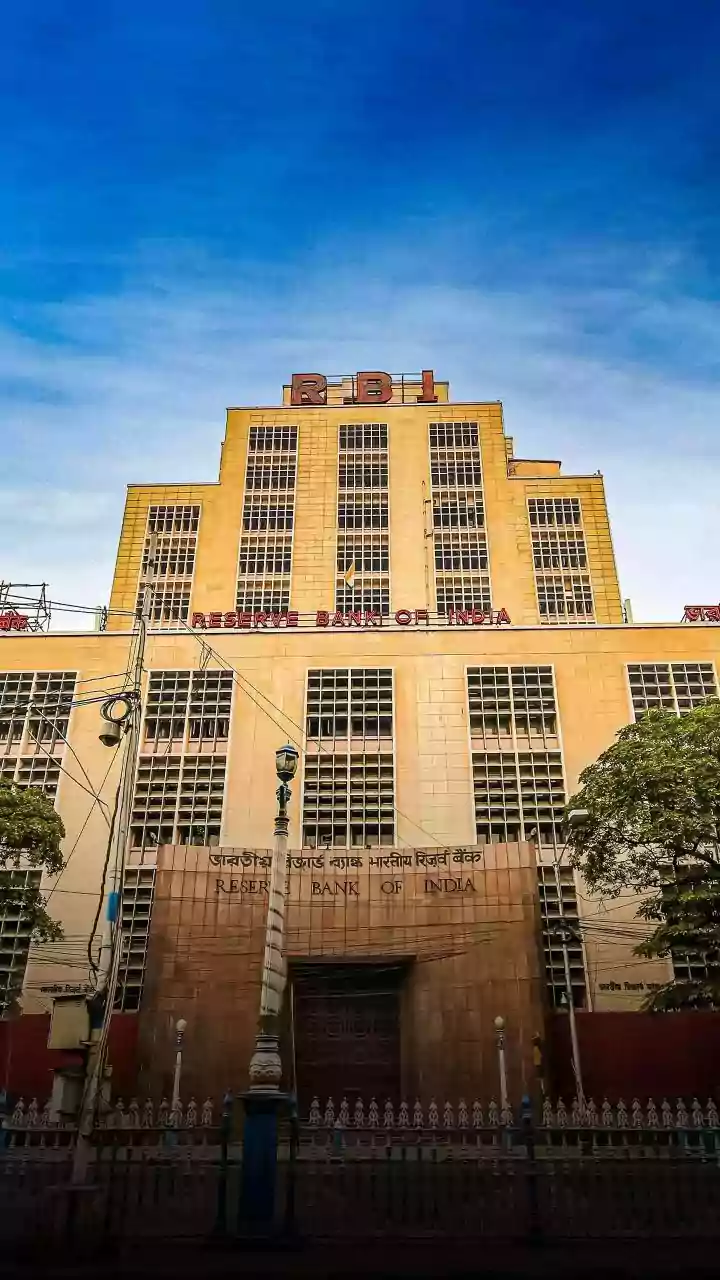
On October 7, 2026, the RBI's Monetary Policy Committee (MPC) announced a 25-basis-point (0.25%) hike in the repo rate, bringing it to 5.50%. This is the first increase since February 2023 and signals a 'calibrated tightening' of monetary policy. The
repo rate is the interest rate at which the central bank lends money to commercial banks. When the RBI makes it more expensive for banks to borrow, banks, in turn, increase the interest rates on loans they offer to customers, including home, auto, and personal loans. The move comes amid rising inflation concerns and a resilient domestic economy.
How This Affects Your Loan
If you have a loan with a floating interest rate, this hike will likely impact you. Most floating-rate loans in India are now linked to an external benchmark, which is often the RBI's repo rate. When the repo rate goes up, your bank will pass on the increased cost to you. This is done in one of two ways: either your monthly EMI amount is increased, or your loan tenure (the total repayment period) is extended. For example, a 0.25% rate increase on a ₹50 lakh home loan with a 20-year tenure could increase the monthly EMI by approximately ₹759. Banks often prefer to extend the tenure to avoid a sudden shock to your monthly budget, but this means you end up paying more interest over the life of the loan.
Step 1: Assess Your Financial Situation
The first step is to get a clear picture of your finances. Review your monthly budget to understand how much flexibility you have. Determine if you can comfortably absorb a higher EMI without straining your essential expenses and savings goals. Contact your lender to get precise details on how they are adjusting your loan. They will clarify whether your EMI will increase or if the tenure will be extended. Understanding this is crucial for making your next move.
Step 2: Decide Between Higher EMI or Longer Tenure
You may have a choice between paying a higher EMI or accepting a longer repayment period. Increasing your EMI helps you pay off the loan faster and reduces the total interest you pay over the long run. This is a good option if your income has increased or you can cut back on discretionary spending. On the other hand, extending the tenure keeps your monthly payment the same, which can be easier on your immediate cash flow. However, be aware that this option is more expensive in the long term as more interest accrues over the extended period.
Step 3: Consider Making Prepayments
One of the most effective strategies to counter a rate hike is to make partial prepayments towards your loan principal. Even small, regular prepayments can significantly reduce your outstanding principal, which in turn lowers the total interest burden and can shorten your loan tenure. If you receive a bonus, a windfall, or have accumulated savings, using a portion of it to prepay your loan can offer substantial long-term benefits and help you become debt-free sooner.
Step 4: Explore a Loan Balance Transfer
A rate hike is a good time to review the market and see if other lenders are offering more competitive interest rates. You could consider a home loan balance transfer, which involves moving your outstanding loan from your current bank to a new one that offers a lower rate. While this can lead to significant savings, it is important to calculate the associated costs, such as processing fees and other charges, to ensure the switch is financially beneficial. This option is most effective for borrowers with a strong credit history and a significant remaining loan tenure.