
A Cosmic Traffic Jam
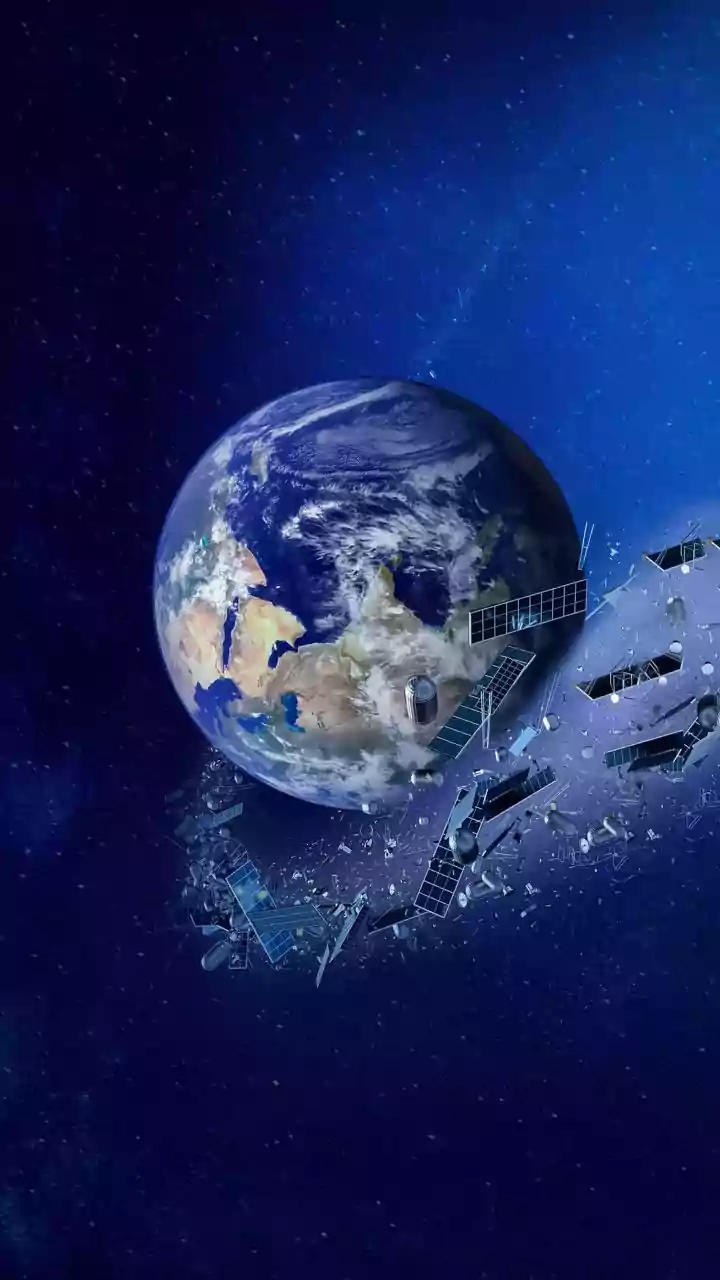
Since 1957, humanity has been launching objects into space, and we've left a lot of junk behind. More than 34,000 pieces of debris larger than 10 centimeters are currently tracked, including defunct satellites and spent rocket stages. Added to this are millions
of smaller fragments, each travelling at speeds up to 28,000 kilometers per hour. At that velocity, even a tiny paint chip can inflict catastrophic damage on an active satellite. This growing cloud of debris is increasing the risk of a cascade of collisions known as the Kessler Syndrome, a scenario where collisions create more debris, which in turn causes more collisions, potentially rendering entire orbits unusable for generations. The rapid deployment of mega-constellations for global internet by companies like SpaceX and Amazon adds thousands of new satellites, dramatically increasing the density and collision risk in Low Earth Orbit (LEO).
The Cleanup Crew Economy
In response to this growing threat, a dedicated space-debris removal market is taking shape. Various market reports project explosive growth, with some estimates suggesting the market could grow from around USD 143 million in 2025 to over USD 9.5 billion by 2035, demonstrating a compound annual growth rate exceeding 40%. This growth is driven by the urgent need to protect valuable space assets. The market primarily revolves around Active Debris Removal (ADR), where specialized spacecraft are designed to rendezvous with, capture, and deorbit large pieces of debris. Today, most revenue in the broader sector comes from tracking and situational awareness services, but the physical removal segment is where the most significant future growth is expected.
Innovators and Their Cosmic Tools
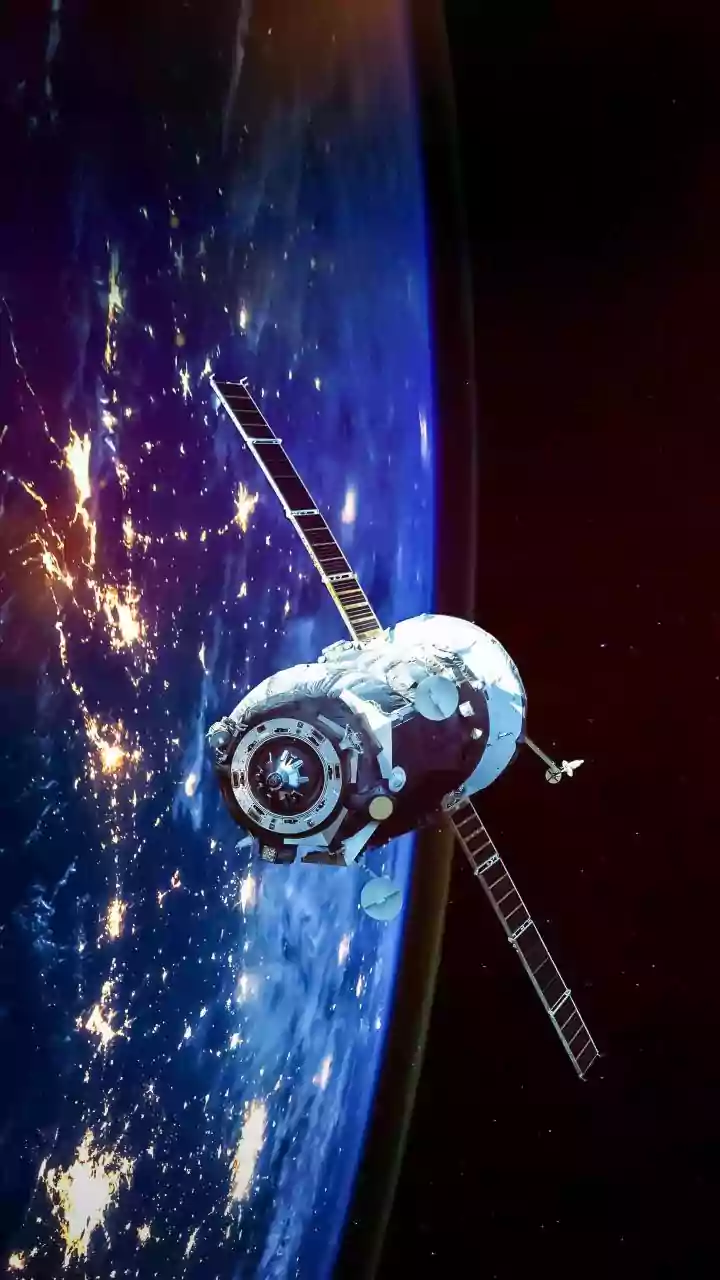
A new generation of aerospace companies is developing an array of technologies fit for a sci-fi film. Japan's Astroscale and Switzerland's ClearSpace are two of the leading pioneers. Astroscale has already demonstrated the ability to approach and inspect a piece of debris in orbit and is preparing its ELSA-M mission, which aims to be the world's first commercial active debris removal mission. ClearSpace was contracted by the European Space Agency (ESA) for a mission to capture and deorbit a piece of a rocket adapter. The technologies being tested are diverse and include robotic arms for gentle capture, nets for larger objects, powerful magnets, and even harpoons. These missions are incredibly complex, requiring autonomous rendezvous and capture capabilities to safely handle tumbling, non-cooperative targets.
The Black Hole of Regulation
Despite the technological progress, the market's biggest challenge is the lack of a clear and binding international legal framework. The 1967 Outer Space Treaty, the foundation of space law, states that a nation retains ownership of and jurisdiction over its space objects in perpetuity. This means a company cannot simply remove another country's defunct satellite without permission, as it is not legally considered abandoned property. Obtaining this consent can be a diplomatic nightmare. Furthermore, liability is a major concern; if a removal mission goes wrong and creates more debris, the launching state of the removal company could be held liable for any damage. While voluntary guidelines exist from the UN and others, and some nations like the U.S. have implemented stricter rules like the FCC's 5-year deorbit mandate for LEO satellites, there is no global enforcement mechanism to compel cleanup.
Who Foots the Bill?
This leads to the ultimate question: who pays? The high cost of removal—a single mission can cost tens of millions of dollars—creates a classic 'tragedy of the commons' scenario. It is in everyone's long-term interest to have clean orbits, but it is in no single operator's short-term financial interest to pay to remove an object they didn't launch. Currently, the primary customers are government space agencies like ESA and JAXA, which are funding demonstration missions to prove the technology. The commercial market depends on satellite operators, insurance companies, and national governments recognizing that the cost of removal is less than the cost of losing a billion-dollar satellite or a critical national security asset. Regulatory pressure is slowly creating a customer base, as new rules increasingly require satellite operators to have a plan for end-of-life disposal, creating a market for 'removal-as-a-service' solutions.