

By Jamie McGeever
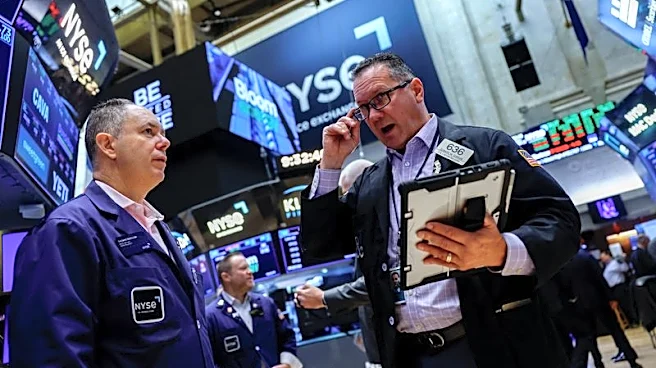
ORLANDO, Florida, Oct 6 (Reuters) - The S&P 500 and Nasdaq hit record highs on Tuesday as a pause in the bond market sell-off and steady oil prices paved the way for a tech- and AI-led wave of buying, with investors entering the third-quarter earnings season with a great sense of optimism.
In my column today, I look at the potential red flags in the US bond market from Treasury's regular debt auctions. Yields are rising, and that's not necessarily a sign of stress, but big "tails"
at these auctions are. Investors will be scrutinizing the underlying data in these sales extremely closely.
Today's Key Reads
• Record imports push US trade balance deep into the red in August
• US software stocks scale fresh 2026 highs as AI disruption worries fade
• Slowdown in money-fund cash flow hits short-term Treasuries
• Early ECB leadership change could worsen Paris bond jolt: Mike Dolan
• BOJ may signal underlying inflation has hit 2% goal, sources say
• Today's Key Market Moves STOCKS: Japan +1% to 3-month high, Europe +0.5%, UK +0.4%. S&P 500 and Nasdaq make new highsSECTORS/SHARES: Ten sectors on the S&P 500 rise, only healthcare falls. Utilities +3%, consumer discretionaries +1.4%. Software stocks +1% to 2026 high. Marvell Technology +6%, Cisco +4.5%, Nvidia hits all-time high. Seagate Technology -14%.FX: US dollar slips 0.3% from Monday's 17-month high, euro recovers ground. Canadian dollar +0.4%.BONDS: Japan 30-year yield hits new high 4.25%. French/German 10-year spread shrinks 8 bps, biggest decline since the pandemic. US yields cool 3-4 bps; 3-year auction goes smoothly, clears at highest yield since 2006.COMMODITIES/METALS: Oil steady, Brent holding around $100/bbl. Gold +0.7% to $4,170/oz.
Today's Talking Points:
Imbalances
The Trump administration's desire to see the US trade deficit narrow meaningfully — or even at all — is frustrated yet again. Figures on Tuesday showed that record imports in August pushed the trade gap out to its widest in 17 months. Tariffs, trade wars, re-shoring, and "trillions" of investment from abroad (according to Trump), are all failing, certainly by this metric.
While record imports point to robust consumer demand and spending, the deficit they deliver cuts GDP growth. The Atlanta Fed's GDPNow model estimate of Q3 growth was trimmed a tenth of one percent to 3.7% on Tuesday after the trade data. Against the backdrop of China's record-breaking trade surplus, the US deficit is also a reminder of the risks posed by widening global imbalances.
Crude awakening
The US-Iran war is now in its eighth month, and the Strait of Hormuz has ostensibly been closed for that entire time too. As such, it's a surprise that oil and related energy prices aren't even higher than they are. The reason oil is $100 a barrel and not $150 or even $200 seems to be the supply of crude flowing from the region is far greater than many had thought. Vitol's CEO on Tuesday said up to 14 million barrels a day are being shipped from the Middle East.
Which is just as well, because the world has nearly burned through its stockpile buffer, according to industry executives. Governments and international agencies are releasing reserves into the market but they are drops in the ocean — the IEA is preparing to release 100 million barrels of crude and diesel, but that barely covers one day of global oil demand. Once reserves run dry and the war is still raging, then what?
Just a minute
The Federal Reserve on Wednesday publishes the minutes of its September 15-16 policy meeting. They will be closely scrutinized, as always, for signals about policymakers' thinking on the likely path for rates in the coming months. But it is already looking like the hawkish posture behind the unanimous vote to raise rates three weeks ago may already be fraying.
Several officials, beginning with New York Fed President John Williams, have indicated they are in no rush to follow up with another hike immediately. The incoming hard economic data seem to support that stance too — PCE inflation and non-farm payrolls were both softer than expected. Rates futures currently show an 80-20 chance of no change later this month, compared with a 70-30 probability of a hike only a week ago.
What could move markets tomorrow?
• India interest rate decision
• Japan tankan index (October)
• Germany industrial production (August)
• US Treasury sells $39 billion of 10-year notes at auction
• US Federal Reserve publishes minutes of September 15-16 meeting
Want to receive Trading Day in your inbox every weekday morning? Sign up for my newsletter here. Opinions expressed are those of the author. They do not reflect the views of Reuters News, which, under the Trust Principles, is committed to integrity, independence, and freedom from bias.
(Reporting by Jamie McGeever; Editing by Nia Williams)