
By Tom Sims and Matthias Inverardi
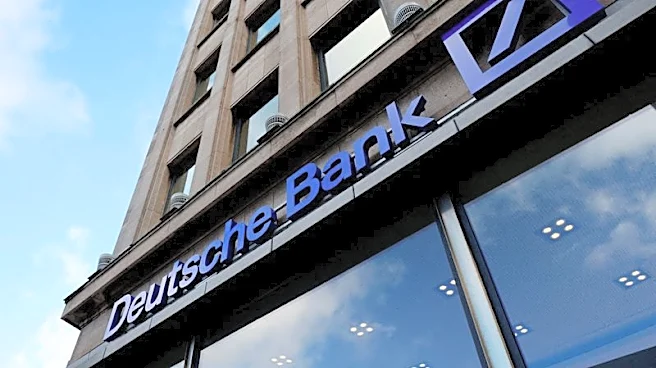
FRANKFURT, Nov 17 (Reuters) - Deutsche Bank shares fell 5.2% in early trade on Tuesday after it responded to a series of media reports based on leaked documents, saying
the incidents reported "date back many years" and that the bank had improved its controls.
The reports from a consortium of international journalists appeared in publications including Der Spiegel, the Financial Times and the New York Times and claimed to shed light on the bank's interactions with clients that included Russian oligarchs, US President Donald Trump and the late financier Jeffrey Epstein.
"The matters ... date back many years, in some cases as much as two decades," a Deutsche Bank statement said.
For years, Deutsche Bank has been trying to rebuild its reputation after penalties tied to anti-money laundering controls and other compliance failings.
Under Christian Sewing — CEO since 2018 — Deutsche Bank has restored profits, but compliance failings have resurfaced from time to time. One of the most recent was when details of its client relationship with Epstein were laid bare in US Department of Justice files released early this year.
"Deutsche Bank is a different bank today and remains focused on executing its strategy, which has proven successful, as evidenced by record profits in 2025 as well as in recent quarters," the bank said on Tuesday.
The reports, which Reuters was not able to verify immediately, are based on 15 million leaked records that include emails and meeting minutes, the New York Times said.
The documents were obtained by two journalists from India and South Africa respectively and analysed by a consortium of more than 200 journalists.
“Given the legacy nature of these matters, any potential financial impact is not expected to be meaningful, if there is any impact at all," Deutsche Bank said.
(Reporting by Tom Sims and Matthias InverardiEditing by Friederike Heine and David Goodman)