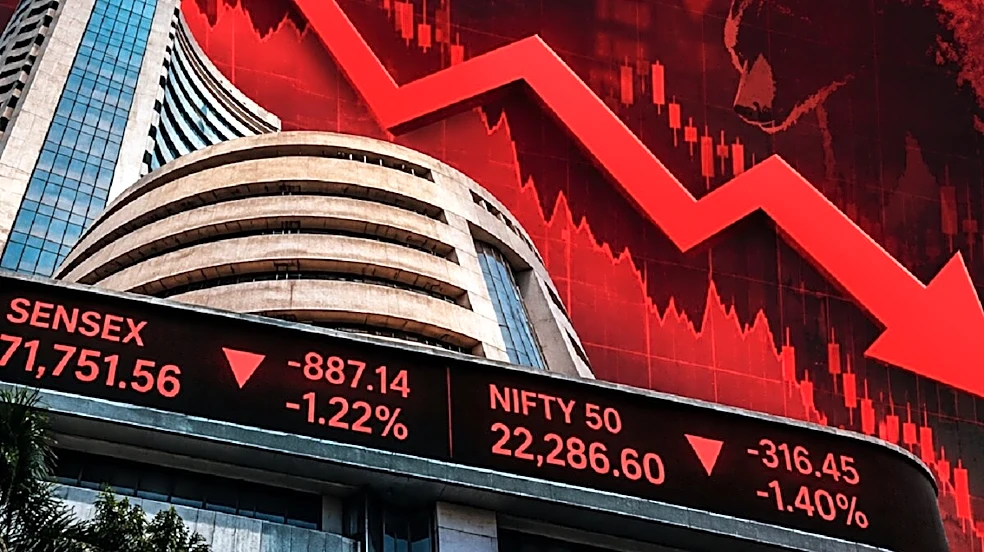
Stock Market Today, October 23: The domestic equity markets extended their losses in the early trade on Friday, October 23, as rising crude oil prices, concerns over energy supply disruptions and heavy selling across broader markets weighed on investor sentiment. Brent crude’s sharp rally to a five-month high in the previous session heightened concerns over inflation, while rising volatility added to market nervousness, with the Sensex falling nearly 1,280 points from the day’s high and the Nifty declining to near 22,450.
The sell-off intensified across metal, auto, realty and banking stocks, with smallcap and midcap shares witnessing deeper losses. Information technology stocks remained a relative outperformer, offering limited support to the
frontline indices.
As of 10:52 am, the BSE Sensex was trading at 72,740.77, down 508.62 points, or 0.69%. The index opened at 73,665.64 and touched an intraday high of 73,766.51 before falling to a low of 72,487.47, a crash of 1,279.04 points from the day’s high.
The NSE Nifty 50 declined 229.20 points, or 1.01%, to 22,458.45. The index opened at 22,742.20 and hit a high of 22,787.25 before slipping to an intraday low of 22,407.05.
Selling pressure was significantly stronger in the broader market. The Nifty Smallcap 100 plunged 3.63%, while the Nifty Midcap 100 declined 2.59%. The Nifty Next 50 fell 2.86%, and the Nifty 500 dropped 1.85%.
The Nifty Microcap 250 tumbled 3.96%, highlighting the intensity of selling in smaller companies.
Among sectoral indices, the Nifty Metal index fell 3.23%, while the Nifty Consumer Durables index declined 3.20%. The Nifty Media index dropped 2.85%, followed by the Nifty Realty and Nifty Chemicals indices, which fell 2.78% each.
Banking stocks also remained under pressure, with the Nifty Bank declining 1.33% and the Nifty Financial Services index losing 1.20%. The Nifty Auto index fell 1.72%, while the Nifty PSU Bank index dropped 2.48%.
Information technology stocks bucked the broader market trend. The Nifty IT index gained 0.38% to 32,201.95, supported by TCS, which rose 2%, and Infosys, which gained 0.67%. HCL Technologies advanced 0.16%.
However, weakness in several heavyweight stocks, including Reliance Industries, ICICI Bank and Axis Bank, continued to weigh on the benchmarks.
India VIX Jumps Over 7%
India VIX, a gauge of expected market volatility, surged 7.56% to 16.96, signalling heightened uncertainty among traders and investors.
Asian Markets Today
Asian shares fell on Friday as concerns over the enormous funding needs of AI hammered tech and led to the biggest daily rally in Treasuries in more than three years, with investors fleeing to sovereign bonds and safe-haven currencies.
MSCI’s broadest index of Asia-Pacific shares excluding Japan fell 0.3% on Friday, bringing its weekly loss to 2.7% and marking a fourth straight week in the red. Japan’s Nikkei dropped 1.3% and was down a whopping 5% for the week.
South Korea’s KOSPI skidded 1.7%, on course for a 4.3% weekly decline, with memory chipmaker SK Hynix down 2.5% on the day. Taiwan’s stock market was closed due to a typhoon.
An index of mainland Chinese blue chips lost 1.1% on Friday to hit the lowest level since July 2025. The index was down about 20% from its peak in late June. Hong Kong’s Hang Seng edged up 0.1% after dropping 3% on Thursday.
V K Vijayakumar, chief investment strategist at Geojit Investments, said, “Brent crude spiking to $114 is a major negative for the economy and markets. However, there are strong positives that can counter this negative. The sharp decline in the US 10-year yield to 4.96 % and the appreciation in the rupee to 94.70 to the dollar are positives that can restrain FII selling significantly. More importantly, more than Rs 3 lakh of the IPO money ( out of the Rs3.73 that has gone into the Jio Platform IPO during the last two days) will come back into the system after the allotment is completed by next Monday. This potential liquidity surge can lift the market next week.”
He added that the market can move higher anticipating this in advance. It is important to understand that the rally, if it happens, will be led by the large-caps which are signalling resilience. The sharp correction in the broader market, particularly in small-caps, might continue since their valuations, driven up by liquidity rather than fundamentals, are hard to justify. Fairly-valued large-caps, particularly those which are growing well, present value buying opportunities for patient investors.