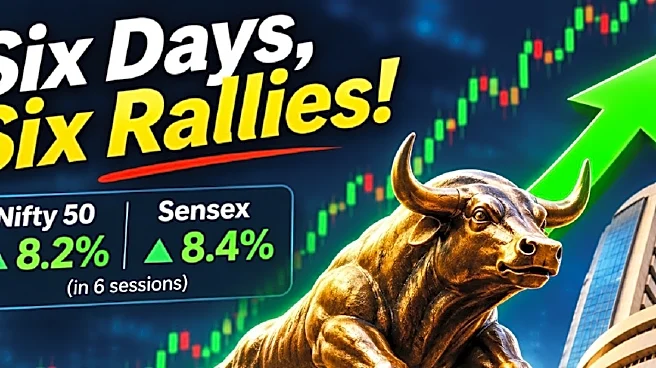
Stock Market Today, November 3: Rising for the fourth consecutive session, the domestic equity markets extended their recovery on Tuesday, November 3, with the Sensex surging over 1,200 points and the Nifty climbing to close above the 23,800 mark. A sharp decline in crude oil prices, renewed foreign investor buying, easing US bond yields, optimism over corporate earnings and expectations of an LTCG relief for foreign investors lifted investor sentiment.
The Sensex closed at 76,917.85, gaining 1,225.07 points, or 1.62%. The index opened at 76,288.65 and advanced to an intraday high of 76,917.85, while its low for the session stood at 76,033.74.
The Nifty settled at 23,810.85, rising 370.05 points, or 1.58%. It touched an intraday high of 23,810.85, compared
with an opening level of 23,582.25 and a low of 23,482.80.
The rally was broad-based, although gains were more pronounced in large-cap stocks than in the broader small-cap segment.
Key Factors Behind Sensex, Nifty Rally Today
The latest gains came after Monday’s strong rebound, when the Sensex had climbed 1,233 points and the Nifty advanced nearly 388 points. Several domestic and global factors supported the continuation of the recovery.
1. Sharp correction in crude oil prices
A significant decline in crude oil prices was among the biggest supports for Indian equities. Brent crude had fallen around 7% in the previous session amid hopes of diplomatic progress on the Iran-related geopolitical situation.
Lower crude prices are positive for India, a major oil importer, as they can ease pressure on the country’s import bill, inflation, corporate input costs and the rupee. A sustained moderation in oil prices could also provide the Reserve Bank of India with greater policy flexibility.
2. Foreign investors return to Indian equities
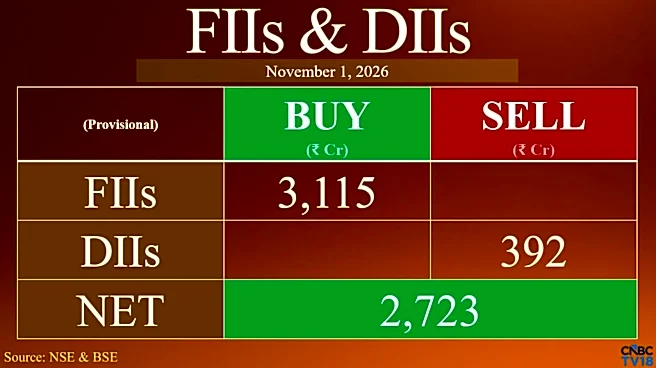
Foreign institutional investors (FIIs) turned net buyers in the previous session, providing a much-needed boost to domestic equities after a prolonged period of selling. FIIs bought Indian equities worth around Rs 3,115 crore on Monday, according to provisional exchange data. The return of foreign flows helped improve market liquidity and supported the broader recovery.
3. Easing US Treasury yields
A decline in US Treasury yields also supported investor sentiment. Softer bond yields can improve the relative attractiveness of equities, particularly in emerging markets such as India, by easing concerns over global financial conditions and capital outflows.
4. Resilient Q2 earnings boost confidence
Investors continued to track the September-quarter earnings season, with corporate results providing support to sentiment. Reliance Industries had led Monday’s rally after reporting its September-quarter results, with its shares surging sharply during the session. Expectations of resilient earnings across sectors have also helped investors look beyond recent concerns over crude prices and geopolitical uncertainty.
5. Broad-based buying in banking and consumption stocks
Buying was visible across several heavyweight sectors, particularly FMCG, private banks, financial services, realty and automobiles. Gains in large-cap stocks such as Hindustan Unilever, Bharti Airtel, HDFC Bank and ICICI Bank provided significant support to the benchmarks.
Vinod Nair, head of research at Geojit Investments Ltd, said the recovery was supported by a combination of easing macroeconomic pressures, foreign investor interest and resilient corporate earnings.
“Indian equities extended their recovery as a sharp decline in crude oil prices, declining U.S. Treasury yields and renewed FII interest eased recent macro pressures. Resilient Q2 earnings further strengthened confidence in the domestic growth outlook, while the return of foreign investors after prolonged selling provided a liquidity boost, driving broader participation led by financials and consumption-oriented sectors,” Nair said.
Looking ahead, he cautioned that the sustainability of the recovery would depend on earnings performance and global developments.
“Going forward, the durability of the recovery will hinge on broader earnings delivery, sustained FII inflows and continued moderation in oil prices and global yields, with geopolitical developments and the Fed’s policy trajectory remaining the key external triggers,” he added.
Sectoral Indices: FMCG, Realty And Financial Stocks Lead
Sectoral performance was largely positive on Tuesday, with FMCG stocks emerging as the biggest gainers. The Nifty FMCG index surged 3.65%, followed by the Nifty Realty index, which gained 2.33%. The Nifty Financial Services Ex-Bank index advanced 2.15%, while the Nifty Private Bank index rose 1.98%.
Other notable gainers included the Nifty Financial Services 25/50 (up 1.89%), Nifty Auto (up 1.71%), Nifty Chemicals (up 1.21%) and Nifty Pharma (up 0.42%).
However, the rally was not uniform. The Nifty PSU Bank index declined 1.27%, while the Nifty Metal index slipped 0.14%.
Among Sensex constituents, Hindustan Unilever emerged as the top performer, rising 4.16%. Bharti Airtel gained 4%, while HDFC Bank advanced 3.62%. Asian Paints climbed 3.53%, UltraTech Cement rose 3.05% and ICICI Bank gained 2.80%. ITC, Titan, Axis Bank and Maruti Suzuki were among the other notable gainers.
On the other hand, Power Grid Corporation was the biggest laggard, falling 2.27%. State Bank of India declined 1.77%, while NTPC lost 0.87% and Tata Steel fell 0.54%. Reliance Industries, which had led the previous session’s rally, was up 0.55%.
Broader Markets: Midcaps Outperform Smallcaps
Broader market indices also ended higher, although the gains were relatively modest in the small-cap space. The Nifty 100 advanced 1.47%, while the Nifty 200 and Nifty 500 gained 1.39% and 1.25%, respectively. The Nifty Midcap 100 rose 1.06%.
The India VIX, a measure of expected market volatility, rose 0.98% to 15.65, suggesting that some caution persisted despite the sharp gains in benchmark indices.