What is the story about?
Renu Baid Pugalia, Senior Vice President – Research at IIFL Institutional Equities, favours CG Power and Larsen & Toubro (L&T) amid strong order books, improving execution and rising demand for power equipment.
On CG Power she said, “Overall at the company level, we have upgraded our earning estimate by about 10% and 13% for FY28 and FY29.”
Pugalia expects strong demand for domestic grid equipment and improving export opportunities to support CG Power’s growth. Demand from data centres in developed markets is also emerging as an additional driver. “We have earnings upgrade, we retain a target price of ₹1,000, which is a combination of the SOTP value for the OSAT as well as the core business front, she added.
BHEL also reported better-than-expected results, prompting IIFL to raise its earnings estimates for the next two years by around 20% to 25%. However, softer order inflows remain a concern.
“We were expecting a strong performance from them. That was a very healthy beat from their side. In BHEL also, we have a upgraded our earnings estimate by almost 20-25% for the next 2 years,” Pugalia said.
She noted that BHEL is being selective about taking thermal power orders because of execution challenges. Order inflows could improve in the second half, with opportunities in railways and other segments supporting demand. Despite the absence of large thermal projects in its current-year pipeline, the company could end the year with broadly flat order inflows.
L&T is another preferred pick, with IIFL expecting execution in its core businesses to improve after a relatively soft first quarter. Core order inflows are expected to grow by more than 20%, providing support for activity in the coming quarters.
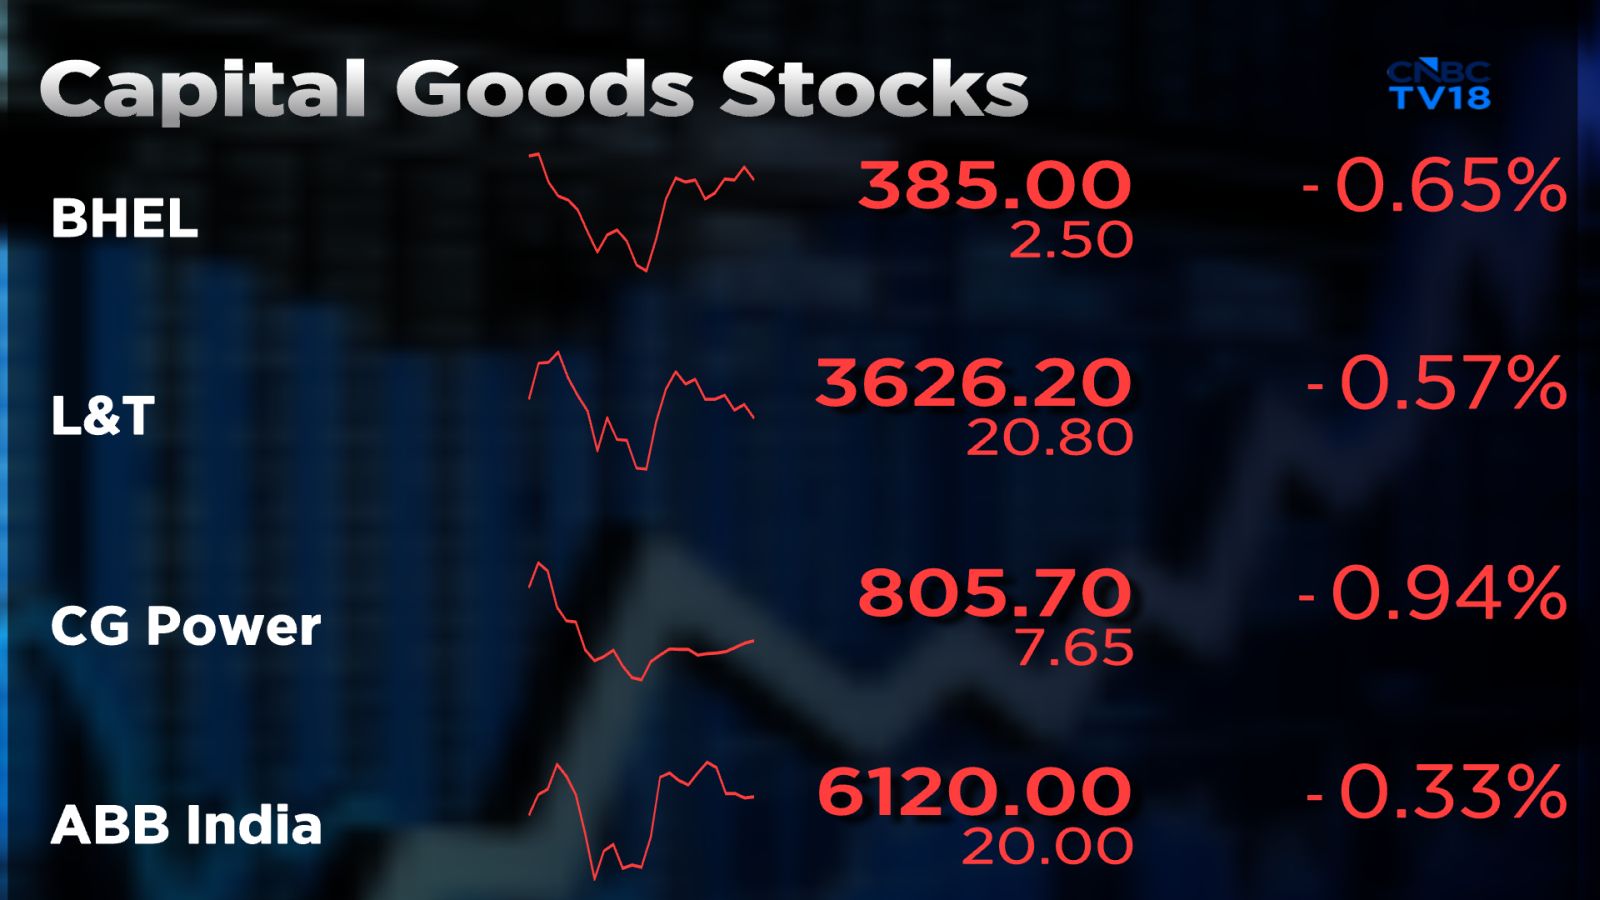
However, margin improvement may take longer, as the second quarter is seasonally softer and cost pressures continue. Pugalia expects a more meaningful recovery in margins in the second half of the financial year.
She considers L&T a relatively defensive largecap stock in the current uncertain market environment, particularly as investors look for companies with steady order books and execution visibility.
ABB India could also benefit from improving order inflows, industrial demand and data centre-led electrification. IIFL expects order inflows to grow 35% year on year, with the possibility of a better-than-expected performance.
The company's exposure to industrial motors and motion products could support revenue growth and margins, while sequential margin improvement may be approaching.
For the entire discussion, watch the accompanying video
Follow our live blog for more updates on Q2 results
On CG Power she said, “Overall at the company level, we have upgraded our earning estimate by about 10% and 13% for FY28 and FY29.”
Pugalia expects strong demand for domestic grid equipment and improving export opportunities to support CG Power’s growth. Demand from data centres in developed markets is also emerging as an additional driver. “We have earnings upgrade, we retain a target price of ₹1,000, which is a combination of the SOTP value for the OSAT as well as the core business front, she added.
BHEL also reported better-than-expected results, prompting IIFL to raise its earnings estimates for the next two years by around 20% to 25%. However, softer order inflows remain a concern.
“We were expecting a strong performance from them. That was a very healthy beat from their side. In BHEL also, we have a upgraded our earnings estimate by almost 20-25% for the next 2 years,” Pugalia said.
She noted that BHEL is being selective about taking thermal power orders because of execution challenges. Order inflows could improve in the second half, with opportunities in railways and other segments supporting demand. Despite the absence of large thermal projects in its current-year pipeline, the company could end the year with broadly flat order inflows.
L&T is another preferred pick, with IIFL expecting execution in its core businesses to improve after a relatively soft first quarter. Core order inflows are expected to grow by more than 20%, providing support for activity in the coming quarters.
However, margin improvement may take longer, as the second quarter is seasonally softer and cost pressures continue. Pugalia expects a more meaningful recovery in margins in the second half of the financial year.
She considers L&T a relatively defensive largecap stock in the current uncertain market environment, particularly as investors look for companies with steady order books and execution visibility.
ABB India could also benefit from improving order inflows, industrial demand and data centre-led electrification. IIFL expects order inflows to grow 35% year on year, with the possibility of a better-than-expected performance.
The company's exposure to industrial motors and motion products could support revenue growth and margins, while sequential margin improvement may be approaching.
For the entire discussion, watch the accompanying video
Follow our live blog for more updates on Q2 results