What is the story about?
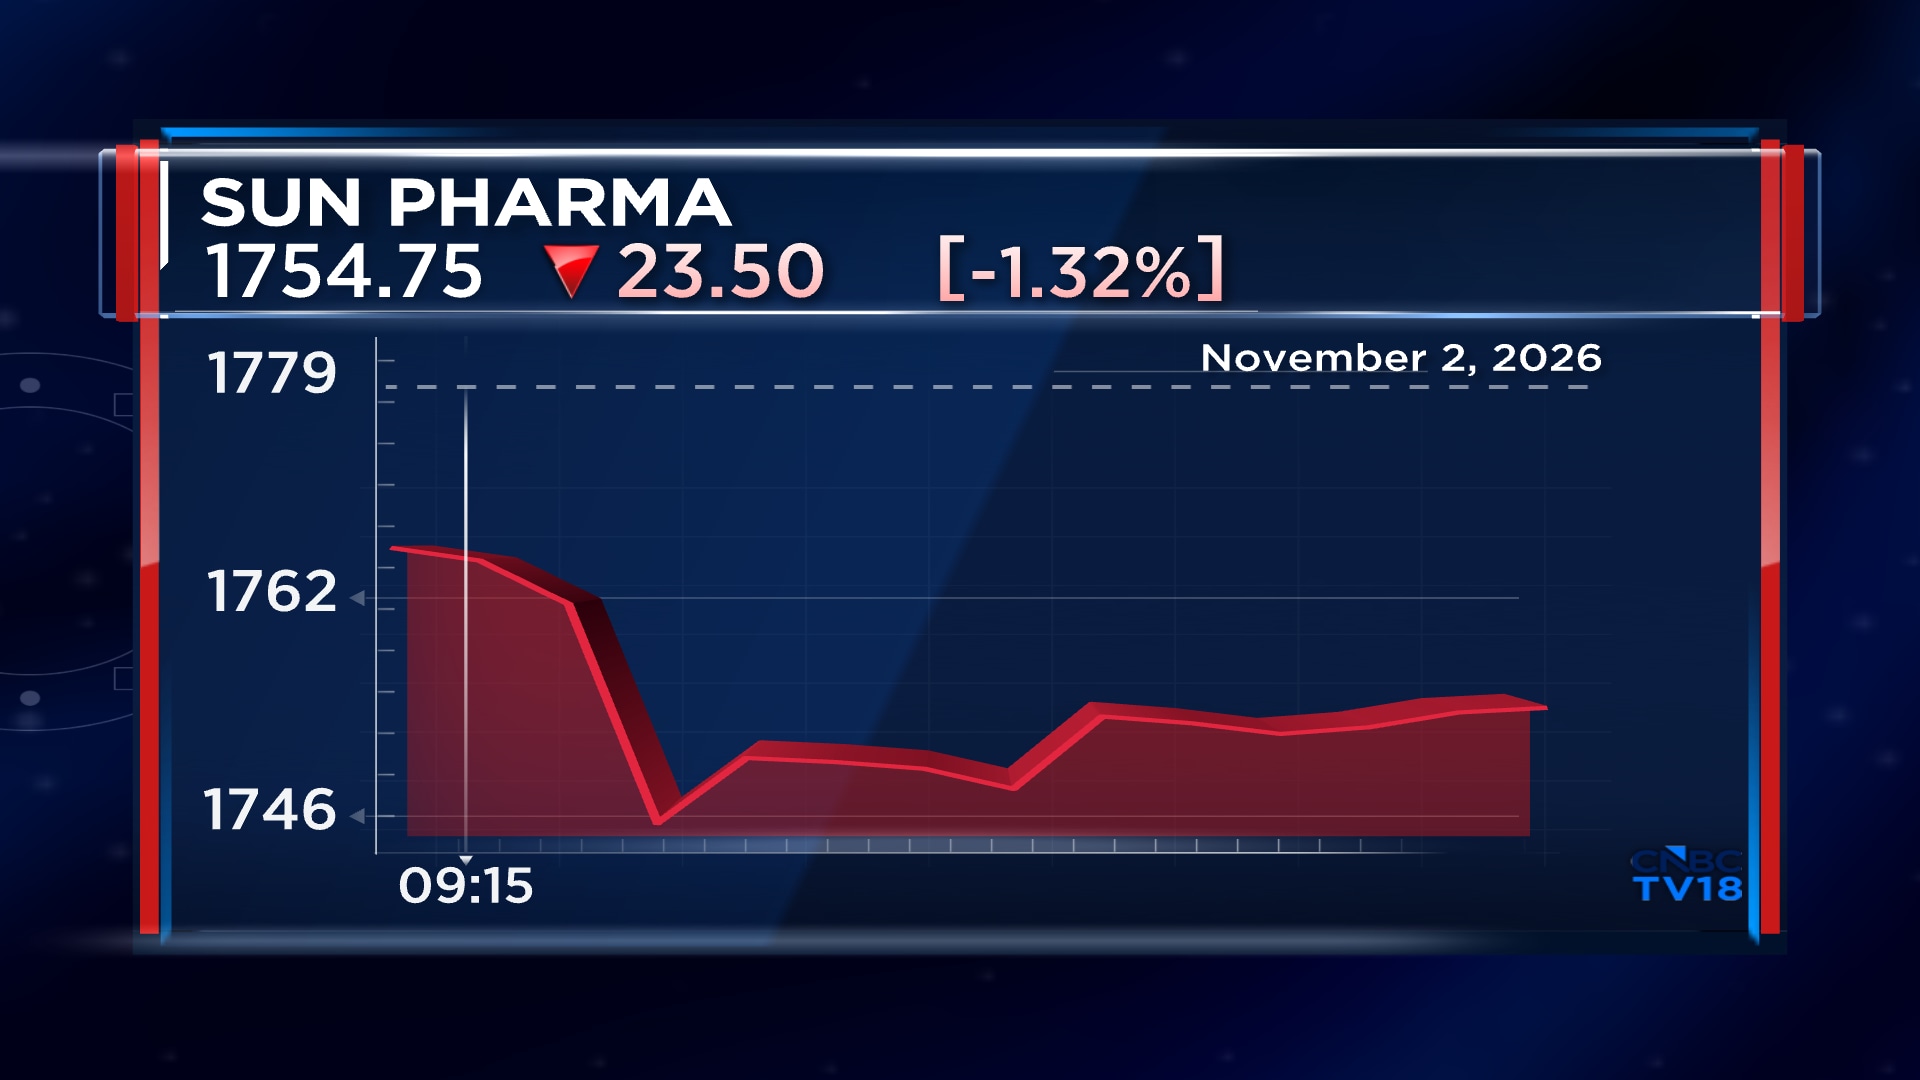
Shares of Sun Pharmaceuticals Industries declined on Monday, November 2, even as the company in its post-earnings conference call reiterated its high single-digit guidance for the ongoing financial year.
Sun Pharma's management said the company witnessed slowdown in the drug Illumya's sales in the second quarter. It made up 12% of sales in FY26.
The company has identified factors that led to the slowdown and will focus on execution to revive growth, the management said.
It added that Sun Pharma will soft launch Illumya for psoriatic arthritis in November.
The management said the firm has secured regulatory approvals for Organon acquisition in majority of the markets. It is on track to close the deal by the fourth quarter of this fiscal.
The management also reiterated its high single-digit guidance for FY27.
Q2 Results
Sun Pharma reported its second quarter results on Friday. Its net profit declined 32% to ₹1,988.5 crore from ₹3,118 crore last year. It was also below the CNBC-TV18 poll of ₹3,085 crore.
Its revenue came in at ₹16,198.7 crore, up 11.9% from the previous year's ₹14,478.31 crore and above estimates of ₹15,766.1 crore.
The company's earnings before interest, taxes, depreciation and amortization (EBITDA) increased 4.8% to ₹4,743.5 crore from ₹4,527.05 crore. It was also above estimates of ₹4,403 crore.
Its EBITDA margin contracted to 29.3% from 31.3% in the year-ago period but was above expectations of 27.9%.
Sun Pharma reported a one-time loss of ₹1,269 crore in the second quarter.
Its US sales were at $455 million, in-line with CNBC-TV18 poll's $455 million.
HSBC
It has a "buy" recommendation on the stock but has reduced its target price to ₹2,050 from ₹2,100. This indicates an upside of 15.3% from its previous closing price.
HSBC said the slowdown of Ilumya sales in the US led to slower 6.9% growth in global innovation medicine sales in the second quarter from last year. It said Sun Pharma is looking for better execution and expansion into psoriatic arthritis indication to recover Illumya sales in the US.
It added that recovery in Illumya US sales and EU launch of lerodalcibep are catalysts.
Nuvama
Nuvama has a retained its "buy" rating but has reduced its target price to ₹2,320 from ₹2,360. This indicates an upside of 30.5% from its previous close.
UBS
UBS has a "buy" rating and a target price of ₹2,200 per share. This indicates an upside of 23.8% from its previous closing price of ₹1,777.7 apiece.
It said the company reported a strong second quarter, revenue growth of 11.8%, driven by India formulations growth of 1.3%, emerging markets growth of 17.8% and rest of world growth of 12.9% from last year.
The overall US formulations sales, representing 27% of its revenue, declined 8.3% to %455 million, largely due to lenalidomide erosion, although sales increased 6.5% sequentially, aided by five generic launches, UBS said.
It added that India formulatons grew 17.3%, led by strong volume growth and new launches, with market share gain of 30 basis points to 8.6%. Its gross margin remained strong at 80.8%, supported by a favourable product mix and currency tailwinds, while its reported EBITDA margin came in at 29.3% compared to 31.3% in the first quarter, which included a higher contribution from lenalidomide.
Nomura
It has a "buy" rating and a target price of ₹2,260 per share, indicating an upside of 27% from its previous close.
It said the second quarter was a mixed bag, with India business roaring and specialty slowing. It expects specialty growth to recover and remains constructive on the Organon acquisition. It has valuation support from the branded generic segment.
It said Organon earnings was stable for the third quarter of the calendar year 2026 and the transaction is on track and is expected to close by the fourth quarter of FY27.
Goldman Sachs
It said the second quarter results were in-line with estimates as sales and EBITDA grew 12% and 5%, respectively, driven by robust growth in India and EM, partially offset by continued weakness in the US generics business.
It said the EBITDA margin of 29% was marginally lower than its estimates as higher operating costs offset gross margin surprise.
The management had guided for high single-digit consolidated topline growth for FY27 on its current understanding of regulatory and macro environment, and expects the FY27 research and development to pick up in the second half at 6-7% of sales.
JPMorgan
It said the company reported a healthy quarter.
It said in the US, Sun Pharma management expects Illumya to re-accelerate over the coming quarters, aided by the recently-approved PsA indication and targeted commercial interventions, while the rest of the innovative portfolio (Unloxcyt, Leqselv) continues to gain traction.
It added that the FY27 guidance of high single-digit revenue growth was maintained despite the first half tracking at 11%.
Stock reaction
Of the 40 analysts who have coverage on the Sun Pharma stock, 35 have "buy" ratings, one has a "hold" rating and four have "sell" recommendations.
Shares of Sun Pharmaceutical Industries were trading 1.6% lower at ₹1,749.8 apiece at 9.27 am on Monday. The stock has declined 3.8% in the last six months but is up 1.9% in 2026, so far.
Also Read:Shyam Metalics shares may react to higher volume growth, strong Q2 operating performance
Sun Pharma's management said the company witnessed slowdown in the drug Illumya's sales in the second quarter. It made up 12% of sales in FY26.
The company has identified factors that led to the slowdown and will focus on execution to revive growth, the management said.
It added that Sun Pharma will soft launch Illumya for psoriatic arthritis in November.
The management said the firm has secured regulatory approvals for Organon acquisition in majority of the markets. It is on track to close the deal by the fourth quarter of this fiscal.
The management also reiterated its high single-digit guidance for FY27.
Q2 Results
Sun Pharma reported its second quarter results on Friday. Its net profit declined 32% to ₹1,988.5 crore from ₹3,118 crore last year. It was also below the CNBC-TV18 poll of ₹3,085 crore.
Its revenue came in at ₹16,198.7 crore, up 11.9% from the previous year's ₹14,478.31 crore and above estimates of ₹15,766.1 crore.
The company's earnings before interest, taxes, depreciation and amortization (EBITDA) increased 4.8% to ₹4,743.5 crore from ₹4,527.05 crore. It was also above estimates of ₹4,403 crore.
Its EBITDA margin contracted to 29.3% from 31.3% in the year-ago period but was above expectations of 27.9%.
Sun Pharma reported a one-time loss of ₹1,269 crore in the second quarter.
Its US sales were at $455 million, in-line with CNBC-TV18 poll's $455 million.
HSBC
It has a "buy" recommendation on the stock but has reduced its target price to ₹2,050 from ₹2,100. This indicates an upside of 15.3% from its previous closing price.
HSBC said the slowdown of Ilumya sales in the US led to slower 6.9% growth in global innovation medicine sales in the second quarter from last year. It said Sun Pharma is looking for better execution and expansion into psoriatic arthritis indication to recover Illumya sales in the US.
It added that recovery in Illumya US sales and EU launch of lerodalcibep are catalysts.
Nuvama
Nuvama has a retained its "buy" rating but has reduced its target price to ₹2,320 from ₹2,360. This indicates an upside of 30.5% from its previous close.
UBS
UBS has a "buy" rating and a target price of ₹2,200 per share. This indicates an upside of 23.8% from its previous closing price of ₹1,777.7 apiece.
It said the company reported a strong second quarter, revenue growth of 11.8%, driven by India formulations growth of 1.3%, emerging markets growth of 17.8% and rest of world growth of 12.9% from last year.
The overall US formulations sales, representing 27% of its revenue, declined 8.3% to %455 million, largely due to lenalidomide erosion, although sales increased 6.5% sequentially, aided by five generic launches, UBS said.
It added that India formulatons grew 17.3%, led by strong volume growth and new launches, with market share gain of 30 basis points to 8.6%. Its gross margin remained strong at 80.8%, supported by a favourable product mix and currency tailwinds, while its reported EBITDA margin came in at 29.3% compared to 31.3% in the first quarter, which included a higher contribution from lenalidomide.
Nomura
It has a "buy" rating and a target price of ₹2,260 per share, indicating an upside of 27% from its previous close.
It said the second quarter was a mixed bag, with India business roaring and specialty slowing. It expects specialty growth to recover and remains constructive on the Organon acquisition. It has valuation support from the branded generic segment.
It said Organon earnings was stable for the third quarter of the calendar year 2026 and the transaction is on track and is expected to close by the fourth quarter of FY27.
Goldman Sachs
It said the second quarter results were in-line with estimates as sales and EBITDA grew 12% and 5%, respectively, driven by robust growth in India and EM, partially offset by continued weakness in the US generics business.
It said the EBITDA margin of 29% was marginally lower than its estimates as higher operating costs offset gross margin surprise.
The management had guided for high single-digit consolidated topline growth for FY27 on its current understanding of regulatory and macro environment, and expects the FY27 research and development to pick up in the second half at 6-7% of sales.
JPMorgan
It said the company reported a healthy quarter.
It said in the US, Sun Pharma management expects Illumya to re-accelerate over the coming quarters, aided by the recently-approved PsA indication and targeted commercial interventions, while the rest of the innovative portfolio (Unloxcyt, Leqselv) continues to gain traction.
It added that the FY27 guidance of high single-digit revenue growth was maintained despite the first half tracking at 11%.
Stock reaction
Of the 40 analysts who have coverage on the Sun Pharma stock, 35 have "buy" ratings, one has a "hold" rating and four have "sell" recommendations.
Shares of Sun Pharmaceutical Industries were trading 1.6% lower at ₹1,749.8 apiece at 9.27 am on Monday. The stock has declined 3.8% in the last six months but is up 1.9% in 2026, so far.
Also Read:Shyam Metalics shares may react to higher volume growth, strong Q2 operating performance