What is the story about?
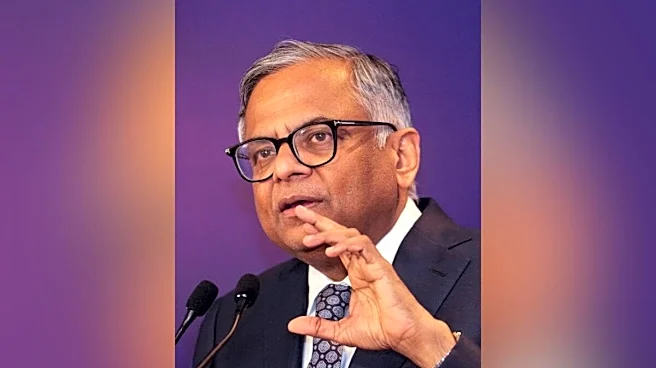
Tata Sons' decision to reappoint N. Chandrasekaran for another five-year term has triggered a legal dispute over the powers of Tata Trusts' nominee directors — and whether the chairman can use a casting vote when those nominees disagree.
At the September 17 Tata Sons board meeting, the resolution to reappoint Chandrasekaran was passed 4:1. But the two Tata Trust nominee directors did not vote together. Noel Tata voted against the resolution, while Venu Srinivasan voted in favour.
That split has brought the Articles of Association of Tata Sons into sharp focus. The Tata Trusts argue that the articles require an affirmative vote from the majority of their nominee directors for certain major decisions. The other side has raised the question of whether the chairman's casting vote can break a deadlock.
So, what exactly is the dispute about?
Speaking to CNBC-TV18, Independent Counsel Vyapak Desai, Advocate Sumesh Dhawan and Dr Thomas Mathew, biographer of Ratan Tata, former IAS officer, author and strategic affairs analyst, explained the different issues at play.
What is the affirmative vote issue?
The dispute centres on Articles 104, 118 and 121 of the Tata Sons Articles of Association.
The Tata Trusts' position is that these provisions require a majority of their nominee directors to give an affirmative vote on major decisions. With Noel Tata voting against Chandrasekaran's reappointment and Venu Srinivasan voting in favour, the Trusts argue that the required affirmative vote was not obtained.
That is why the Trusts have described the resolution as illegal, void ab initio and without basis.
The Trusts have also pointed to the Cyrus Mistry case, in which Tata Sons had defended the Articles of Association and the Supreme Court upheld their legality.
Dhawan said this history is important because the affirmative voting rights were part of the provisions that were upheld.
"These three articles, 104, 118, and 121, all are upheld by the Supreme Court," he said.
His argument is that it would be difficult to take a different position on the affirmative vote after the Supreme Court had upheld these provisions.
Where does the chairman's casting vote come in?
This is where the legal dispute becomes more complicated.
Article 121 also contains a provision relating to the chairman's casting vote. The question is whether that vote can be used to resolve a deadlock between the Tata Trust nominee directors, or whether it applies only when there is a tie at the overall board level.
Desai said there are two different levels of majority that need to be considered.
"Everybody knows for now that there are two levels of majority that we are now talking about," he said.
One is the majority among the Tata Trust nominee directors. The other is the majority at the overall Tata Sons board level.
Desai also pointed out that Article 121 provides for a casting vote by the chairman.
"My sense is that, look, definitely the chairman has a casting vote, there is no question about it," he said.
But the question, according to Desai, is whether that casting vote can override the requirement for an affirmative vote from the Trust nominees.
In simple terms, the dispute is not about whether the chairman has a casting vote. It is about whether that power can be used to overcome a split among the Tata Trust nominees when the Articles require an affirmative vote at that level.
Why does the Cyrus Mistry case matter?
The Cyrus Mistry case has become an important reference point because the same Articles of Association were part of the earlier dispute.
Dhawan said the Supreme Court had upheld affirmative voting rights for nominees of institutions holding a majority of shares.
He questioned why the interpretation of those provisions should now change.
Dhawan pointed out that Tata Sons had relied on the Articles of Association during the earlier battle involving Mistry. In his view, taking a different position now would effectively mean revisiting the interpretation of provisions that had already been upheld.
"I think there is something wrong here," Dhawan said.
The significance of the Mistry case, therefore, is not simply that it involved the Tata Group in an earlier governance dispute. It is that the validity of the relevant Articles was itself part of that legal battle.
Who does a Tata Trust nominee represent?
The split vote has also raised a separate question about the role of a nominee director.
Venu Srinivasan voted in favour of Chandrasekaran's reappointment despite the Tata Trusts' position. That has led to a broader question: when a person is appointed as a nominee of a shareholder, should the nominee follow the position of the shareholder, or exercise independent judgment as a director of the company?
Dr Thomas Mathew took the view that a Tata Trust representative is expected to follow the Trust's decision.
"Any representative of Tata Trust, according to me, is bound to vote in favour of the decision of the Chairman, Tata Trust," Mathew said.
He argued that the issue becomes particularly significant because Tata Trusts hold 66% of Tata Sons.
Mathew questioned how a majority shareholder could potentially be unable to determine who leads the company, despite holding such a large stake.
There is, however, another side to the issue. Harish Salve, advising Tata Sons, has argued that trust-nominated directors remain directors of Tata Sons and owe fiduciary duties to the company. He has also argued that there cannot be an indefinite deadlock and that the chairman must have the power to break a tie.
This brings two principles into conflict in the current debate: the rights attached to the Tata Trusts' shareholding and the responsibilities of directors serving on the Tata Sons board.
Could the issue reach the AGM?
The dispute may not necessarily end with the board's decision.
The possibility of the issue being tested at the AGM has also been raised. The two Tata Trusts — SDTT and SRTT — are required to nominate a joint representative to exercise their voting rights at the AGM.
The SRTT is currently facing an issue involving the Charities Commissioner, which means it may not be able to meet to appoint such a joint representative.
Dhawan said that could create another situation in which the Trusts, despite holding 66% of Tata Sons, could face difficulty exercising their voting rights.
"That's actually ironical, that the person who holds 66% ownership of the company will not be able to vote in that situation," he said.
Dhawan said legal experts would have to find a way to address the issue.
The AGM therefore presents another potential point of contention over how the Trusts can exercise their shareholder rights.
How does the dispute connect to the listing issue?
The governance battle is also unfolding against a separate dispute over whether Tata Sons should remain private or be listed.
In September 2022, the RBI classified Tata Sons as an upper-layer NBFC, making listing mandatory within three years. In March 2024, however, the Tata Sons board resolved to remain unlisted.
The Tata Trusts backed that position. In July 2025, SDTT and SRTT also resolved to keep Tata Sons unlisted.
The issue resurfaced after the RBI rejected Tata Sons' application for deregistration as a core investment company on September 11, 2026. The rejection effectively kept the regulatory pressure for listing alive.
Against that backdrop, Chandrasekaran's reappointment has become part of a much wider governance dispute involving the relationship between Tata Sons and Tata Trusts.
What changed after Ratan Tata?
Dr Thomas Mathew also questioned the change in the position on Tata Sons' listing.
Ratan Tata had previously described the relationship between the Tata Trusts and Tata Sons in terms of the Trusts being the moral compass and Tata Sons being the commercial engine.
Mathew said the change in stance on listing was difficult for him to explain because the circumstances had not, in his view, changed sufficiently to justify such a reversal.
"It is perplexing to me and is inexplicable to me at the same time because in two years there is nothing that's happened that there's been a drastic change in circumstances to warrant any such 180-degree turn," he said.
Mathew stressed that he was not taking sides in the legal dispute. His broader point was that the relationship between Tata Trusts and Tata Sons had changed significantly in a relatively short period.
What is the central legal question?
At its core, the dispute comes down to how different provisions of Tata Sons' Articles of Association are to be read together.
The Tata Trusts argue that their nominee directors' affirmative voting rights must be respected. Dhawan points to the Supreme Court's earlier treatment of those provisions as support for that position.
Tata Sons, through the argument advanced by Harish Salve, has focused on the role and duties of nominee directors and the need to prevent an indefinite deadlock.
Desai's analysis highlights the key question connecting the two positions: while Article 121 provides for a chairman's casting vote, can that vote resolve a deadlock where a separate affirmative vote of Tata Trust nominee directors is required?
That is the central issue behind the current governance dispute.
And beyond Chandrasekaran's reappointment, the interpretation of these provisions could have a bearing on the broader balance between Tata Trusts' shareholder rights and the functioning of the Tata Sons board.
At the September 17 Tata Sons board meeting, the resolution to reappoint Chandrasekaran was passed 4:1. But the two Tata Trust nominee directors did not vote together. Noel Tata voted against the resolution, while Venu Srinivasan voted in favour.
That split has brought the Articles of Association of Tata Sons into sharp focus. The Tata Trusts argue that the articles require an affirmative vote from the majority of their nominee directors for certain major decisions. The other side has raised the question of whether the chairman's casting vote can break a deadlock.
So, what exactly is the dispute about?
Speaking to CNBC-TV18, Independent Counsel Vyapak Desai, Advocate Sumesh Dhawan and Dr Thomas Mathew, biographer of Ratan Tata, former IAS officer, author and strategic affairs analyst, explained the different issues at play.
What is the affirmative vote issue?
The dispute centres on Articles 104, 118 and 121 of the Tata Sons Articles of Association.
The Tata Trusts' position is that these provisions require a majority of their nominee directors to give an affirmative vote on major decisions. With Noel Tata voting against Chandrasekaran's reappointment and Venu Srinivasan voting in favour, the Trusts argue that the required affirmative vote was not obtained.
That is why the Trusts have described the resolution as illegal, void ab initio and without basis.
The Trusts have also pointed to the Cyrus Mistry case, in which Tata Sons had defended the Articles of Association and the Supreme Court upheld their legality.
Dhawan said this history is important because the affirmative voting rights were part of the provisions that were upheld.
"These three articles, 104, 118, and 121, all are upheld by the Supreme Court," he said.
His argument is that it would be difficult to take a different position on the affirmative vote after the Supreme Court had upheld these provisions.
Where does the chairman's casting vote come in?
This is where the legal dispute becomes more complicated.
Article 121 also contains a provision relating to the chairman's casting vote. The question is whether that vote can be used to resolve a deadlock between the Tata Trust nominee directors, or whether it applies only when there is a tie at the overall board level.
Desai said there are two different levels of majority that need to be considered.
"Everybody knows for now that there are two levels of majority that we are now talking about," he said.
One is the majority among the Tata Trust nominee directors. The other is the majority at the overall Tata Sons board level.
Desai also pointed out that Article 121 provides for a casting vote by the chairman.
"My sense is that, look, definitely the chairman has a casting vote, there is no question about it," he said.
But the question, according to Desai, is whether that casting vote can override the requirement for an affirmative vote from the Trust nominees.
In simple terms, the dispute is not about whether the chairman has a casting vote. It is about whether that power can be used to overcome a split among the Tata Trust nominees when the Articles require an affirmative vote at that level.
Why does the Cyrus Mistry case matter?
The Cyrus Mistry case has become an important reference point because the same Articles of Association were part of the earlier dispute.
Dhawan said the Supreme Court had upheld affirmative voting rights for nominees of institutions holding a majority of shares.
He questioned why the interpretation of those provisions should now change.
Dhawan pointed out that Tata Sons had relied on the Articles of Association during the earlier battle involving Mistry. In his view, taking a different position now would effectively mean revisiting the interpretation of provisions that had already been upheld.
"I think there is something wrong here," Dhawan said.
The significance of the Mistry case, therefore, is not simply that it involved the Tata Group in an earlier governance dispute. It is that the validity of the relevant Articles was itself part of that legal battle.
Who does a Tata Trust nominee represent?
The split vote has also raised a separate question about the role of a nominee director.
Venu Srinivasan voted in favour of Chandrasekaran's reappointment despite the Tata Trusts' position. That has led to a broader question: when a person is appointed as a nominee of a shareholder, should the nominee follow the position of the shareholder, or exercise independent judgment as a director of the company?
Dr Thomas Mathew took the view that a Tata Trust representative is expected to follow the Trust's decision.
"Any representative of Tata Trust, according to me, is bound to vote in favour of the decision of the Chairman, Tata Trust," Mathew said.
He argued that the issue becomes particularly significant because Tata Trusts hold 66% of Tata Sons.
Mathew questioned how a majority shareholder could potentially be unable to determine who leads the company, despite holding such a large stake.
There is, however, another side to the issue. Harish Salve, advising Tata Sons, has argued that trust-nominated directors remain directors of Tata Sons and owe fiduciary duties to the company. He has also argued that there cannot be an indefinite deadlock and that the chairman must have the power to break a tie.
This brings two principles into conflict in the current debate: the rights attached to the Tata Trusts' shareholding and the responsibilities of directors serving on the Tata Sons board.
Could the issue reach the AGM?
The dispute may not necessarily end with the board's decision.
The possibility of the issue being tested at the AGM has also been raised. The two Tata Trusts — SDTT and SRTT — are required to nominate a joint representative to exercise their voting rights at the AGM.
The SRTT is currently facing an issue involving the Charities Commissioner, which means it may not be able to meet to appoint such a joint representative.
Dhawan said that could create another situation in which the Trusts, despite holding 66% of Tata Sons, could face difficulty exercising their voting rights.
"That's actually ironical, that the person who holds 66% ownership of the company will not be able to vote in that situation," he said.
Dhawan said legal experts would have to find a way to address the issue.
The AGM therefore presents another potential point of contention over how the Trusts can exercise their shareholder rights.
How does the dispute connect to the listing issue?
The governance battle is also unfolding against a separate dispute over whether Tata Sons should remain private or be listed.
In September 2022, the RBI classified Tata Sons as an upper-layer NBFC, making listing mandatory within three years. In March 2024, however, the Tata Sons board resolved to remain unlisted.
The Tata Trusts backed that position. In July 2025, SDTT and SRTT also resolved to keep Tata Sons unlisted.
The issue resurfaced after the RBI rejected Tata Sons' application for deregistration as a core investment company on September 11, 2026. The rejection effectively kept the regulatory pressure for listing alive.
Against that backdrop, Chandrasekaran's reappointment has become part of a much wider governance dispute involving the relationship between Tata Sons and Tata Trusts.
What changed after Ratan Tata?
Dr Thomas Mathew also questioned the change in the position on Tata Sons' listing.
Ratan Tata had previously described the relationship between the Tata Trusts and Tata Sons in terms of the Trusts being the moral compass and Tata Sons being the commercial engine.
Mathew said the change in stance on listing was difficult for him to explain because the circumstances had not, in his view, changed sufficiently to justify such a reversal.
"It is perplexing to me and is inexplicable to me at the same time because in two years there is nothing that's happened that there's been a drastic change in circumstances to warrant any such 180-degree turn," he said.
Mathew stressed that he was not taking sides in the legal dispute. His broader point was that the relationship between Tata Trusts and Tata Sons had changed significantly in a relatively short period.
What is the central legal question?
At its core, the dispute comes down to how different provisions of Tata Sons' Articles of Association are to be read together.
The Tata Trusts argue that their nominee directors' affirmative voting rights must be respected. Dhawan points to the Supreme Court's earlier treatment of those provisions as support for that position.
Tata Sons, through the argument advanced by Harish Salve, has focused on the role and duties of nominee directors and the need to prevent an indefinite deadlock.
Desai's analysis highlights the key question connecting the two positions: while Article 121 provides for a chairman's casting vote, can that vote resolve a deadlock where a separate affirmative vote of Tata Trust nominee directors is required?
That is the central issue behind the current governance dispute.
And beyond Chandrasekaran's reappointment, the interpretation of these provisions could have a bearing on the broader balance between Tata Trusts' shareholder rights and the functioning of the Tata Sons board.