What is the story about?
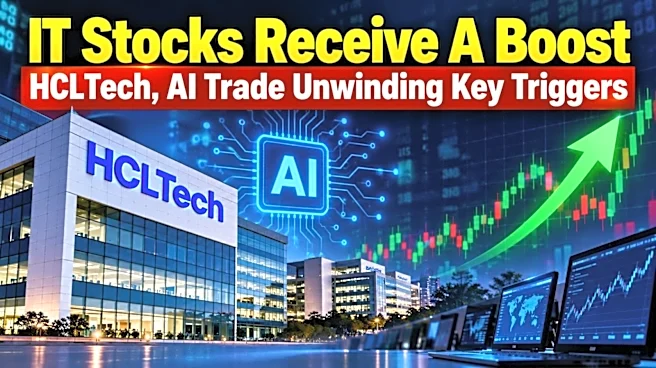
Shares of HCLTech Ltd. gained as much as 4% on Tuesday, October 13, in response to its September quarter results, which were a beat on the margins front, and also resulted in the company raising the lower end of its constant currency revenue growth guidance to 2.5% from 1% earlier.
HCLTech now expects revenue growth to be between 2.5% to 4% in financial year 2027 on a constant currency basis, compared to the earlier projection of 1% to 4%.
Brokerages such as Nomura, Citi, and DAM Capital have upgraded their Earnings Per Share estimates on the stock, while Jefferies has upgraded the stock to a "hold" recommendation.
Nomura has maintained its "buy" rating on HCLTech and has raised its price target to ₹1,330 from ₹1,310 earlier. The firm expects HCLTech's margins to normalize in financial year 2027 and 2028, citing steady progress on its five-pillar AI strategy.
As a result, Nomura has increased its EPS estimates for HCLTech by 2% to 3%.
Jefferies has upgraded HCLTech to "hold" from its earlier rating of "underperform", and raised its price target to ₹1,150 from ₹1,070 earlier.
HSBC too, has maintained its "hold" rating on HCLTech with a price target of ₹1,225. It called the company's outlook commentary positive as it noted improved demand in the past few weeks, although the firm highlighted that the sustainability of the same is a concern.
HCLTech is trading at a premium valuation multiple to peers for moderate outperformance and on lower margins as well, HSBC noted.
Citi has a "sell" recommendation on HCLTech with a price target of ₹1,050. The firm has also raised its financial year 2027-2029 EPS estimates by 1% to 3% following the margin beat.
However, Citi has said that the sustainability of margins will be key as HCLTech already trades at a premium of 20% to 25% to its peers like TCS and Infosys based on consensus estimates.
45 analysts have coverage on HCLTech, of which 18 have a "buy" rating, 16 say "hold", and 11 have a "sell" rating on the stock. The consensus estimates of price targets imply an upside potential of only 2.1% from current levels.
Shares of HCLTech are now trading 4.7% higher on Tuesday at ₹1,279.2. The stock is the top gainer on the Nifty IT index.
The results of HCLTech, coupled with the meltdown seen across the AI theme globally has given a leg up to Indian IT companies on Tuesday.
Apart from HCLTech, shares of TCS are also trading with gains of 4.5% and are among the top Nifty 50 gainers on Tuesday. Shares of Mphasis are up 3.5%, while those of LTM, Wipro, and Tech Mahindra are trading with gains of 2% to 2.5%
Shares of Infosys, Persistent Systems, Oracle Financial Services and Coforge are also trading with gains between 1% to 2%.
HCLTech now expects revenue growth to be between 2.5% to 4% in financial year 2027 on a constant currency basis, compared to the earlier projection of 1% to 4%.
Brokerages such as Nomura, Citi, and DAM Capital have upgraded their Earnings Per Share estimates on the stock, while Jefferies has upgraded the stock to a "hold" recommendation.
Nomura has maintained its "buy" rating on HCLTech and has raised its price target to ₹1,330 from ₹1,310 earlier. The firm expects HCLTech's margins to normalize in financial year 2027 and 2028, citing steady progress on its five-pillar AI strategy.
As a result, Nomura has increased its EPS estimates for HCLTech by 2% to 3%.
Jefferies has upgraded HCLTech to "hold" from its earlier rating of "underperform", and raised its price target to ₹1,150 from ₹1,070 earlier.
HSBC too, has maintained its "hold" rating on HCLTech with a price target of ₹1,225. It called the company's outlook commentary positive as it noted improved demand in the past few weeks, although the firm highlighted that the sustainability of the same is a concern.
HCLTech is trading at a premium valuation multiple to peers for moderate outperformance and on lower margins as well, HSBC noted.
Citi has a "sell" recommendation on HCLTech with a price target of ₹1,050. The firm has also raised its financial year 2027-2029 EPS estimates by 1% to 3% following the margin beat.
However, Citi has said that the sustainability of margins will be key as HCLTech already trades at a premium of 20% to 25% to its peers like TCS and Infosys based on consensus estimates.
45 analysts have coverage on HCLTech, of which 18 have a "buy" rating, 16 say "hold", and 11 have a "sell" rating on the stock. The consensus estimates of price targets imply an upside potential of only 2.1% from current levels.
Shares of HCLTech are now trading 4.7% higher on Tuesday at ₹1,279.2. The stock is the top gainer on the Nifty IT index.
Boost to IT Stocks
The results of HCLTech, coupled with the meltdown seen across the AI theme globally has given a leg up to Indian IT companies on Tuesday.
Apart from HCLTech, shares of TCS are also trading with gains of 4.5% and are among the top Nifty 50 gainers on Tuesday. Shares of Mphasis are up 3.5%, while those of LTM, Wipro, and Tech Mahindra are trading with gains of 2% to 2.5%
Shares of Infosys, Persistent Systems, Oracle Financial Services and Coforge are also trading with gains between 1% to 2%.