What is the story about?
Shares of Delhivery gained nearly 10% on Monday, November 2, as the company's strong operational improvement continued. Global investment banking firms are positive on the Delhivery stock and see up to 42% upside on it.
Delhivery reported a profit after tax (PAT) of ₹40.6 crore compared to a loss of ₹50.4 crore last year.
Its revenue increased 19.8% to ₹3,066.3 crore from ₹2,559.3 crore.
The company's earnings before interest, taxes, depreciation and amortization increased 200.1% to ₹204.7 crore from ₹68.2 crore last year.
Its margins expanded to 6.7% from 2.7% in the year-ago period.
The company's transport segment revenue increased 22% to ₹2,633 crore.
Its express parcel shipments were up 32%, PTL freight tonnage gained 14.2%.
Its net working capital days were at five compared to 17 last year. Its cash on books was at ₹4,676 crore.
Outlook
Jefferies
Jefferies has a "buy" rating but has cut its target price to ₹470 from its previous ₹540. This indicates an upside of 21.8% from its previous closing price.
The company's second quarter adjusted earnings before interest, taxes, depreciation and amortization (EBITDA) beat Jefferies estimates by 23%, with 70 basis points margin expansion on an annual basis, despite a deferred festive season.
Jefferies expects 30% stock underperformance compared to its peers since the June 2026 quarter to reverse as margin pressures ease.
It has raised its estimated FY27 earnings per share (EPS) by 21%, but cut its estimated FY28-29 EPS by 8-10%.
It said triangulating September quarter reported volumes of 3 PM players and Meesho and it estimates a marginal rise in Meesho's insourcing, which is a key monitorable.
Citi
Citi has a "buy" rating and a target price of ₹545 per share. This indicates an upside of 41.2% from its previous closing price.
It said that while its volumes were a tad soft, its yields rose sharply, driven by both inflation passthrough as well as mix-shift towards high yielding shipments and freight.
Delhivery also reiterated upper-end of 20-30% B2C volume growth guidance for FY27 and it expects 17% growth in the second half of FY27.
Overall, the company's service EBITDA and adjusted EBITDA were up 6% and 30%, respectively, compared to estimates on modestly higher transportation and significantly higher non-transportation margin, Citi said.
It added that Delhivery is focusing on higher margin, better yield business across verticals, likely at some cost of volumes.
Stock reaction
Of the 21 analysts who have coverage on the stock, 18 have a "buy" rating, one has a "hold" rating and two have "sell" recommendations.
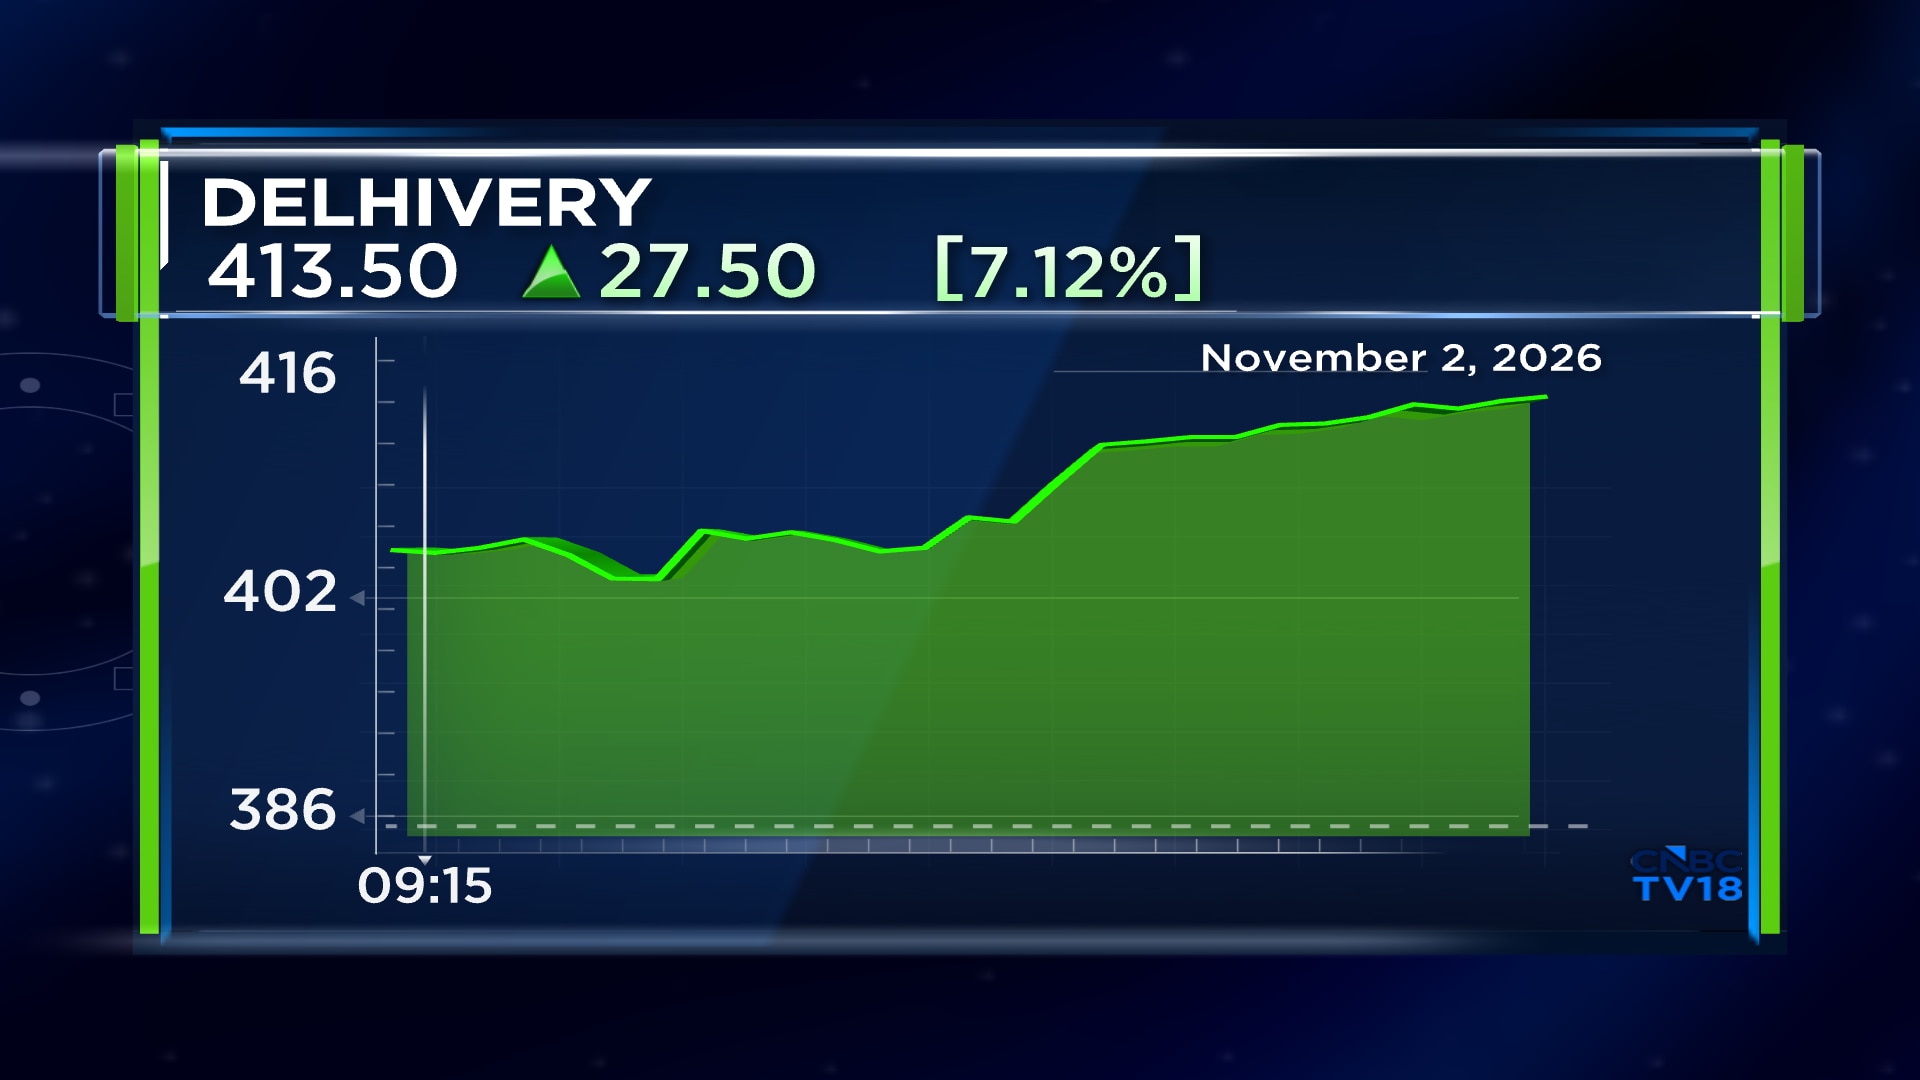
Shares of Delhivery gained 9.6% to hit an intraday high of ₹423 apiece on Monday. The stock was up 8.2% at ₹417.6 apiece at 10.30 am. It has gained 4.3% in the past month, is down 10.7% in the last six months but is up 4.2% this year, so far.
Also Read: Muthoot Finance shares rise 2.5% after Q2 results; management explains rise in loan delinquencies
Delhivery reported a profit after tax (PAT) of ₹40.6 crore compared to a loss of ₹50.4 crore last year.
Its revenue increased 19.8% to ₹3,066.3 crore from ₹2,559.3 crore.
The company's earnings before interest, taxes, depreciation and amortization increased 200.1% to ₹204.7 crore from ₹68.2 crore last year.
Its margins expanded to 6.7% from 2.7% in the year-ago period.
The company's transport segment revenue increased 22% to ₹2,633 crore.
Its express parcel shipments were up 32%, PTL freight tonnage gained 14.2%.
Its net working capital days were at five compared to 17 last year. Its cash on books was at ₹4,676 crore.
Outlook
- Delhivery expects its EBITDA margins to continue to expand through the third quarter.
- Express will end FY27 in the 16-18% service EBITDA margin range.
- The PTL service EBITDA margins should expand to 15% by FY27 exit.
Jefferies
Jefferies has a "buy" rating but has cut its target price to ₹470 from its previous ₹540. This indicates an upside of 21.8% from its previous closing price.
The company's second quarter adjusted earnings before interest, taxes, depreciation and amortization (EBITDA) beat Jefferies estimates by 23%, with 70 basis points margin expansion on an annual basis, despite a deferred festive season.
Jefferies expects 30% stock underperformance compared to its peers since the June 2026 quarter to reverse as margin pressures ease.
It has raised its estimated FY27 earnings per share (EPS) by 21%, but cut its estimated FY28-29 EPS by 8-10%.
It said triangulating September quarter reported volumes of 3 PM players and Meesho and it estimates a marginal rise in Meesho's insourcing, which is a key monitorable.
Citi
Citi has a "buy" rating and a target price of ₹545 per share. This indicates an upside of 41.2% from its previous closing price.
It said that while its volumes were a tad soft, its yields rose sharply, driven by both inflation passthrough as well as mix-shift towards high yielding shipments and freight.
Delhivery also reiterated upper-end of 20-30% B2C volume growth guidance for FY27 and it expects 17% growth in the second half of FY27.
Overall, the company's service EBITDA and adjusted EBITDA were up 6% and 30%, respectively, compared to estimates on modestly higher transportation and significantly higher non-transportation margin, Citi said.
It added that Delhivery is focusing on higher margin, better yield business across verticals, likely at some cost of volumes.
Stock reaction
Of the 21 analysts who have coverage on the stock, 18 have a "buy" rating, one has a "hold" rating and two have "sell" recommendations.
Shares of Delhivery gained 9.6% to hit an intraday high of ₹423 apiece on Monday. The stock was up 8.2% at ₹417.6 apiece at 10.30 am. It has gained 4.3% in the past month, is down 10.7% in the last six months but is up 4.2% this year, so far.
Also Read: Muthoot Finance shares rise 2.5% after Q2 results; management explains rise in loan delinquencies