What is the story about?
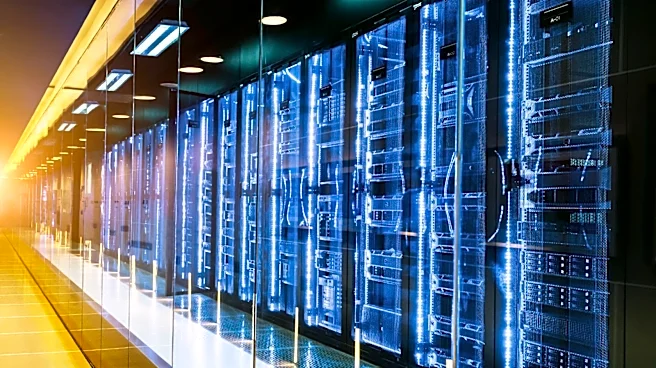
India's data centre industry is poised for an unprecedented investment boom, with installed capacity expected to increase five-fold to around 7.5 gigawatts (GW) by March 2030. The expansion is expected to attract investments of more than ₹3 lakh crore over the next four financial years, according to a report by Crisil Ratings on Tuesday, November 3.
The growth, driven by generative artificial intelligence (GenAI), enterprise digitalisation and rising data consumption, is set to transform India's digital infrastructure landscape.
However, the industry's ability to convert rising demand into sustainable returns will depend on timely power connectivity, regulatory approvals and disciplined project execution.
"Nearly half of the upcoming capacity is already committed under long-term contracts, limiting speculative development and reducing offtake risk," Crisil Ratings said. "Upfront tie-ups with hyperscalers, driven by cloud adoption and compute-intensive GenAI workloads, provide revenue certainty from the outset. This helps de-risk projects, even as the scale and speed of the planned build-out intensify execution requirements."
Strong demand from global hyperscalers, supported by cloud adoption and increasingly compute-intensive GenAI workloads, is also encouraging investments and reducing offtake uncertainty.
India's cost advantage strengthens data centre appeal
India's competitive cost structure is adding to its appeal as a data centre destination. Development costs are around 20% lower than in several competing Asia-Pacific markets, supported by relatively competitive land, construction and labour costs.
Combined with lower power tariffs, this allows rental rates to remain 30-35% below those in peer markets. The availability of large campuses powered by renewable energy also strengthens India's appeal among hyperscalers seeking to meet their sustainability commitments.
Anand Kulkarni, Director at Crisil Ratings, said, "India's structural cost advantages further strengthen its attractiveness as a data centre destination. Development costs are around one-fifth lower than in several competing Asia-Pacific markets owing to more competitive land, construction and labour costs. Combined with lower power tariffs, this translates into rentals that are 30-35% lower than in peer markets. The ability to develop large, renewable-powered campuses also aligns well with the sustainability goals of hyperscalers, reinforcing India's competitive positioning."
Power infrastructure poses execution challenges
However, the scale of the planned expansion is putting considerable pressure on power infrastructure. Nearly three-fourths of the approximately 6 GW of upcoming capacity is expected to be concentrated in Visakhapatnam, Mumbai and Hyderabad, Crisil Ratings said.
Data centre capacity in these cities could be equivalent to around 80%, 60% and 20%, respectively, of their current peak electricity demand. This concentration makes timely grid connectivity and transmission capacity expansion critical to avoiding commissioning delays and cost overruns.
Demand visibility and advance commitments offer some protection against these execution challenges. Existing data centre facilities in India are operating at around 90% utilisation, while more than 95% of the capacity currently under construction has already been contracted.
These high pre-commitment levels should help developers ramp up operations and generate cash flows relatively quickly once projects are commissioned.
Longer contracts improve revenue visibility
The quality of these contracts has also improved, with longer commitments providing greater revenue predictability.
Nitin Bansal, Associate Director at Crisil Ratings, said, "The quality of contracted revenues has also strengthened. Contract tenors have lengthened to 15-20 years from 10-12 years earlier, enhancing cash flow visibility. Furthermore, high migration costs and rising replacement capex should support customer retention, although a meaningful contract renewal track record is yet to be established."
He added that developers would need to ensure existing facilities remain relevant for next-generation GenAI workloads through timely upgrades to support higher power density and advanced cooling infrastructure.
Hyperscaler concentration could pressure rental rates
However, growing reliance on hyperscalers brings its own set of risks. Their share of leased data centre capacity is expected to increase to 75-80% by fiscal 2030 from 60-65% in fiscal 2026, exposing developers to greater customer concentration and bargaining-power risks.
While rental rates have remained broadly stable so far, accelerated capacity additions could strengthen hyperscalers' negotiating position and put pressure on pricing, potentially affecting project returns.
High capital expenditure to test credit profiles
The sector's credit profile will also be tested by the substantial upfront capital expenditure required to build facilities before revenue generation begins.
Investments typically precede cash flows by 24-36 months, keeping debt levels elevated over the medium term. However, as projects are commissioned, contracted capacity becomes operational and utilisation improves, cash generation should strengthen, supporting a gradual reduction in leverage.
The investment cycle presents both a significant growth opportunity and a substantial execution challenge. Long-term contracts, high utilisation and India's cost advantages provide a strong foundation for expansion and credit stability.
However, developers' ability to secure power, obtain regulatory approvals, commission projects on schedule and contain costs will determine whether they can convert the demand boom into sustainable financial performance. The durability of GenAI-led demand and the industry's ability to accommodate rapidly evolving computing requirements will also shape returns over the longer term.
The growth, driven by generative artificial intelligence (GenAI), enterprise digitalisation and rising data consumption, is set to transform India's digital infrastructure landscape.
However, the industry's ability to convert rising demand into sustainable returns will depend on timely power connectivity, regulatory approvals and disciplined project execution.
"Nearly half of the upcoming capacity is already committed under long-term contracts, limiting speculative development and reducing offtake risk," Crisil Ratings said. "Upfront tie-ups with hyperscalers, driven by cloud adoption and compute-intensive GenAI workloads, provide revenue certainty from the outset. This helps de-risk projects, even as the scale and speed of the planned build-out intensify execution requirements."
Strong demand from global hyperscalers, supported by cloud adoption and increasingly compute-intensive GenAI workloads, is also encouraging investments and reducing offtake uncertainty.
India's cost advantage strengthens data centre appeal
India's competitive cost structure is adding to its appeal as a data centre destination. Development costs are around 20% lower than in several competing Asia-Pacific markets, supported by relatively competitive land, construction and labour costs.
Combined with lower power tariffs, this allows rental rates to remain 30-35% below those in peer markets. The availability of large campuses powered by renewable energy also strengthens India's appeal among hyperscalers seeking to meet their sustainability commitments.
Anand Kulkarni, Director at Crisil Ratings, said, "India's structural cost advantages further strengthen its attractiveness as a data centre destination. Development costs are around one-fifth lower than in several competing Asia-Pacific markets owing to more competitive land, construction and labour costs. Combined with lower power tariffs, this translates into rentals that are 30-35% lower than in peer markets. The ability to develop large, renewable-powered campuses also aligns well with the sustainability goals of hyperscalers, reinforcing India's competitive positioning."
Power infrastructure poses execution challenges
However, the scale of the planned expansion is putting considerable pressure on power infrastructure. Nearly three-fourths of the approximately 6 GW of upcoming capacity is expected to be concentrated in Visakhapatnam, Mumbai and Hyderabad, Crisil Ratings said.
Data centre capacity in these cities could be equivalent to around 80%, 60% and 20%, respectively, of their current peak electricity demand. This concentration makes timely grid connectivity and transmission capacity expansion critical to avoiding commissioning delays and cost overruns.
Demand visibility and advance commitments offer some protection against these execution challenges. Existing data centre facilities in India are operating at around 90% utilisation, while more than 95% of the capacity currently under construction has already been contracted.
These high pre-commitment levels should help developers ramp up operations and generate cash flows relatively quickly once projects are commissioned.
Longer contracts improve revenue visibility
The quality of these contracts has also improved, with longer commitments providing greater revenue predictability.
Nitin Bansal, Associate Director at Crisil Ratings, said, "The quality of contracted revenues has also strengthened. Contract tenors have lengthened to 15-20 years from 10-12 years earlier, enhancing cash flow visibility. Furthermore, high migration costs and rising replacement capex should support customer retention, although a meaningful contract renewal track record is yet to be established."
He added that developers would need to ensure existing facilities remain relevant for next-generation GenAI workloads through timely upgrades to support higher power density and advanced cooling infrastructure.
Hyperscaler concentration could pressure rental rates
However, growing reliance on hyperscalers brings its own set of risks. Their share of leased data centre capacity is expected to increase to 75-80% by fiscal 2030 from 60-65% in fiscal 2026, exposing developers to greater customer concentration and bargaining-power risks.
While rental rates have remained broadly stable so far, accelerated capacity additions could strengthen hyperscalers' negotiating position and put pressure on pricing, potentially affecting project returns.
High capital expenditure to test credit profiles
The sector's credit profile will also be tested by the substantial upfront capital expenditure required to build facilities before revenue generation begins.
Investments typically precede cash flows by 24-36 months, keeping debt levels elevated over the medium term. However, as projects are commissioned, contracted capacity becomes operational and utilisation improves, cash generation should strengthen, supporting a gradual reduction in leverage.
The investment cycle presents both a significant growth opportunity and a substantial execution challenge. Long-term contracts, high utilisation and India's cost advantages provide a strong foundation for expansion and credit stability.
However, developers' ability to secure power, obtain regulatory approvals, commission projects on schedule and contain costs will determine whether they can convert the demand boom into sustainable financial performance. The durability of GenAI-led demand and the industry's ability to accommodate rapidly evolving computing requirements will also shape returns over the longer term.