What is the story about?
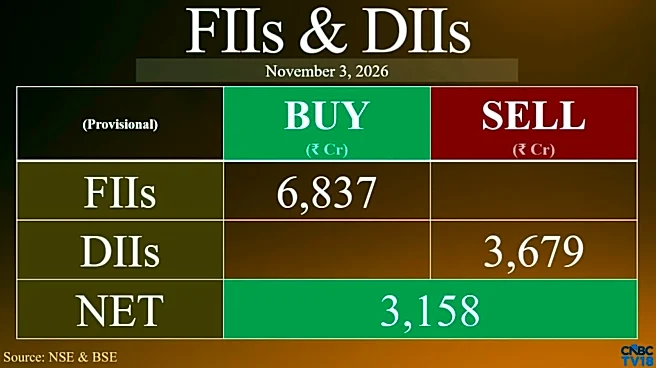
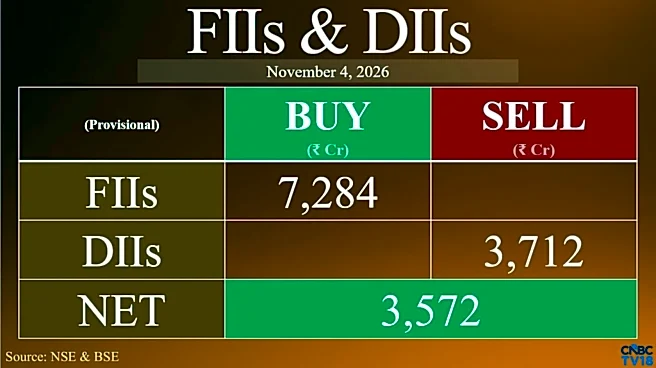
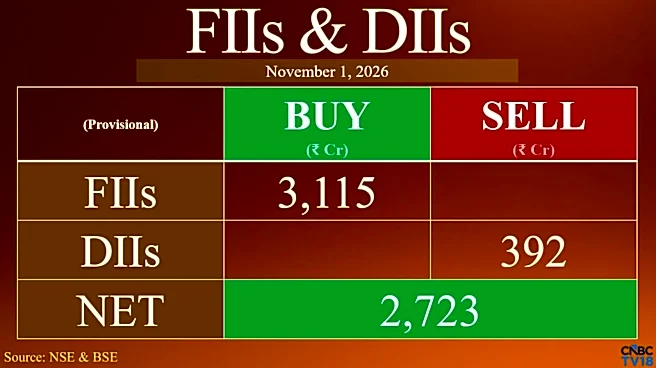
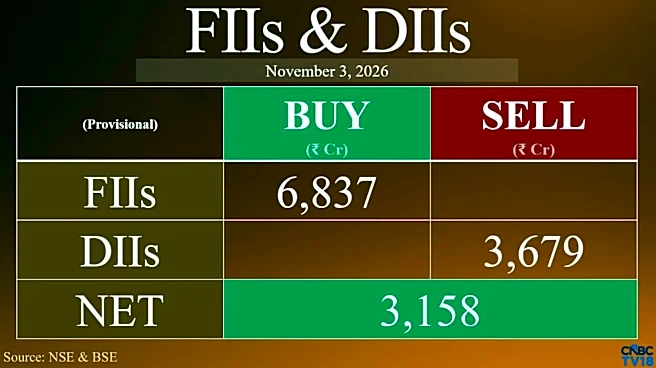
Foreign institutional investor (FII) money could favour private sector banks, industrials and capital goods if the flows return to India, according to Manishi Raychaudhuri, Chief Executive Officer at Emmer Capital Partners.
He expects the domestic market to mirror a trend already visible in China, where capital is rotating out of traditional semiconductor winners and into battered consumer technology stocks.
Chinese consumer tech giants such as Alibaba, Tencent and NetEase have recently jumped between 4% and 8%, while chipmakers including Samsung, Taiwan Semiconductor Manufacturing Company (TSMC) and MediaTek sold off sharply, dragging down the Kospi and Nikkei indices. A similar reversal is likely in India, where the hardest-hit sectors could emerge as the new leaders provided they are backed by fundamental rationales.
Financials suffered the most during the recent market correction, making them a prime candidate for returning inflows. Private sector lenders are positioned to gain market share and boast superior asset quality compared to their public sector peers. Furthermore, the rising interest rate environment serves as a tailwind for net interest margins.
"Bank loan growth has gone up to about 18 to 20%. That's a very serious upturn over the last one to one and a half years," Raychaudhuri noted. Wealth management companies also stand out within the broader financial space.
Beyond financials, industrials and capital goods represent the next major opportunity. The ongoing capital expenditure cycle remains largely driven by the government, but broader revenue and margin growth across the market is expected to spark a private CapEx revival. Together, banks, industrials and capital goods account for roughly 40-45% of the Indian market, making them the most substantial bets for incoming foreign capital.
Large frontline stocks are also expected to capture institutional attention. Reliance Industries, which advanced 13% over the week despite longer-term stagnation, remains a complex proposition due to its multiple business verticals.
"Reliance is a slightly more complicated story because it has so many moving parts now," Raychaudhuri explained. The conglomerate straddles pure exploration, refining, petrochemicals and the recently listed Jio Platforms. While pure explorers like Oil and Natural Gas Corporation (ONGC) and Oil India operate on one end of the spectrum, refining and marketing companies benefit from declining global crude prices. Despite the moving parts, frontline heavyweights are well-positioned to gain as foreign money gradually returns.
Watch the full conversation here
Conversely, the outlook for Indian information technology (IT) services remains clouded by the disruptive potential of artificial intelligence. In China, companies that were previously hammered—including SaaS providers and internet platforms like Trip.com and NetEase—jumped sharply after concerns emerged that AI spending would be leashed. However, domestic IT firms have declined on fears that their work will be automated by AI coding tools such as Claude. Although capital expenditure on mega data centers may slow due to regulatory pressures, the core value proposition of AI remains intact.
The threat to Indian IT margins cannot be dismissed. Consequently, reallocating major resources into the sector remains a skeptical proposition until these companies rediscover themselves and enter new business lines attuned to the evolving technological landscape.
Disclosure: Reliance Industries Ltd, which owns Jio, is the sole beneficiary of Independent Media Trust that controls Network18, the parent company of CNBCTV18.com.
Catch all the latest updates from the stock market here
He expects the domestic market to mirror a trend already visible in China, where capital is rotating out of traditional semiconductor winners and into battered consumer technology stocks.
Chinese consumer tech giants such as Alibaba, Tencent and NetEase have recently jumped between 4% and 8%, while chipmakers including Samsung, Taiwan Semiconductor Manufacturing Company (TSMC) and MediaTek sold off sharply, dragging down the Kospi and Nikkei indices. A similar reversal is likely in India, where the hardest-hit sectors could emerge as the new leaders provided they are backed by fundamental rationales.
Financials suffered the most during the recent market correction, making them a prime candidate for returning inflows. Private sector lenders are positioned to gain market share and boast superior asset quality compared to their public sector peers. Furthermore, the rising interest rate environment serves as a tailwind for net interest margins.
"Bank loan growth has gone up to about 18 to 20%. That's a very serious upturn over the last one to one and a half years," Raychaudhuri noted. Wealth management companies also stand out within the broader financial space.
Beyond financials, industrials and capital goods represent the next major opportunity. The ongoing capital expenditure cycle remains largely driven by the government, but broader revenue and margin growth across the market is expected to spark a private CapEx revival. Together, banks, industrials and capital goods account for roughly 40-45% of the Indian market, making them the most substantial bets for incoming foreign capital.
Large frontline stocks are also expected to capture institutional attention. Reliance Industries, which advanced 13% over the week despite longer-term stagnation, remains a complex proposition due to its multiple business verticals.
"Reliance is a slightly more complicated story because it has so many moving parts now," Raychaudhuri explained. The conglomerate straddles pure exploration, refining, petrochemicals and the recently listed Jio Platforms. While pure explorers like Oil and Natural Gas Corporation (ONGC) and Oil India operate on one end of the spectrum, refining and marketing companies benefit from declining global crude prices. Despite the moving parts, frontline heavyweights are well-positioned to gain as foreign money gradually returns.
Watch the full conversation here
Conversely, the outlook for Indian information technology (IT) services remains clouded by the disruptive potential of artificial intelligence. In China, companies that were previously hammered—including SaaS providers and internet platforms like Trip.com and NetEase—jumped sharply after concerns emerged that AI spending would be leashed. However, domestic IT firms have declined on fears that their work will be automated by AI coding tools such as Claude. Although capital expenditure on mega data centers may slow due to regulatory pressures, the core value proposition of AI remains intact.
The threat to Indian IT margins cannot be dismissed. Consequently, reallocating major resources into the sector remains a skeptical proposition until these companies rediscover themselves and enter new business lines attuned to the evolving technological landscape.
Disclosure: Reliance Industries Ltd, which owns Jio, is the sole beneficiary of Independent Media Trust that controls Network18, the parent company of CNBCTV18.com.
Catch all the latest updates from the stock market here