What is the story about?
Shares of Mankind Pharma Ltd. rose more than 8% intraday on Tuesday, October 27, after the company reported a 39.2% year-on-year rise in September-quarter net profit to ₹712 crore, while revenue grew 17.3% to ₹4,338 crore and EBITDA margin expanded to 27%.
This is the biggest single-day gain for the stock in nearly two years.
Despite the earnings beat, global investment firms remain cautious, with three of the four firms maintaining negative or cautious ratings and target prices implying downside of 5.5% to 36% from Monday's close of ₹3,212. Concerns centre on the muted over-the-counter (OTC) business growth and the stock's valuation.
Mankind Pharma's domestic business grew by 15.9% during the quarter, with volume growth at 1.2 times that of the Indian Pharmaceutical Market (IPM). Its chronic portfolio grew 1.1 times faster than the market, led by 19% growth in cardiac and 16% in anti-diabetes.
The acute portfolio also outperformed the market by 1.1 times, supported by 19% growth in gastro and 26% in the VMN segment. Bharat Serums and Vaccines' domestic specialty business recorded steady double-digit growth, while the international business grew 33%. The over-the-counter (OTC) business, however, reported muted growth.
Kotak Institutional Equities: Buy | Target price: ₹3,035
Kotak Institutional Equities maintained a Buy rating on Mankind Pharma with a target price of ₹3,035. Based on Monday's closing price of ₹3,212, the target implies a downside of 5.5%.
Kotak expects Mankind Pharma's Earnings per share (EPS) to report a Compounded Annual Growth Rate (CAGR) of 23% over financial year 2026-2029. It identified the over-the-counter (OTC) business as a key concern, with growth yet to pick up.
JPMorgan: Neutral | Target price: ₹2,700
JPMorgan retained a "Neutral" rating and a target price of ₹2,700, implying a 15.9% downside from Monday's close.
The firm said second-quarter revenue beat estimates by 3%, led by the India prescription (Rx) business and exports. Earnings before interest, tax, depreciation and amortisation (EBITDA) margin came in at 27%, around 100 basis points above estimates.
However, the company's FY27 EBITDA margin guidance remains at 25.5%-26.5%. JPMorgan also noted that consumer business growth guidance had been reduced to single digits, with double-digit growth expected from the next financial year.
Macquarie: Underperform | Target price: ₹2,200
Macquarie maintained an Underperform rating and a target price of ₹2,200, implying a 31.5% downside from Monday's close.
The global investment firm said revenue, EBITDA and adjusted profit after tax (PAT) for the September quarter exceeded its estimates by 3%, 4% and 12%, respectively.
Bernstein: Underperform | Target price: ₹2,057
Bernstein maintained an Underperform rating with a target price of ₹2,057, implying a downside of 36% from Monday's closing price.
It said domestic growth of 15.9% was healthy, but the recovery remained uneven. It sees limited incremental evidence to justify Mankind Pharma's premium valuation.
Of the 22 analysts covering the stock, 15 have given it a "Buy" recommendation, three have a "Hold" rating, and the stock has four "Sell" ratings.
Investec has a Buy rating with a target price of ₹3,040, followed by Kotak Securities at ₹3,035. HDFC Research has a target price of ₹3,280, while Ambit Capital's target stands at ₹2,635. Morgan Stanley has an Equal-weight/Attractive recommendation with a target price of ₹2,595.
The 12-month consensus target price stands at ₹2,704, against the last price of ₹2,495.10, indicating a potential return of more than 8% from current levels..
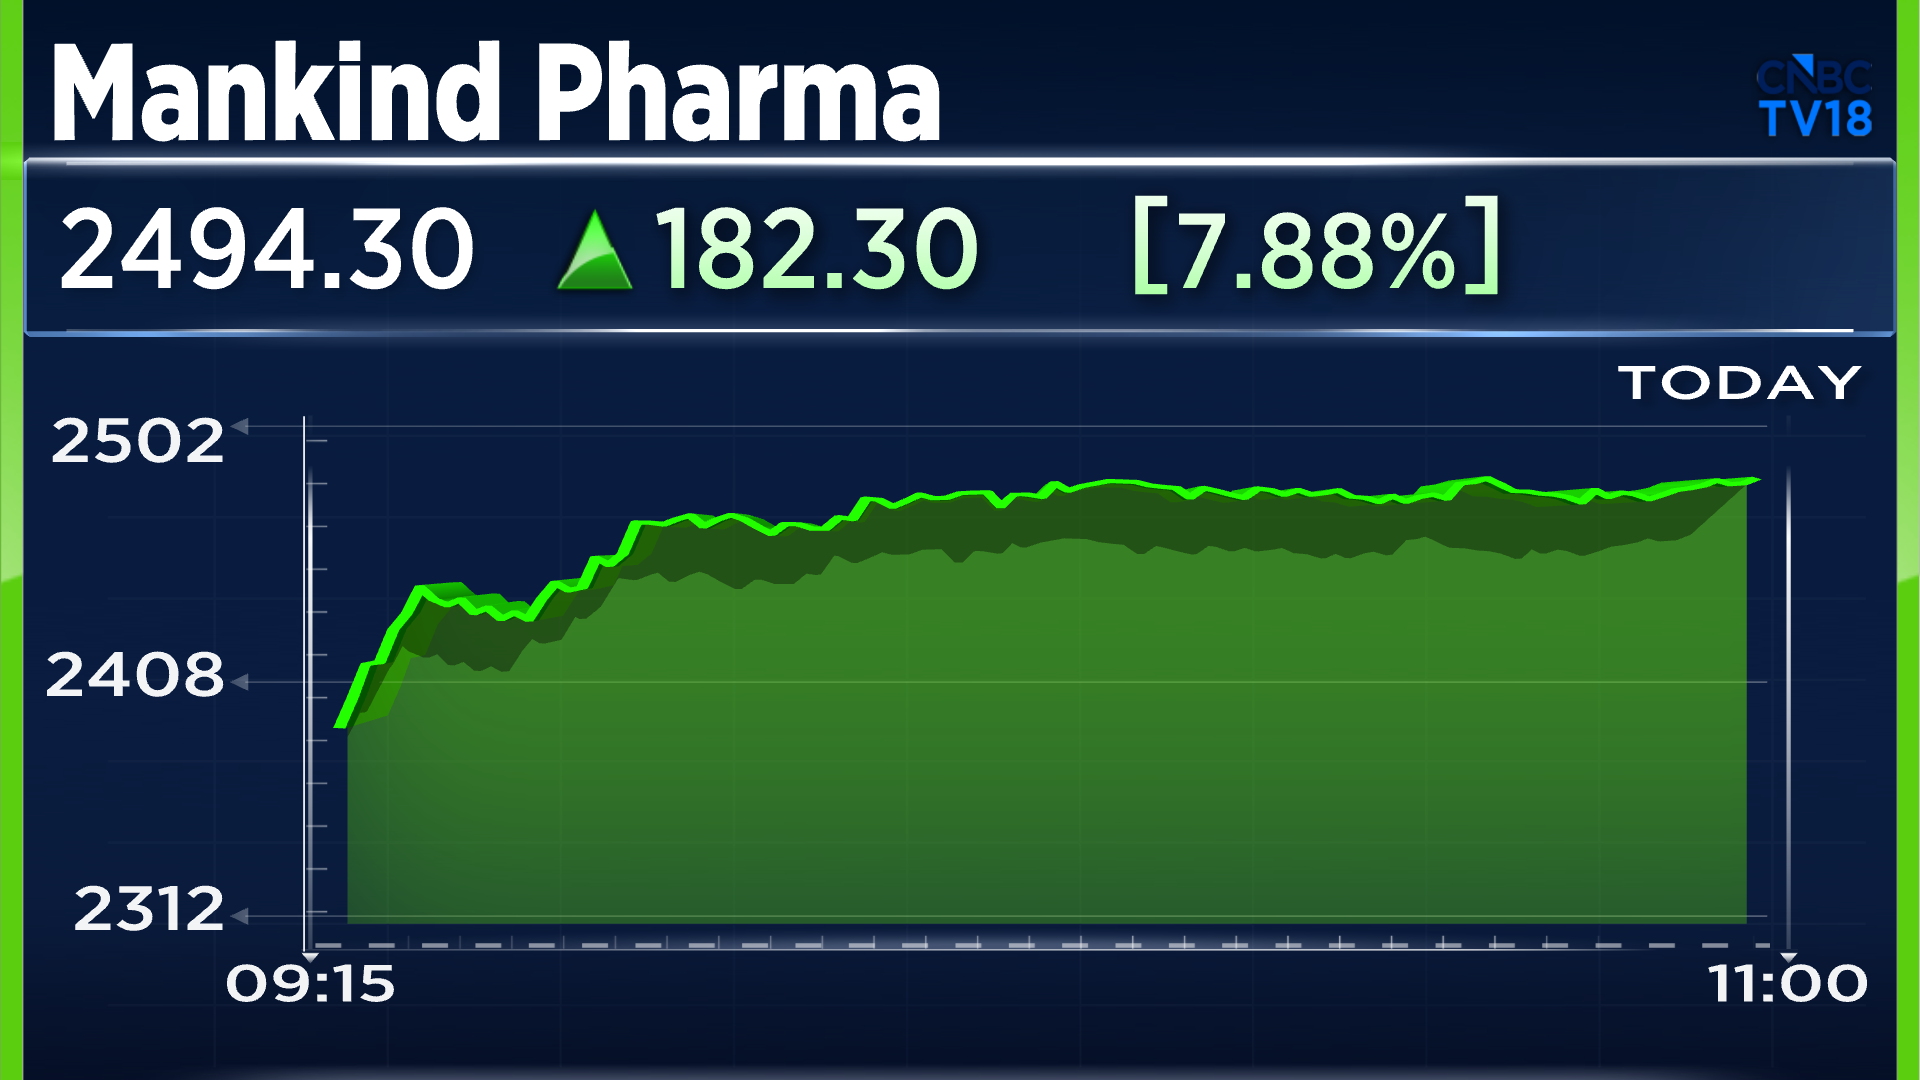
Shares of Mankind Pharma surged as much as 8.3% on Tuesday, hitting an intraday high of ₹2,503.40. The stock was trading 7.7% higher at ₹2,490. The stock has gained more than 15% so far in 2026.
The stock's 52-week high stands at ₹2,642, recorded on July 29, 2026, while its 52-week low is ₹1,909.70, recorded on March 23, 2026.
This is the biggest single-day gain for the stock in nearly two years.
Despite the earnings beat, global investment firms remain cautious, with three of the four firms maintaining negative or cautious ratings and target prices implying downside of 5.5% to 36% from Monday's close of ₹3,212. Concerns centre on the muted over-the-counter (OTC) business growth and the stock's valuation.
Mankind Pharma's domestic business grew by 15.9% during the quarter, with volume growth at 1.2 times that of the Indian Pharmaceutical Market (IPM). Its chronic portfolio grew 1.1 times faster than the market, led by 19% growth in cardiac and 16% in anti-diabetes.
The acute portfolio also outperformed the market by 1.1 times, supported by 19% growth in gastro and 26% in the VMN segment. Bharat Serums and Vaccines' domestic specialty business recorded steady double-digit growth, while the international business grew 33%. The over-the-counter (OTC) business, however, reported muted growth.
What global investment firms say
Kotak Institutional Equities: Buy | Target price: ₹3,035
Kotak Institutional Equities maintained a Buy rating on Mankind Pharma with a target price of ₹3,035. Based on Monday's closing price of ₹3,212, the target implies a downside of 5.5%.
Kotak expects Mankind Pharma's Earnings per share (EPS) to report a Compounded Annual Growth Rate (CAGR) of 23% over financial year 2026-2029. It identified the over-the-counter (OTC) business as a key concern, with growth yet to pick up.
JPMorgan: Neutral | Target price: ₹2,700
JPMorgan retained a "Neutral" rating and a target price of ₹2,700, implying a 15.9% downside from Monday's close.
The firm said second-quarter revenue beat estimates by 3%, led by the India prescription (Rx) business and exports. Earnings before interest, tax, depreciation and amortisation (EBITDA) margin came in at 27%, around 100 basis points above estimates.
However, the company's FY27 EBITDA margin guidance remains at 25.5%-26.5%. JPMorgan also noted that consumer business growth guidance had been reduced to single digits, with double-digit growth expected from the next financial year.
Macquarie: Underperform | Target price: ₹2,200
Macquarie maintained an Underperform rating and a target price of ₹2,200, implying a 31.5% downside from Monday's close.
The global investment firm said revenue, EBITDA and adjusted profit after tax (PAT) for the September quarter exceeded its estimates by 3%, 4% and 12%, respectively.
Bernstein: Underperform | Target price: ₹2,057
Bernstein maintained an Underperform rating with a target price of ₹2,057, implying a downside of 36% from Monday's closing price.
It said domestic growth of 15.9% was healthy, but the recovery remained uneven. It sees limited incremental evidence to justify Mankind Pharma's premium valuation.
Street view and stock reaction
Of the 22 analysts covering the stock, 15 have given it a "Buy" recommendation, three have a "Hold" rating, and the stock has four "Sell" ratings.
Investec has a Buy rating with a target price of ₹3,040, followed by Kotak Securities at ₹3,035. HDFC Research has a target price of ₹3,280, while Ambit Capital's target stands at ₹2,635. Morgan Stanley has an Equal-weight/Attractive recommendation with a target price of ₹2,595.
The 12-month consensus target price stands at ₹2,704, against the last price of ₹2,495.10, indicating a potential return of more than 8% from current levels..
Shares of Mankind Pharma surged as much as 8.3% on Tuesday, hitting an intraday high of ₹2,503.40. The stock was trading 7.7% higher at ₹2,490. The stock has gained more than 15% so far in 2026.
The stock's 52-week high stands at ₹2,642, recorded on July 29, 2026, while its 52-week low is ₹1,909.70, recorded on March 23, 2026.