What is the story about?
Jindal Stainless Ltd (JSL) has lowered its full-year volume growth guidance to 4-6% from the earlier 7-9% for the financial year 2026-27 (FY27), reflecting the impact of a weak first quarter.
However, the company has raised its earnings before interest, taxes, depreciation, and amortisation (EBITDA) per tonne guidance, signalling confidence in profitability even as volumes remain under pressure.
Tarun Khulbe, CEO and Whole-Time Director of Jindal Stainless Ltd, said the company expects business conditions to improve in the coming quarters, supported by export growth, capacity additions and operational efficiencies. He also said the company remains on track to reduce debt and expects a decision on protection against Chinese stainless steel imports by December.
Despite lowering volume expectations, the company improved its profitability outlook after reporting better-than-guided margins in the first half.
Khulbe said exports have remained resilient even though shipments to the European Union have been impacted by lower country-specific quotas.
To offset this, Jindal Stainless has expanded into new geographies and is increasing business with existing customers.
Khulbe said the sharp rise in stainless steel imports from China has been driven by the removal of quality control restrictions, allowing low-cost products to enter the Indian market.
He said the industry has approached the government for relief and expects progress in the ongoing investigation.
According to Khulbe, unchecked imports are hurting domestic manufacturers, particularly MSMEs, and impacting capacity utilisation across the sector.
[faq type="interview" title="This is an edited transcript of the interview."][ques][/ques][ans][/ans][/faq][faq type="interview"][ques]It was an encouraging performance in the past quarter because you have managed to ramp up exports yet again, and your EBITDA per tonne as well is holding out. So, give us a few details. In the past, you were guiding that volume growth should be seven to around 9%. Now the half-year mark actually looks a little bit challenging. Do you want to revise the volume guidance? And if you could tell us, do you see the export market contributing more? As of now, it's around 11%, but it's grown drastically. Will that continue?[/ques][ans]Coming to the volume part. If you remember, our first quarter was quite disturbed because of the war and the fuel problem, but in the second quarter, we have recovered and improved our numbers as far as volume is concerned. But still, you are right. If we look at our half-yearly numbers, while they are 14% higher on a year-on-year basis, they are still 2% lower on an H1-to-H1 basis. We hope that the coming quarters will do better. But in any case, because the damage of quarter one was a bit higher, we are revising our volume guidance, which was earlier 7% to 9%, down to 4% to 6%. Now coming to the domestic and export markets. Yes, you are right that we have improved our exports. In the export market, the EU (European Union), which we have always said is one of our major markets, has been impacted because the country-specific quotas have been reduced drastically. But yes, the FTA-specific quota will help us a bit. Still, there is quite a sharp drop in the EU market. As a company, we have gone into new territories. We are trying to increase our share with our existing customers. We hope that the brand we have created and our quality will continue to be well accepted. We hope that we should be able to maintain these numbers. In fact, some of the facilities that we are putting up in the future should help us offer an even better product range for exports.[/ans][/faq]
For the full interview, watch the accompanying video
Catch all the latest updates from the stock market here
However, the company has raised its earnings before interest, taxes, depreciation, and amortisation (EBITDA) per tonne guidance, signalling confidence in profitability even as volumes remain under pressure.
Tarun Khulbe, CEO and Whole-Time Director of Jindal Stainless Ltd, said the company expects business conditions to improve in the coming quarters, supported by export growth, capacity additions and operational efficiencies. He also said the company remains on track to reduce debt and expects a decision on protection against Chinese stainless steel imports by December.
Despite lowering volume expectations, the company improved its profitability outlook after reporting better-than-guided margins in the first half.
Khulbe said exports have remained resilient even though shipments to the European Union have been impacted by lower country-specific quotas.
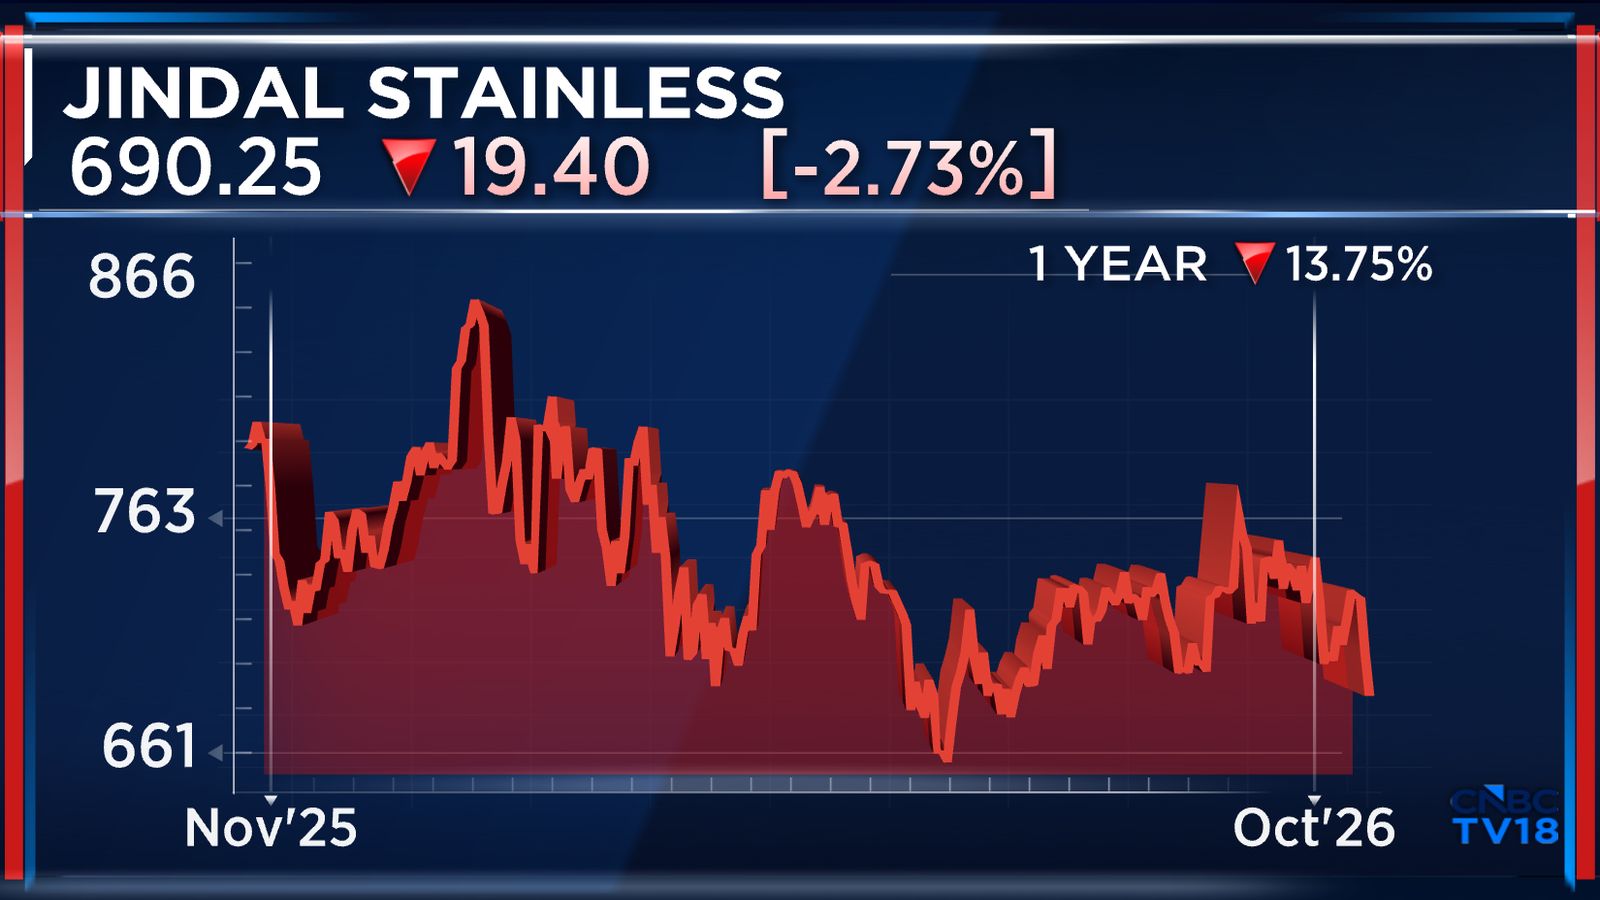
JSL shares were trading at ₹691.90 as of 11:23 am on the NSE. The company, which has a current market capitalisation of ₹57,041.59 crore, has seen its shares decline more than 13% over the last year.
To offset this, Jindal Stainless has expanded into new geographies and is increasing business with existing customers.
Khulbe said the sharp rise in stainless steel imports from China has been driven by the removal of quality control restrictions, allowing low-cost products to enter the Indian market.
He said the industry has approached the government for relief and expects progress in the ongoing investigation.
According to Khulbe, unchecked imports are hurting domestic manufacturers, particularly MSMEs, and impacting capacity utilisation across the sector.
[faq type="interview" title="This is an edited transcript of the interview."][ques][/ques][ans][/ans][/faq][faq type="interview"][ques]It was an encouraging performance in the past quarter because you have managed to ramp up exports yet again, and your EBITDA per tonne as well is holding out. So, give us a few details. In the past, you were guiding that volume growth should be seven to around 9%. Now the half-year mark actually looks a little bit challenging. Do you want to revise the volume guidance? And if you could tell us, do you see the export market contributing more? As of now, it's around 11%, but it's grown drastically. Will that continue?[/ques][ans]Coming to the volume part. If you remember, our first quarter was quite disturbed because of the war and the fuel problem, but in the second quarter, we have recovered and improved our numbers as far as volume is concerned. But still, you are right. If we look at our half-yearly numbers, while they are 14% higher on a year-on-year basis, they are still 2% lower on an H1-to-H1 basis. We hope that the coming quarters will do better. But in any case, because the damage of quarter one was a bit higher, we are revising our volume guidance, which was earlier 7% to 9%, down to 4% to 6%. Now coming to the domestic and export markets. Yes, you are right that we have improved our exports. In the export market, the EU (European Union), which we have always said is one of our major markets, has been impacted because the country-specific quotas have been reduced drastically. But yes, the FTA-specific quota will help us a bit. Still, there is quite a sharp drop in the EU market. As a company, we have gone into new territories. We are trying to increase our share with our existing customers. We hope that the brand we have created and our quality will continue to be well accepted. We hope that we should be able to maintain these numbers. In fact, some of the facilities that we are putting up in the future should help us offer an even better product range for exports.[/ans][/faq]
For the full interview, watch the accompanying video
Catch all the latest updates from the stock market here