What is the story about?
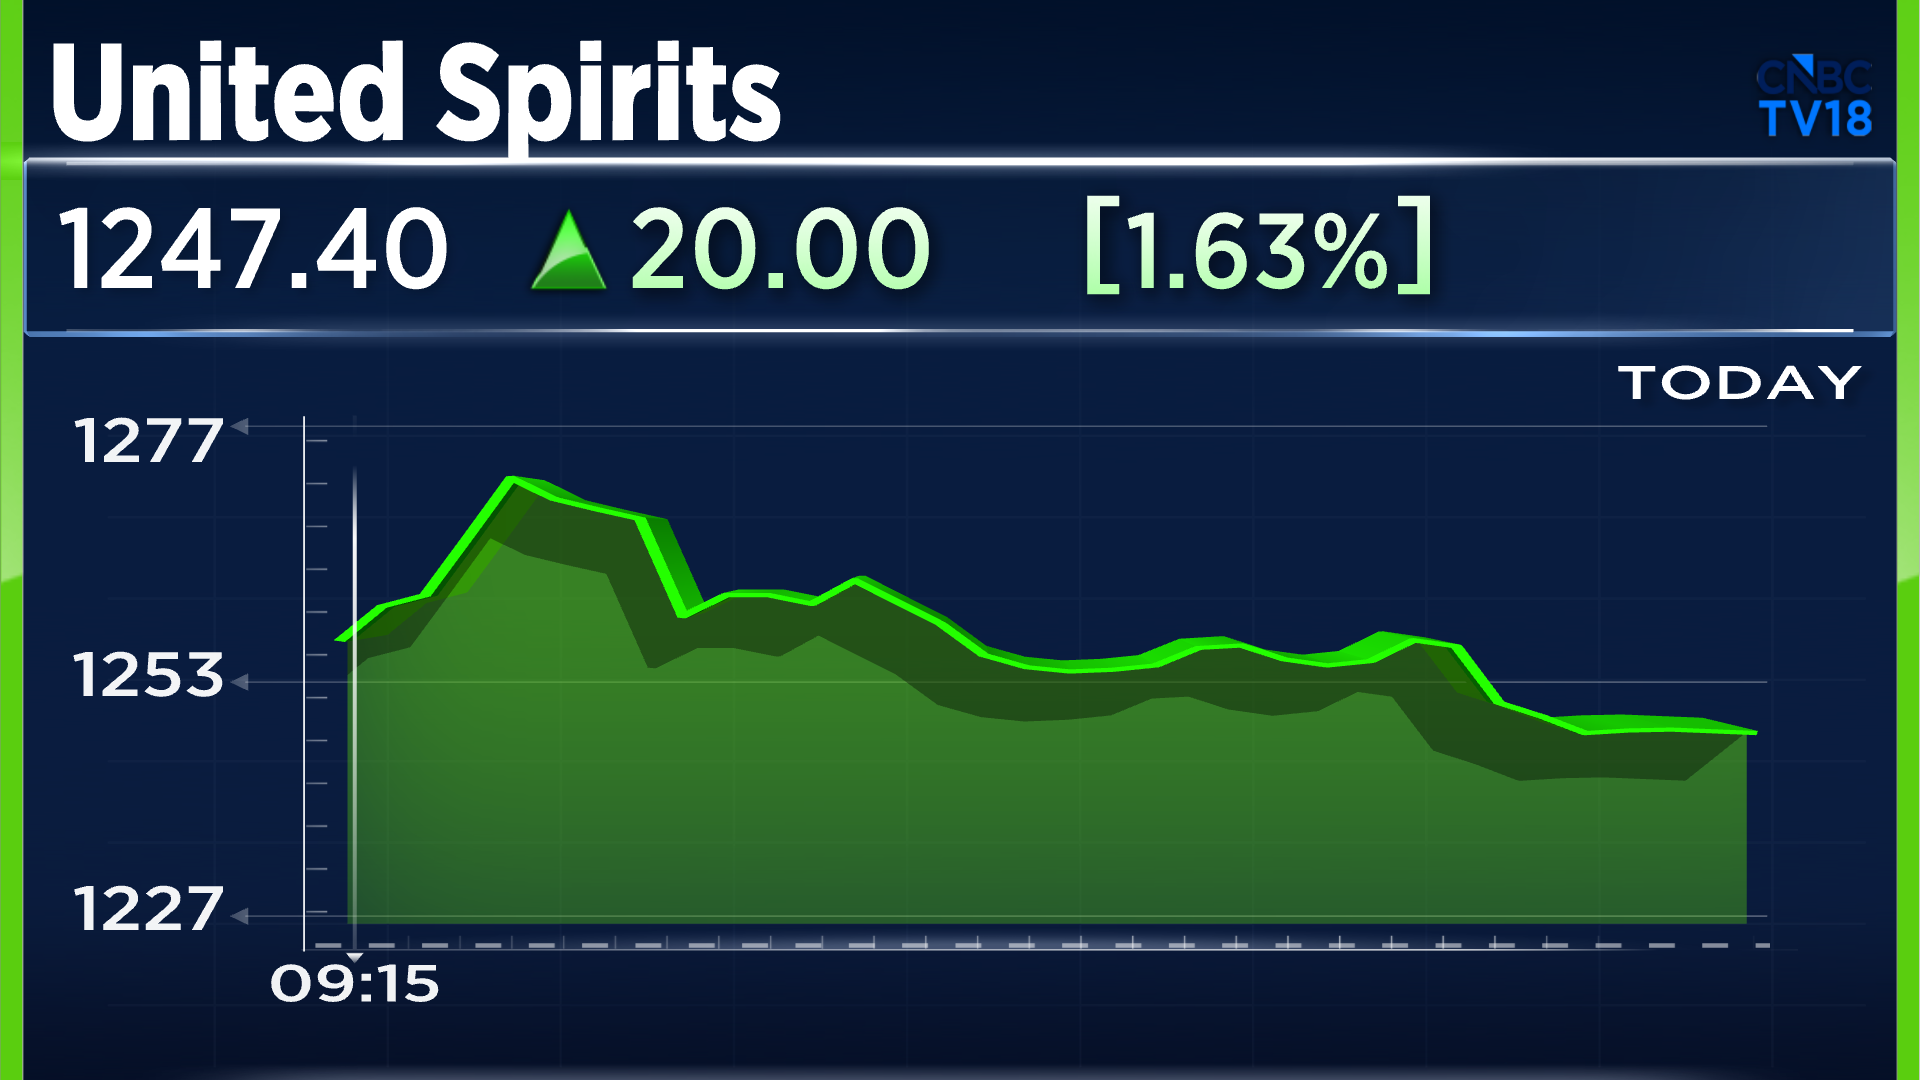
Shares of United Spirits gained as much as 4% on Thursday, October 29, after the Diageo-controlled liquor maker reported a 2.1% year-on-year decline in net profit to ₹462 crore for Q2FY27, missing the CNBC-TV18 poll estimate of ₹471 crore.
Revenue rose 2.8% to ₹3,258 crore but fell short of the estimated ₹3,348 crore, while earnings before interest, tax, depreciation and amortisation (EBITDA) declined 4.3% to ₹643 crore.
EBITDA came in above the poll estimate of ₹637 crore, but the margin contracted to 19.7% from 21.2% a year ago. The company increased advertising and promotion spending ahead of the festive season, with the outlay rising 56.8% year-on-year to ₹378 crore from ₹241 crore.
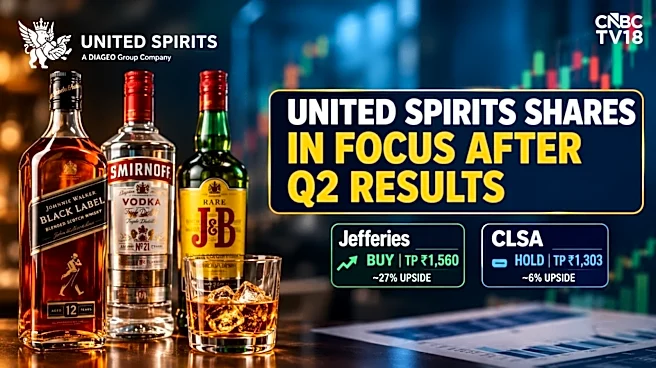
Following the results, global investment firm Jefferies maintained its Buy rating with a target price of ₹1,560, implying around 27% upside from Wednesday’s close of ₹1,229, while CLSA retained its Hold rating with a target of ₹1,303, indicating around 6% upside.
Praveen Someshwar, CEO and Managing Director of United Spirits, said, “We delivered a resilient quarter despite a strong prior-year base and regulatory headwinds, while continuing to invest behind our brands for long-term growth.”
He added that the relaunch of J&B Scotch, enabled by the India-UK free trade agreement, offers a proposition aimed at expanding Scotch penetration. The company has also entered the ready-to-drink segment with Smirnoff Ice.
United Spirits reported underlying volume pressure in its Popular segment, where volumes declined 29.7%, amid adverse policy changes in Maharashtra and Karnataka. The company said the impact of the Maharashtra policy on its business, along with policy changes in Karnataka, continued to weigh on growth and realisations.
The Prestige & Above segment recorded growth of 6.3%, partly offsetting the weakness in the Popular portfolio.
Gross margin improved to 48% from 47.1% in the year-ago quarter, supported by product mix and productivity gains. However, advertising and promotion spending increased to 11.6% of net sales value (NSV) from 7.6% a year earlier, as the company stepped up investments behind its brands and new launches ahead of the festive season.
The company said the continuing impact of adverse policy in Maharashtra and Karnataka affected growth and realisations. In Maharashtra, the impact of the MML policy continued to weigh on the Popular segment, while excise slab changes in Karnataka affected realisations and growth.
Someshwar said the company was looking ahead to the festive quarter with confidence.
Jefferies maintained its Buy rating on United Spirits with a target price of ₹1,560, implying an upside of around 27% from Wednesday’s closing price of ₹1,227.4.
The brokerage said the September quarter performance of the Prestige & Above segment remained underwhelming compared with peers, with volumes declining around 1% as momentum in Smirnoff and J&B was offset by headwinds in Maharashtra. Regular segment volumes fell 30%.
Jefferies noted that improved product mix and productivity lifted gross margin by 88 basis points to 48%. However, the 57% increase in A&P spending drove EBITDA margin down by around 146 basis points to 19.7%, although EBITDA came in above the brokerage’s estimate. Jefferies also highlighted strong first-half operating cash flow of ₹1,100 crore and free cash flow of ₹1,000 crore.
CLSA maintained its Hold rating on United Spirits with a target price of ₹1,303, implying an upside of more than 6% from Wednesday’s closing price.
The brokerage said Prestige & Above volumes declined 1.6% year-on-year in Q2FY27, or 1.2% after reclassification of McDowell’s No.1 brandy, below its expectation of 0.5% growth. The decline in Popular category volumes was also sharper than estimated.
CLSA noted that net sales grew 2.8% year-on-year, below its estimate of 5% and consensus growth of 5.6%. Gross margin expanded by 88 basis points year-on-year and was above its estimate and consensus. However, EBITDA margin declined by around 146 basis points as A&P spending remained elevated.
According to Bloomberg's Analyst consensus data, the stock has 22 Buy, five Hold and two Sell ratings. The 12-month consensus target price stood at ₹1,614.67, compared with the last price of ₹1,227.40, indicating a potential upside of nearly 32%.
Shares of United Spirits ended Wednesday’s session at ₹1,227.40, down 3.4%, ahead of the results announcement. The stock has fallen about 13% so far in 2026.
Revenue rose 2.8% to ₹3,258 crore but fell short of the estimated ₹3,348 crore, while earnings before interest, tax, depreciation and amortisation (EBITDA) declined 4.3% to ₹643 crore.
EBITDA came in above the poll estimate of ₹637 crore, but the margin contracted to 19.7% from 21.2% a year ago. The company increased advertising and promotion spending ahead of the festive season, with the outlay rising 56.8% year-on-year to ₹378 crore from ₹241 crore.
Following the results, global investment firm Jefferies maintained its Buy rating with a target price of ₹1,560, implying around 27% upside from Wednesday’s close of ₹1,229, while CLSA retained its Hold rating with a target of ₹1,303, indicating around 6% upside.
Praveen Someshwar, CEO and Managing Director of United Spirits, said, “We delivered a resilient quarter despite a strong prior-year base and regulatory headwinds, while continuing to invest behind our brands for long-term growth.”
He added that the relaunch of J&B Scotch, enabled by the India-UK free trade agreement, offers a proposition aimed at expanding Scotch penetration. The company has also entered the ready-to-drink segment with Smirnoff Ice.
Popular segment volumes decline sharply
United Spirits reported underlying volume pressure in its Popular segment, where volumes declined 29.7%, amid adverse policy changes in Maharashtra and Karnataka. The company said the impact of the Maharashtra policy on its business, along with policy changes in Karnataka, continued to weigh on growth and realisations.
The Prestige & Above segment recorded growth of 6.3%, partly offsetting the weakness in the Popular portfolio.
| Metric | Q2FY27 | Q2FY26 | YoY change |
|---|---|---|---|
| Revenue | ₹3,258 crore | ₹3,170 crore | +2.8% |
| EBITDA | ₹643 crore | ₹672 crore | -4.3% |
| EBITDA margin | 19.7% | 21.2% | -150 bps |
| Net profit | ₹462 crore | ₹472 crore | -2.1% |
| Gross margin | 48.0% | 47.1% | +90 bps |
| Advertising and promotion spend | ₹378 crore | ₹241 crore | +56.8% |
Gross margin expands, advertising spend rises
Gross margin improved to 48% from 47.1% in the year-ago quarter, supported by product mix and productivity gains. However, advertising and promotion spending increased to 11.6% of net sales value (NSV) from 7.6% a year earlier, as the company stepped up investments behind its brands and new launches ahead of the festive season.
The company said the continuing impact of adverse policy in Maharashtra and Karnataka affected growth and realisations. In Maharashtra, the impact of the MML policy continued to weigh on the Popular segment, while excise slab changes in Karnataka affected realisations and growth.
Someshwar said the company was looking ahead to the festive quarter with confidence.
Jefferies retains Buy, sees 27% upside
Jefferies maintained its Buy rating on United Spirits with a target price of ₹1,560, implying an upside of around 27% from Wednesday’s closing price of ₹1,227.4.
The brokerage said the September quarter performance of the Prestige & Above segment remained underwhelming compared with peers, with volumes declining around 1% as momentum in Smirnoff and J&B was offset by headwinds in Maharashtra. Regular segment volumes fell 30%.
Jefferies noted that improved product mix and productivity lifted gross margin by 88 basis points to 48%. However, the 57% increase in A&P spending drove EBITDA margin down by around 146 basis points to 19.7%, although EBITDA came in above the brokerage’s estimate. Jefferies also highlighted strong first-half operating cash flow of ₹1,100 crore and free cash flow of ₹1,000 crore.
CLSA maintains Hold, target at ₹1,303
CLSA maintained its Hold rating on United Spirits with a target price of ₹1,303, implying an upside of more than 6% from Wednesday’s closing price.
The brokerage said Prestige & Above volumes declined 1.6% year-on-year in Q2FY27, or 1.2% after reclassification of McDowell’s No.1 brandy, below its expectation of 0.5% growth. The decline in Popular category volumes was also sharper than estimated.
CLSA noted that net sales grew 2.8% year-on-year, below its estimate of 5% and consensus growth of 5.6%. Gross margin expanded by 88 basis points year-on-year and was above its estimate and consensus. However, EBITDA margin declined by around 146 basis points as A&P spending remained elevated.
Analyst consensus and stock reaction
According to Bloomberg's Analyst consensus data, the stock has 22 Buy, five Hold and two Sell ratings. The 12-month consensus target price stood at ₹1,614.67, compared with the last price of ₹1,227.40, indicating a potential upside of nearly 32%.
Shares of United Spirits ended Wednesday’s session at ₹1,227.40, down 3.4%, ahead of the results announcement. The stock has fallen about 13% so far in 2026.