What is the story about?
ICICI Prudential Life Insurance Ltd. shares are trading higher on Wednesday, October 14, after the insurer reported a 20.7% year-on-year rise in the value of new business (VNB) for the September quarter, although the metric fell short of estimates.
Global investment banking firms remain positive on the stock, with target prices ranging from ₹582 to ₹710, citing improving business fundamentals, even as concerns persist over margins and the visibility of future growth.
ICICI Prudential Life reported VNB of ₹712 crore for the second quarter of financial year 2027, against the CNBC-TV18 poll estimate of ₹722 crore. The VNB margin improved to 25.43% from 24% a year earlier, but came in marginally below the poll estimate of 25.79%.
Annual premium equivalent (APE) rose 16.6% year-on-year to ₹2,799 crore, in line with estimates, while retail APE increased by 10.7% to ₹2,221 crore, marginally ahead of the poll estimate.
For the first half of FY27, VNB rose 22.3% year-on-year to ₹1,283 crore, with a margin of 26%. Profit after tax increased 26.5% to ₹760 crore from ₹601 crore a year earlier, supported primarily by higher shareholders’ investment income and improved surplus generation in the existing policyholder portfolio.
HSBC maintained its "Buy" rating on ICICI Prudential Life with a target price of ₹582, implying an upside of about 30% from Tuesday’s closing price of ₹447.
The global investment banking firm said second-quarter VNB was marginally ahead of its estimate, with margins benefiting from a favourable product mix and the yield curve. It also noted a steady improvement in the insurer’s fundamentals, identifying regulatory clarity and Prudential’s stake sale as key potential catalysts.
HSBC believes the stock’s valuation of around 1 times estimated embedded value for FY28 is inexpensive and limits the downside risk.
Nomura also maintained its "Buy" rating but set a higher target price of ₹710, indicating a potential upside of 59% from Tuesday’s close.
The global investment banking firms flagged the VNB margin miss, at 25.4% against its estimate of 26.7%, but pointed to 22% year-on-year VNB growth in the first half of FY27. It expects VNB growth of 14% for the full financial year, with a high base in protection business expected to weigh on growth in the second half.
Nomura said momentum in non-participating products is picking up and expects the agency channel to grow faster than the company in the coming years. It also believes distribution reforms will not have a significant impact on the stock.
JPMorgan maintained its Overweight rating on ICICI Prudential Life, with a target price of ₹670, implying an upside of 50% from Tuesday’s close.
The brokerage said the VNB rise was 2.7% below its estimate, as the VNB margin expanded 100 basis points year-on-year but declined 129 basis points sequentially to 25.4%.
JPMorgan attributed the quarter-on-quarter margin moderation largely to a lower contribution from protection business. Protection’s share of the business mix fell to 20% in the September quarter, down 790 basis points sequentially, although it remained 270 basis points higher than a year earlier.
While retail APE growth improved to 10.5% year-on-year, JPMorgan noted that management did not provide near-term guidance on growth or margins. It believes the stock could see a bounce given its valuation of around 1 times estimated FY28 price-to-embedded value, but said a sustained re-rating would depend on consistent retail APE growth and greater clarity on the regulatory environment.
According to the Bloomberg analyst data, 36 analysts have coverage on the stock, with 33 giving it a "Buy" rating, while three have a "Hold" rating. There are no "Sell" recommendations. The 12-month consensus price target of ₹621.41, implies an upside potential of 39% from Tuesday's close.
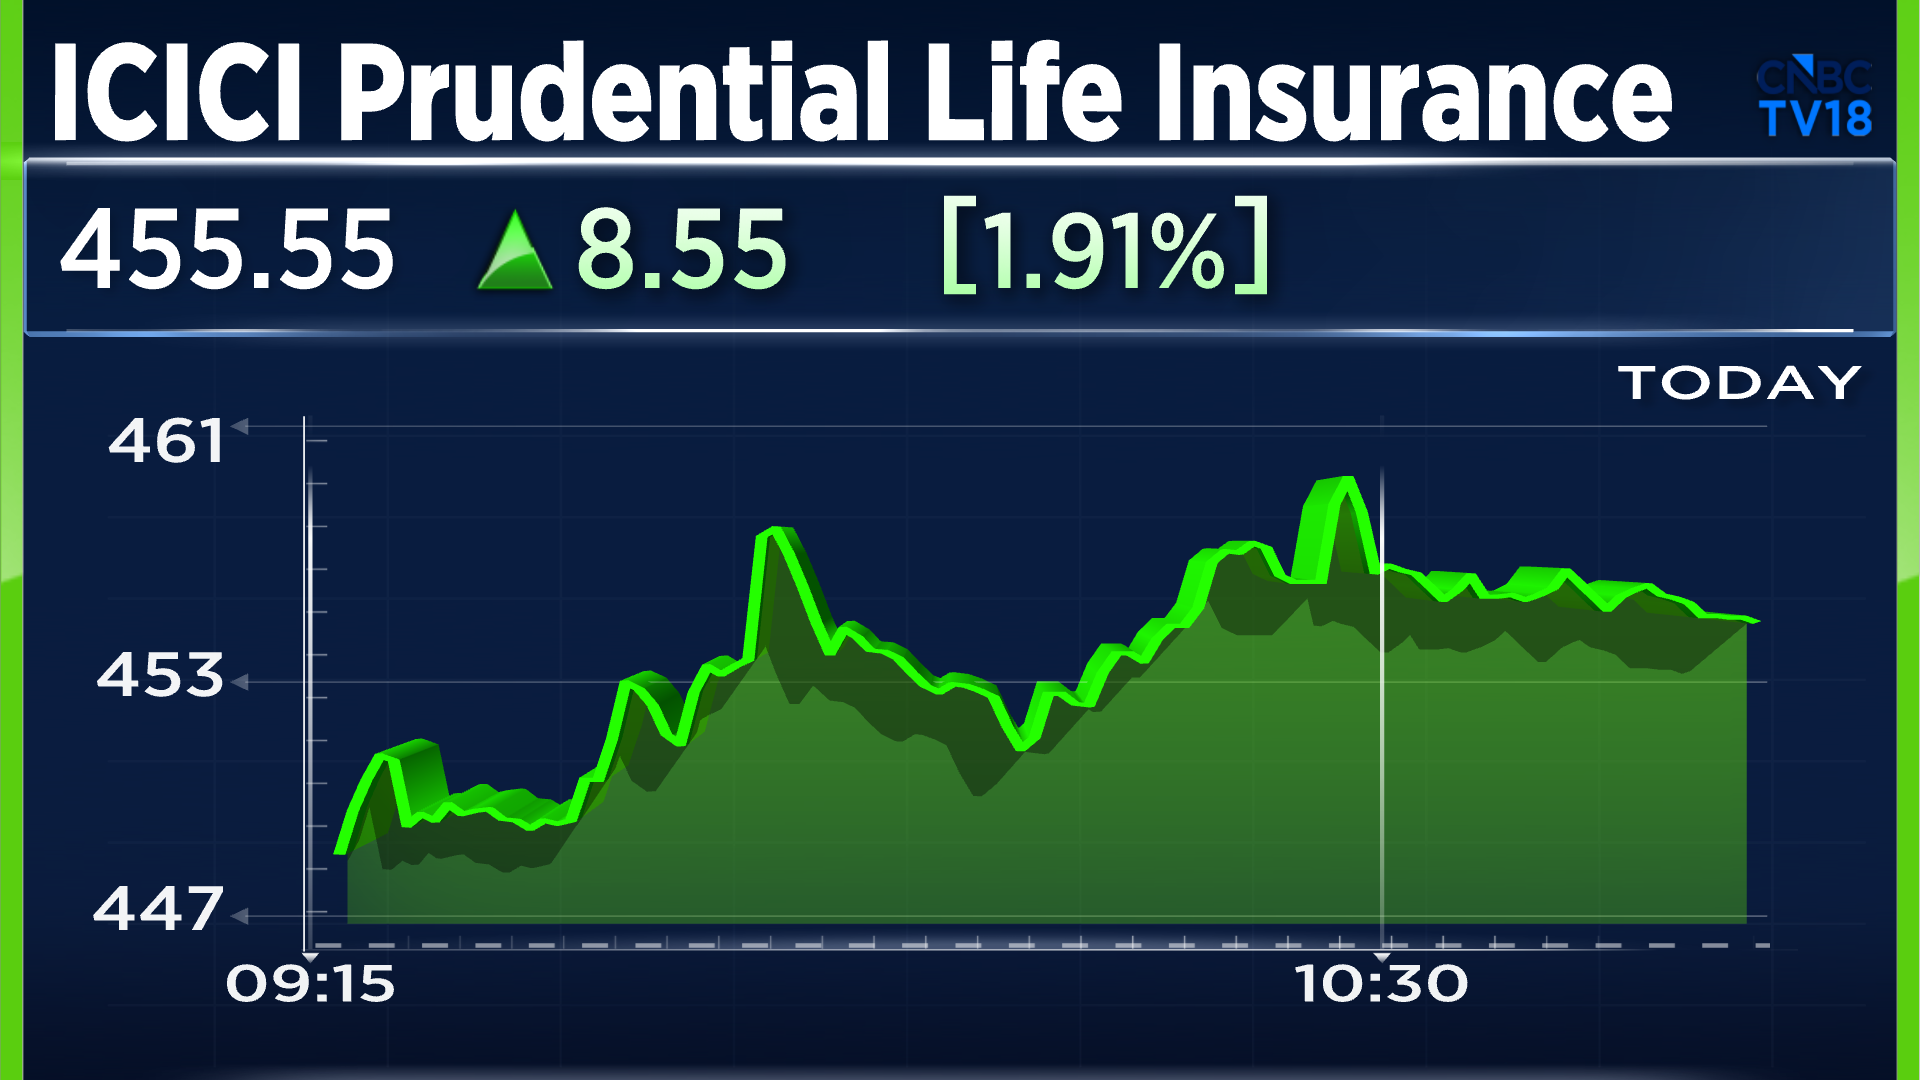
Shares of ICICI Prudential Life Insurance are trading 1.4% higher on Wednesday at ₹453.3. The stock is still down 33% on a year-to-date basis and is trading close to its 52-week low of ₹441.8.
Also read: Foreign investors will 'rediscover India' as earnings growth stays strong, says Blackstone's Jon Gray
Global investment banking firms remain positive on the stock, with target prices ranging from ₹582 to ₹710, citing improving business fundamentals, even as concerns persist over margins and the visibility of future growth.
ICICI Prudential Life reported VNB of ₹712 crore for the second quarter of financial year 2027, against the CNBC-TV18 poll estimate of ₹722 crore. The VNB margin improved to 25.43% from 24% a year earlier, but came in marginally below the poll estimate of 25.79%.
Annual premium equivalent (APE) rose 16.6% year-on-year to ₹2,799 crore, in line with estimates, while retail APE increased by 10.7% to ₹2,221 crore, marginally ahead of the poll estimate.
For the first half of FY27, VNB rose 22.3% year-on-year to ₹1,283 crore, with a margin of 26%. Profit after tax increased 26.5% to ₹760 crore from ₹601 crore a year earlier, supported primarily by higher shareholders’ investment income and improved surplus generation in the existing policyholder portfolio.
HSBC sees limited downside at current valuations
HSBC maintained its "Buy" rating on ICICI Prudential Life with a target price of ₹582, implying an upside of about 30% from Tuesday’s closing price of ₹447.
The global investment banking firm said second-quarter VNB was marginally ahead of its estimate, with margins benefiting from a favourable product mix and the yield curve. It also noted a steady improvement in the insurer’s fundamentals, identifying regulatory clarity and Prudential’s stake sale as key potential catalysts.
HSBC believes the stock’s valuation of around 1 times estimated embedded value for FY28 is inexpensive and limits the downside risk.
Nomura sees nearly 59% upside for ICICI Prudential
Nomura also maintained its "Buy" rating but set a higher target price of ₹710, indicating a potential upside of 59% from Tuesday’s close.
The global investment banking firms flagged the VNB margin miss, at 25.4% against its estimate of 26.7%, but pointed to 22% year-on-year VNB growth in the first half of FY27. It expects VNB growth of 14% for the full financial year, with a high base in protection business expected to weigh on growth in the second half.
Nomura said momentum in non-participating products is picking up and expects the agency channel to grow faster than the company in the coming years. It also believes distribution reforms will not have a significant impact on the stock.
JPMorgan sees scope for a bounce, but flags growth visibility
JPMorgan maintained its Overweight rating on ICICI Prudential Life, with a target price of ₹670, implying an upside of 50% from Tuesday’s close.
The brokerage said the VNB rise was 2.7% below its estimate, as the VNB margin expanded 100 basis points year-on-year but declined 129 basis points sequentially to 25.4%.
JPMorgan attributed the quarter-on-quarter margin moderation largely to a lower contribution from protection business. Protection’s share of the business mix fell to 20% in the September quarter, down 790 basis points sequentially, although it remained 270 basis points higher than a year earlier.
While retail APE growth improved to 10.5% year-on-year, JPMorgan noted that management did not provide near-term guidance on growth or margins. It believes the stock could see a bounce given its valuation of around 1 times estimated FY28 price-to-embedded value, but said a sustained re-rating would depend on consistent retail APE growth and greater clarity on the regulatory environment.
ICICI Prudential Life shares: Analyst consensus
According to the Bloomberg analyst data, 36 analysts have coverage on the stock, with 33 giving it a "Buy" rating, while three have a "Hold" rating. There are no "Sell" recommendations. The 12-month consensus price target of ₹621.41, implies an upside potential of 39% from Tuesday's close.
Shares of ICICI Prudential Life Insurance are trading 1.4% higher on Wednesday at ₹453.3. The stock is still down 33% on a year-to-date basis and is trading close to its 52-week low of ₹441.8.
Also read: Foreign investors will 'rediscover India' as earnings growth stays strong, says Blackstone's Jon Gray