

What is the story about?
Vodafone Idea's potential ₹35,000-crore bank fundraise could accelerate network investment and improve its growth prospects, but Axis Capital remains cautious on the stock.
Gaurav Malhotra, Executive Director - Telecom at Axis Capital, said the brokerage retains a Reduce rating with a ₹13 target price, even after factoring in the fundraise, network improvement, tariff hikes and stronger earnings before interest, taxes, depreciation and amortisation (EBITDA) growth.
“The way to think about the stock price, it's obviously moved up very sharply,” Malhotra said. He added that Axis Capital's ₹13 target already assumes the fundraise, network improvement and strong EBITDA growth, suggesting the recent rally has moved the stock beyond what the brokerage considers justified on fundamentals.
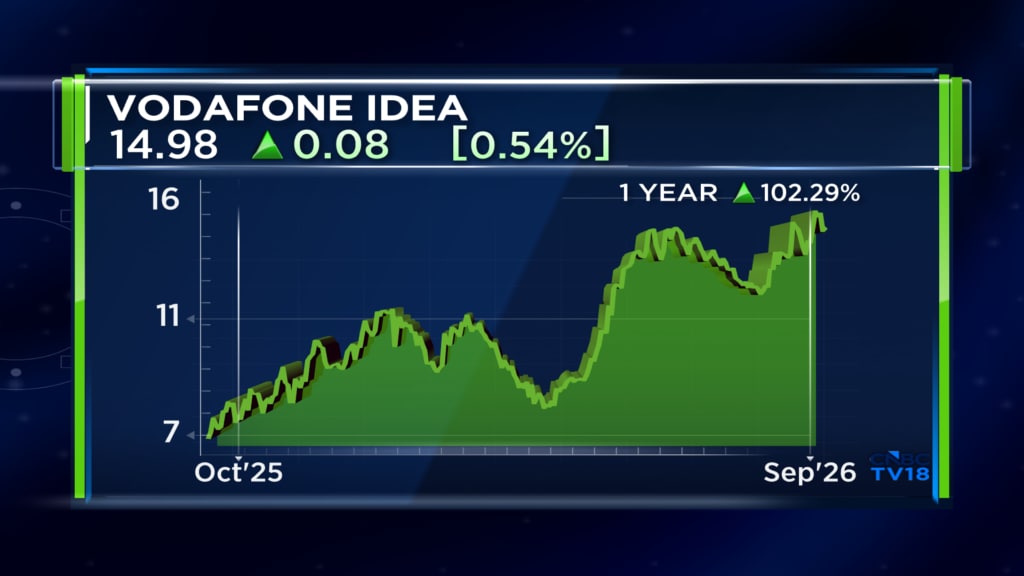
Axis Capital expects Vodafone Idea's average revenue per user (ARPU) to grow faster than Bharti Airtel's over the next 2-3 years, helped by tariff increases, premiumisation and better network quality. The brokerage also expects EBITDA growth to be strong, with cash EBITDA estimated at around ₹18,000-19,000 crore over the next couple of years.
The key valuation question, however, is whether Vodafone Idea should command a premium to Bharti Airtel because it is starting from a lower base and could grow faster, or continue to trade at a discount. Malhotra believes Bharti remains the benchmark. “We still feel that Bharti remains the best in class. So, Vodafone should be benchmarked off Bharti,” he said.
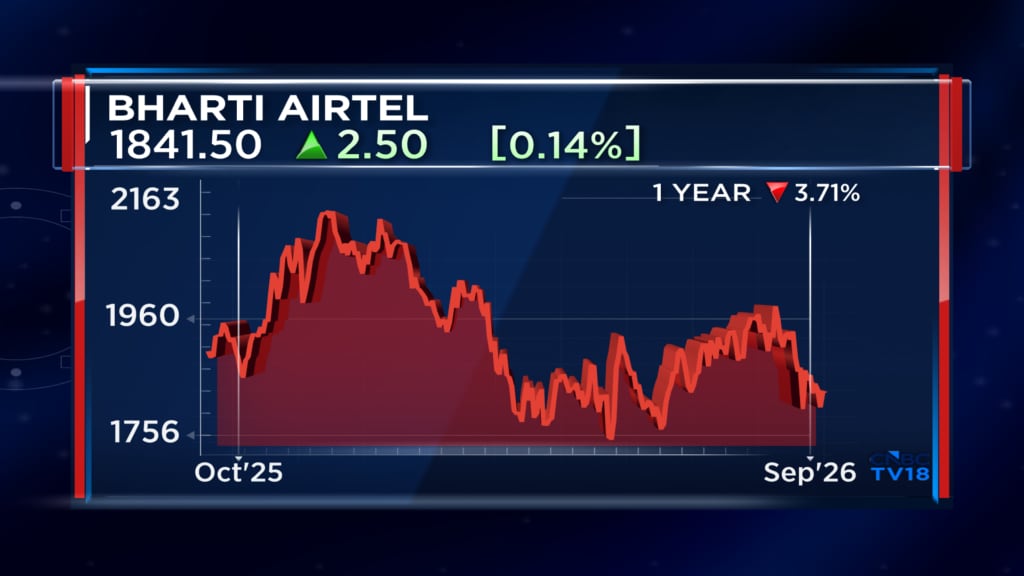
For Bharti Airtel, the main concern is the timing of the next tariff hike. Axis Capital expects a 10-12% broad-based tariff increase, but now sees it happening within the next six months rather than three months. Malhotra said Bharti's recent tariff intervention means it could take another 4-5 months for the impact to flow through its numbers.
Despite the near-term weakness, Bharti remains Axis Capital's top telecom pick. Malhotra said its India business is trading at around 9.5 times one-year forward valuation, which he considers compelling.
Watch the full conversation here
Indus Towers is another beneficiary of a potential Vodafone Idea fundraise. Higher funding for Vodafone Idea would support network investment and increase tenancies for Indus Towers. Axis Capital has a positive view on the stock, which currently trades at around six times EV/EBITDA, and believes it should command a premium to its long-term average.
Catch all the latest updates from the stock market here
Gaurav Malhotra, Executive Director - Telecom at Axis Capital, said the brokerage retains a Reduce rating with a ₹13 target price, even after factoring in the fundraise, network improvement, tariff hikes and stronger earnings before interest, taxes, depreciation and amortisation (EBITDA) growth.
“The way to think about the stock price, it's obviously moved up very sharply,” Malhotra said. He added that Axis Capital's ₹13 target already assumes the fundraise, network improvement and strong EBITDA growth, suggesting the recent rally has moved the stock beyond what the brokerage considers justified on fundamentals.
Axis Capital expects Vodafone Idea's average revenue per user (ARPU) to grow faster than Bharti Airtel's over the next 2-3 years, helped by tariff increases, premiumisation and better network quality. The brokerage also expects EBITDA growth to be strong, with cash EBITDA estimated at around ₹18,000-19,000 crore over the next couple of years.
The key valuation question, however, is whether Vodafone Idea should command a premium to Bharti Airtel because it is starting from a lower base and could grow faster, or continue to trade at a discount. Malhotra believes Bharti remains the benchmark. “We still feel that Bharti remains the best in class. So, Vodafone should be benchmarked off Bharti,” he said.
For Bharti Airtel, the main concern is the timing of the next tariff hike. Axis Capital expects a 10-12% broad-based tariff increase, but now sees it happening within the next six months rather than three months. Malhotra said Bharti's recent tariff intervention means it could take another 4-5 months for the impact to flow through its numbers.
Despite the near-term weakness, Bharti remains Axis Capital's top telecom pick. Malhotra said its India business is trading at around 9.5 times one-year forward valuation, which he considers compelling.
Watch the full conversation here
Indus Towers is another beneficiary of a potential Vodafone Idea fundraise. Higher funding for Vodafone Idea would support network investment and increase tenancies for Indus Towers. Axis Capital has a positive view on the stock, which currently trades at around six times EV/EBITDA, and believes it should command a premium to its long-term average.
Catch all the latest updates from the stock market here