What is the story about?
Shares of Sundaram-Clayton rallied on Wednesday after the company reported an improvement in its operating performance for the September quarter, with revenue rising sharply and its net loss narrowing from a year earlier.
The stock touched an intraday high of ₹1,175.85, up ₹117.55, or 11.1%, from the day’s low of ₹1,058.30.
Sundaram-Clayton reported revenue growth of 41% year on year to ₹698 crore in Q2 FY27, compared with ₹495 crore in the corresponding quarter last year.
At the operating level, earnings before interest, tax, depreciation and amortisation (EBITDA) rose to ₹33 crore from ₹5 crore in the year-ago period. EBITDA margin also improved to 4.7% from 1%, reflecting a recovery in operating performance despite continued cost pressures.
The company, however, remained in the red, reporting a net loss of ₹51 crore against a loss of ₹64 crore a year earlier. This represents a narrowing of around 20% in its quarterly loss.
First-half performance
For the first half of FY27, Sundaram-Clayton reported a 28% year-on-year increase in income to ₹1,159.8 crore. Profit after tax rose 52% to ₹56.5 crore, indicating stronger profitability over the six-month period.
The company attributed its performance to broad-based customer growth and robust export demand. This came despite continued pressure from elevated alloy, energy and logistics costs.
Automotive demand supports growth
The company said the Indian automotive industry recorded healthy growth during the first half, particularly in segments relevant to its business.
Medium and heavy commercial vehicle sales rose 23% year on year during H1 FY27, with growth accelerating to 33% in the September quarter. Demand was supported by pre-buying ahead of an October price increase, along with continued activity in infrastructure and mining.
Passenger vehicle volumes also remained strong, growing 24% in Q2, supported by demand across rural and urban markets and improved affordability following GST 2.0.
International markets presented a mixed picture. North American Class 8 retail sales grew 10% year on year during the July-September quarter, while production increased 53%. Heavy commercial vehicle registrations in Europe also remained positive.
Cost pressures and US operations remain key focus areas
Sundaram-Clayton said geopolitical developments in the Middle East continued to create uncertainty across global commodity and logistics markets. Volatility in aluminium prices, energy costs and freight rates remained a source of pressure on input costs and operating margins.
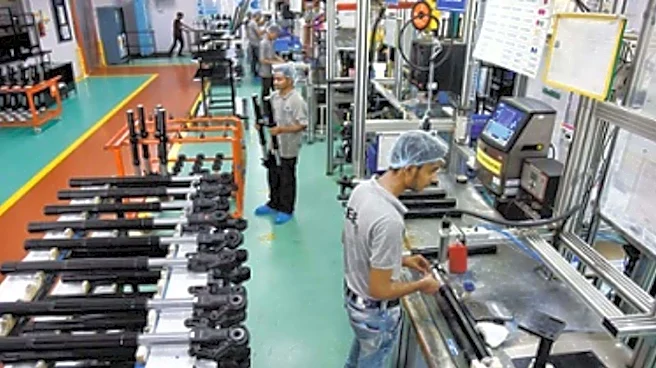
The company said it was working to strengthen supply-chain resilience, improve cost competitiveness and maintain operational continuity. Production across its Indian manufacturing facilities continued to increase in line with customer requirements.
Its US operations, meanwhile, continued to ramp up production during the quarter, supporting manufacturing performance and customer deliveries. However, the business continued to weigh on consolidated profitability.
Management said it remained focused on achieving a financial turnaround in the US through restructuring and improvements in production and operating metrics. The initiatives are aimed at improving sales, cost competitiveness and overall execution.
Sundaram-Clayton is an automotive components manufacturer specialising in aluminium die-cast products. Its components are used across commercial vehicles, passenger vehicles and other industrial applications, with operations serving customers in India and overseas.
The stock touched an intraday high of ₹1,175.85, up ₹117.55, or 11.1%, from the day’s low of ₹1,058.30.
Sundaram-Clayton reported revenue growth of 41% year on year to ₹698 crore in Q2 FY27, compared with ₹495 crore in the corresponding quarter last year.
At the operating level, earnings before interest, tax, depreciation and amortisation (EBITDA) rose to ₹33 crore from ₹5 crore in the year-ago period. EBITDA margin also improved to 4.7% from 1%, reflecting a recovery in operating performance despite continued cost pressures.
The company, however, remained in the red, reporting a net loss of ₹51 crore against a loss of ₹64 crore a year earlier. This represents a narrowing of around 20% in its quarterly loss.
First-half performance
For the first half of FY27, Sundaram-Clayton reported a 28% year-on-year increase in income to ₹1,159.8 crore. Profit after tax rose 52% to ₹56.5 crore, indicating stronger profitability over the six-month period.
The company attributed its performance to broad-based customer growth and robust export demand. This came despite continued pressure from elevated alloy, energy and logistics costs.
Automotive demand supports growth
The company said the Indian automotive industry recorded healthy growth during the first half, particularly in segments relevant to its business.
Medium and heavy commercial vehicle sales rose 23% year on year during H1 FY27, with growth accelerating to 33% in the September quarter. Demand was supported by pre-buying ahead of an October price increase, along with continued activity in infrastructure and mining.
Passenger vehicle volumes also remained strong, growing 24% in Q2, supported by demand across rural and urban markets and improved affordability following GST 2.0.
International markets presented a mixed picture. North American Class 8 retail sales grew 10% year on year during the July-September quarter, while production increased 53%. Heavy commercial vehicle registrations in Europe also remained positive.
Cost pressures and US operations remain key focus areas
Sundaram-Clayton said geopolitical developments in the Middle East continued to create uncertainty across global commodity and logistics markets. Volatility in aluminium prices, energy costs and freight rates remained a source of pressure on input costs and operating margins.
The company said it was working to strengthen supply-chain resilience, improve cost competitiveness and maintain operational continuity. Production across its Indian manufacturing facilities continued to increase in line with customer requirements.
Its US operations, meanwhile, continued to ramp up production during the quarter, supporting manufacturing performance and customer deliveries. However, the business continued to weigh on consolidated profitability.
Management said it remained focused on achieving a financial turnaround in the US through restructuring and improvements in production and operating metrics. The initiatives are aimed at improving sales, cost competitiveness and overall execution.
Sundaram-Clayton is an automotive components manufacturer specialising in aluminium die-cast products. Its components are used across commercial vehicles, passenger vehicles and other industrial applications, with operations serving customers in India and overseas.