What is the story about?
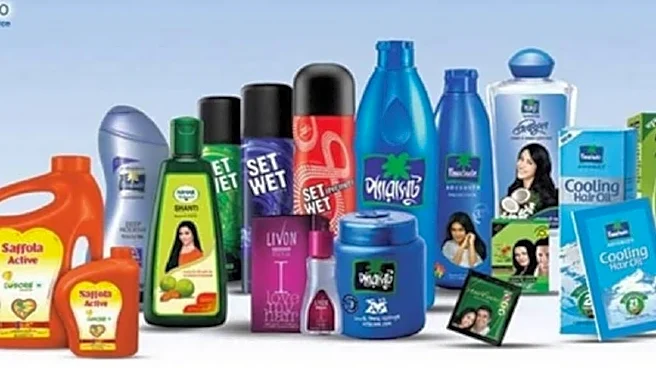
Shares of Marico Ltd. gained over 6.5% on Tuesday, November 3, as global investment banking firms were largely positive on the consumer goods company, after its strong second quarter earnings, indicating a potential upside of up to 35% from its previous close.
HSBC, Jefferies, Goldman Sachs and JPMorgan have maintained their "buy" recommendations on the stock, while CLSA has upgraded it to "hold" from its earlier rating of "reduce.'
HSBC has a "buy" recommendation on Marico with a target price of ₹1,080 per share. This indicates an upside of 35.2% from its previous close.
It said the second quarter results were in-line with estimates with 27% earnings before interest, taxes, depreciation and amortisation (EBITDA) growth and the outlook for the financial year 2027 raised to mid-20s.
The EBITDA growth is among the highest in HSBC's coverage.
It said the foods and premium personal care segments continue to scale up. The company now has a ₹20,000 crore revenue ambition for FY29 from FY30 earlier.
It added that the company's growth performance and diversification push call for a re-rating.
Jefferies has a "buy" rating and a target price of ₹1,035 per share. This indicates an upside of 29.6% from its previous closing price.
It said the company's compounding flywheel continues, with volume and EBITDA growth at multi-year highs.
Marico's core portfolio of Parachute and value-added hair (VAHO) segment grew strongly, further supported by robust performance in foods and PPC.
Jefferies said that at a time when Marico's peers are seeing patchy trends, the company clearly stands out as a compounding machine, as reflected in its premium valuation relative to peers.
CLSA has upgraded Marico to "hold" from "reduce" and has a target price of ₹737 per share on it. This indicates a downside of 7.7% from its previous closing price.
It said Marico's 27% EBITDA growth was 3% below estimates. The company's domestic volume growth came in at 10%, with 13% volume growth in parachute, though the value growth for Parachute was 1%.
Marico has lifted its guidance for EBITDA growth to mid-twenties for FY27, from nearly 20% earlier, driven by visibility on costs due to procurement benefits, strong execuction in general trade (GT) transformation via project SETU and improving profitability of growth business, CLSA said.
Marico expects to comfortably cross ₹15,000 crore sales in FY27, it added.
It has an "overweight" rating on Marico with a target price of ₹940 per share. This indicates an upside of 17.7% from its previous closing price.
It said the company reported another strong operational quarter with the revenue rising 13%, EBITDA up 27% and profit after tax rising 29% from last year.
Marico's India volumes were up 10% led by Parachute, which reported a 13% growth - highest in 22 quarters and mid/premium VAHO (mid-teens), while foods/PPC and digital brands continued to scale up with improving profitability.
The company's international growth was healthy at 13% despite soft trends in Bangladesh, though the company expects gradual recovery in the second half of FY27. JPMorgan said.
It sees a combination of sustained volumes, a better portfolio mix and lower copra costs as the key positives, allowing robust EBITDA expansion despite higher brand investments,
Better visibility on consumption costs and growth led the company to raise its FY27 EBITDA growth guidance again to mid-twenties, 24%-25% minimum compared to the previous 20%.
It has a "buy" rating and a target price of ₹950 per share. This indicates an upside of 18.9% from its previous closing price.
It said the company's strong volume growth sustained in double digits, Parachute grew 13% from last year, its VAHO business sustained strong growth, while the Saffola edible oil reset continues.
Of the 44 analysts who have coverage on the Marico stock, 36 have "buy" recommendations, seven have "hold" ratings and one has a "sell" rating.
Shares of Marico are currently trading 6% higher on Tuesday after the results announcement at ₹846.
Also Read: Here are five pharma and healthcare stocks that will be reacting to their Q2 results today
HSBC, Jefferies, Goldman Sachs and JPMorgan have maintained their "buy" recommendations on the stock, while CLSA has upgraded it to "hold" from its earlier rating of "reduce.'
HSBC Remains Bullish On Marico
HSBC has a "buy" recommendation on Marico with a target price of ₹1,080 per share. This indicates an upside of 35.2% from its previous close.
It said the second quarter results were in-line with estimates with 27% earnings before interest, taxes, depreciation and amortisation (EBITDA) growth and the outlook for the financial year 2027 raised to mid-20s.
The EBITDA growth is among the highest in HSBC's coverage.
It said the foods and premium personal care segments continue to scale up. The company now has a ₹20,000 crore revenue ambition for FY29 from FY30 earlier.
It added that the company's growth performance and diversification push call for a re-rating.
Jefferies Sees Close to 30% Upside
Jefferies has a "buy" rating and a target price of ₹1,035 per share. This indicates an upside of 29.6% from its previous closing price.
It said the company's compounding flywheel continues, with volume and EBITDA growth at multi-year highs.
Marico's core portfolio of Parachute and value-added hair (VAHO) segment grew strongly, further supported by robust performance in foods and PPC.
Jefferies said that at a time when Marico's peers are seeing patchy trends, the company clearly stands out as a compounding machine, as reflected in its premium valuation relative to peers.
CLSA Upgrades Marico
CLSA has upgraded Marico to "hold" from "reduce" and has a target price of ₹737 per share on it. This indicates a downside of 7.7% from its previous closing price.
It said Marico's 27% EBITDA growth was 3% below estimates. The company's domestic volume growth came in at 10%, with 13% volume growth in parachute, though the value growth for Parachute was 1%.
Marico has lifted its guidance for EBITDA growth to mid-twenties for FY27, from nearly 20% earlier, driven by visibility on costs due to procurement benefits, strong execuction in general trade (GT) transformation via project SETU and improving profitability of growth business, CLSA said.
Marico expects to comfortably cross ₹15,000 crore sales in FY27, it added.
JPMorgan Sees 17% Upside On Marico
It has an "overweight" rating on Marico with a target price of ₹940 per share. This indicates an upside of 17.7% from its previous closing price.
It said the company reported another strong operational quarter with the revenue rising 13%, EBITDA up 27% and profit after tax rising 29% from last year.
Marico's India volumes were up 10% led by Parachute, which reported a 13% growth - highest in 22 quarters and mid/premium VAHO (mid-teens), while foods/PPC and digital brands continued to scale up with improving profitability.
The company's international growth was healthy at 13% despite soft trends in Bangladesh, though the company expects gradual recovery in the second half of FY27. JPMorgan said.
It sees a combination of sustained volumes, a better portfolio mix and lower copra costs as the key positives, allowing robust EBITDA expansion despite higher brand investments,
Better visibility on consumption costs and growth led the company to raise its FY27 EBITDA growth guidance again to mid-twenties, 24%-25% minimum compared to the previous 20%.
Goldman Sachs Says "buy" Marico
It has a "buy" rating and a target price of ₹950 per share. This indicates an upside of 18.9% from its previous closing price.
It said the company's strong volume growth sustained in double digits, Parachute grew 13% from last year, its VAHO business sustained strong growth, while the Saffola edible oil reset continues.
Marico Shares Are A Buy Or Sell?
Of the 44 analysts who have coverage on the Marico stock, 36 have "buy" recommendations, seven have "hold" ratings and one has a "sell" rating.
Shares of Marico are currently trading 6% higher on Tuesday after the results announcement at ₹846.
Also Read: Here are five pharma and healthcare stocks that will be reacting to their Q2 results today