What is the story about?
The public stand-off between the Tata Sons board and Tata Trusts has raised a fundamental question over who has the final say in running the holding company — particularly over the reappointment of N Chandrasekaran as chairman and the proposed listing of Tata Sons.
Tata Group stocks have lost ₹42,000 crore in market capitalisation amid the dispute. TCS accounted for more than ₹30,000 crore of the decline, while Tata Chemicals fell 10%. Shares of other Tata Group companies, including Tata Motors and Tata Technologies, also fell sharply.
At the centre of the dispute is the decision to reappoint N Chandrasekaran, or Chandra, as Tata Sons chairman for another five years. Tata Trusts, led by Noel Tata, has opposed the move. Noel Tata has called the decision "illegal" and said his veto was "wrongfully over-ridden".
But the legal question is more complicated: can a nominee director appointed on behalf of the Tata Trusts act independently of the Trusts, and does a disagreement between nominee directors allow the Tata Sons board to proceed with Chandra's reappointment?
Speaking to CNBC-TV18, Senior Advocates Sanjay Hegde and Vaibhav Gaggar offered different interpretations of the Articles of Association of Tata Sons and the powers of its board and shareholders.
Can Tata Trusts veto Chandra’s reappointment?
Gaggar’s reading centres on Articles 104, 118 and 121 of the Articles of Association of Tata Sons.
According to him, two nominee directors come into play when the Sir Ratan Tata Trust and the Dorabji Trust are both in a position to appoint their nominees. The issue becomes more complicated if the two nominee directors do not take the same position.
The Articles refer to an affirmative vote by the two nominee directors. Gaggar said the question is what happens if they do not act jointly.
“If they don’t jointly take it, right? So, those are matters of interpretation which are going to go into court,” he said.
Gaggar also pointed to the chairman’s casting vote. His reading is that this provision could become relevant if the two nominee directors disagree.
One interpretation, therefore, is that a disagreement between the nominees creates a situation in which the chairman’s casting vote can come into play. The competing view is that the absence of a joint affirmative vote itself could prevent the board from proceeding.
Why Hegde and Gaggar disagree
Hegde’s interpretation starts with the role of a nominee director.
According to him, when a director is nominated by a significant shareholder, that director is expected to act in line with the shareholder’s wishes. He rejected the idea that such a director automatically becomes independent of the shareholder after joining the board.
“I would think that if you are nominated as a director on behalf of a significant shareholder, then you would be bound by that particular shareholder’s instructions,” Hegde said.
That interpretation has a direct bearing on Chandra’s reappointment.
Asked whether the reappointment was legal or illegal, Hegde said it “runs in the face of the Articles of Association”.
“A company moves according to its Articles of Association. How do you get over the block in the Articles of Association?” he said.
Hegde added that if he were on the Company Law Tribunal, he would find it difficult to uphold the reappointment.
Gaggar disagreed. His preliminary reading is that the board had the right to proceed with the appointment, particularly because the two nominee directors disagreed.
For Gaggar, however, the issue does not end with the board’s decision. Chandra’s reappointment still has to go through the shareholder approval process at the AGM.
What happens at the AGM?
This is where Tata Trusts’ shareholding becomes important.
Gaggar referred to Tata Trusts’ roughly 66% shareholding in Tata Sons. But he also pointed to a question over whether the Ratan Tata Trust can vote as a shareholder because it cannot currently hold board meetings.
That could create another legal hurdle before the AGM.
Hegde said there could be litigation seeking to have the Charity Commissioner lift or alter the restriction so that the Trust can participate in the voting process.
His broader argument is that a large shareholder cannot simply be prevented from having a say in the company’s affairs.
“Ultimately, it is a shareholder democracy,” Hegde said. “If you have over 60% of the company, then you are entitled to a very significant say in its affairs.”
That means Chandra’s reappointment could face another test even after the board-level decision — this time through the shareholder approval process.
What does this mean for the Tata Sons listing?
The dispute over Chandra’s reappointment is running alongside another major issue: whether Tata Sons should go public.
Tata Trusts, led by Noel Tata, has argued for keeping Tata Sons private, saying it is a philanthropic institution and would lose its character through the public accountability associated with a listing.
The position comes after the RBI rejected Tata Sons’ request for an exemption from going public.
Gaggar said the board could prevail on the listing issue if its current composition remains unchanged. But he also pointed to the RBI’s direction.
Tata Sons had said it was willing to revoke its upper-layer NBFC licence, a position that was rejected by the RBI. According to Gaggar, that direction would also need to be challenged.
“The interplay of the board, the interpretation of the powers of the board, and the constitution of the board is going to be pivotal in this entire decision-making process,” he said.
At the same time, Gaggar acknowledged that Tata Trusts’ substantial shareholding could not simply be discounted.
Where does the SP Group fit in?
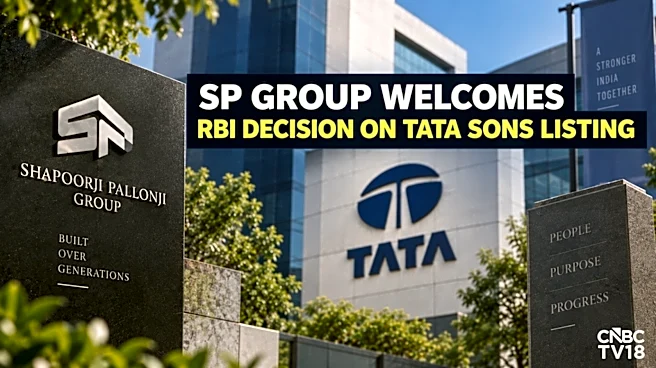
The Shapoorji Pallonji Group, the second-largest shareholder in Tata Sons, has backed a listing.
SP Group has argued that an IPO would provide greater liquidity and flexibility. Its position comes as Noel Tata has proposed buying the group’s Tata Sons shares for ₹25,000 crore using internal accruals.
That brings another question into the dispute: can a minority shareholder prevail over a majority shareholder?
Gaggar said it was possible, depending on the corporate-law provisions involved, for both sides to protect their interests.
He said there are ways for a majority to take total control if a minority is blocking it, while there are also ways for minority shareholders to prevent themselves from being “trampled upon or rolled over”.
“There can be a takeover mandatorily, and there could also be a way for the minority shareholders to block it,” Gaggar said.
Hegde, however, said the minority could not prevail on its own in a group of Tata Sons’ size.
“It happens occasionally, but in such a large group, with such large amounts, it can’t. Ultimately, it can’t. The minority group on its own cannot,” he said.
Hegde then pointed to what he sees as another important factor: the minority group appears to have the support of regulators and “the powers that really matter in this country”.
What are the key issues ahead?
The Tata Sons dispute now turns on several interconnected questions.
The first is how Articles 104, 118 and 121 of the Articles of Association should be interpreted, particularly where the two nominee directors do not agree.
The second is whether a nominee director appointed on behalf of a significant shareholder is bound by that shareholder’s position.
The third is whether the board’s decision to reappoint Chandra can survive the shareholder approval process at the AGM, given Tata Trusts’ substantial shareholding and the question surrounding the Ratan Tata Trust’s ability to vote.
And the fourth is the listing issue, where the powers of the board, Tata Trusts’ shareholding, the SP Group’s position and the RBI’s direction all intersect.
Hegde and Gaggar therefore arrive at different preliminary readings of the same corporate dispute. Hegde believes the reappointment runs against the Articles of Association, while Gaggar believes the board had a basis to proceed when the nominee directors disagreed.
The immediate legal question, therefore, is whether the Articles allowed the board to proceed despite the disagreement among the nominee directors. The answer could determine what happens next — at the AGM and potentially in court.
Tata Group stocks have lost ₹42,000 crore in market capitalisation amid the dispute. TCS accounted for more than ₹30,000 crore of the decline, while Tata Chemicals fell 10%. Shares of other Tata Group companies, including Tata Motors and Tata Technologies, also fell sharply.
At the centre of the dispute is the decision to reappoint N Chandrasekaran, or Chandra, as Tata Sons chairman for another five years. Tata Trusts, led by Noel Tata, has opposed the move. Noel Tata has called the decision "illegal" and said his veto was "wrongfully over-ridden".
But the legal question is more complicated: can a nominee director appointed on behalf of the Tata Trusts act independently of the Trusts, and does a disagreement between nominee directors allow the Tata Sons board to proceed with Chandra's reappointment?
Speaking to CNBC-TV18, Senior Advocates Sanjay Hegde and Vaibhav Gaggar offered different interpretations of the Articles of Association of Tata Sons and the powers of its board and shareholders.
Can Tata Trusts veto Chandra’s reappointment?
Gaggar’s reading centres on Articles 104, 118 and 121 of the Articles of Association of Tata Sons.
According to him, two nominee directors come into play when the Sir Ratan Tata Trust and the Dorabji Trust are both in a position to appoint their nominees. The issue becomes more complicated if the two nominee directors do not take the same position.
The Articles refer to an affirmative vote by the two nominee directors. Gaggar said the question is what happens if they do not act jointly.
“If they don’t jointly take it, right? So, those are matters of interpretation which are going to go into court,” he said.
Gaggar also pointed to the chairman’s casting vote. His reading is that this provision could become relevant if the two nominee directors disagree.
One interpretation, therefore, is that a disagreement between the nominees creates a situation in which the chairman’s casting vote can come into play. The competing view is that the absence of a joint affirmative vote itself could prevent the board from proceeding.
Why Hegde and Gaggar disagree
Hegde’s interpretation starts with the role of a nominee director.
According to him, when a director is nominated by a significant shareholder, that director is expected to act in line with the shareholder’s wishes. He rejected the idea that such a director automatically becomes independent of the shareholder after joining the board.
“I would think that if you are nominated as a director on behalf of a significant shareholder, then you would be bound by that particular shareholder’s instructions,” Hegde said.
That interpretation has a direct bearing on Chandra’s reappointment.
Asked whether the reappointment was legal or illegal, Hegde said it “runs in the face of the Articles of Association”.
“A company moves according to its Articles of Association. How do you get over the block in the Articles of Association?” he said.
Hegde added that if he were on the Company Law Tribunal, he would find it difficult to uphold the reappointment.
Gaggar disagreed. His preliminary reading is that the board had the right to proceed with the appointment, particularly because the two nominee directors disagreed.
For Gaggar, however, the issue does not end with the board’s decision. Chandra’s reappointment still has to go through the shareholder approval process at the AGM.
What happens at the AGM?
This is where Tata Trusts’ shareholding becomes important.
Gaggar referred to Tata Trusts’ roughly 66% shareholding in Tata Sons. But he also pointed to a question over whether the Ratan Tata Trust can vote as a shareholder because it cannot currently hold board meetings.
That could create another legal hurdle before the AGM.
Hegde said there could be litigation seeking to have the Charity Commissioner lift or alter the restriction so that the Trust can participate in the voting process.
His broader argument is that a large shareholder cannot simply be prevented from having a say in the company’s affairs.
“Ultimately, it is a shareholder democracy,” Hegde said. “If you have over 60% of the company, then you are entitled to a very significant say in its affairs.”
That means Chandra’s reappointment could face another test even after the board-level decision — this time through the shareholder approval process.
What does this mean for the Tata Sons listing?
The dispute over Chandra’s reappointment is running alongside another major issue: whether Tata Sons should go public.
Tata Trusts, led by Noel Tata, has argued for keeping Tata Sons private, saying it is a philanthropic institution and would lose its character through the public accountability associated with a listing.
The position comes after the RBI rejected Tata Sons’ request for an exemption from going public.
Gaggar said the board could prevail on the listing issue if its current composition remains unchanged. But he also pointed to the RBI’s direction.
Tata Sons had said it was willing to revoke its upper-layer NBFC licence, a position that was rejected by the RBI. According to Gaggar, that direction would also need to be challenged.
“The interplay of the board, the interpretation of the powers of the board, and the constitution of the board is going to be pivotal in this entire decision-making process,” he said.
At the same time, Gaggar acknowledged that Tata Trusts’ substantial shareholding could not simply be discounted.
Where does the SP Group fit in?
The Shapoorji Pallonji Group, the second-largest shareholder in Tata Sons, has backed a listing.
SP Group has argued that an IPO would provide greater liquidity and flexibility. Its position comes as Noel Tata has proposed buying the group’s Tata Sons shares for ₹25,000 crore using internal accruals.
That brings another question into the dispute: can a minority shareholder prevail over a majority shareholder?
Gaggar said it was possible, depending on the corporate-law provisions involved, for both sides to protect their interests.
He said there are ways for a majority to take total control if a minority is blocking it, while there are also ways for minority shareholders to prevent themselves from being “trampled upon or rolled over”.
“There can be a takeover mandatorily, and there could also be a way for the minority shareholders to block it,” Gaggar said.
Hegde, however, said the minority could not prevail on its own in a group of Tata Sons’ size.
“It happens occasionally, but in such a large group, with such large amounts, it can’t. Ultimately, it can’t. The minority group on its own cannot,” he said.
Hegde then pointed to what he sees as another important factor: the minority group appears to have the support of regulators and “the powers that really matter in this country”.
What are the key issues ahead?
The Tata Sons dispute now turns on several interconnected questions.
The first is how Articles 104, 118 and 121 of the Articles of Association should be interpreted, particularly where the two nominee directors do not agree.
The second is whether a nominee director appointed on behalf of a significant shareholder is bound by that shareholder’s position.
The third is whether the board’s decision to reappoint Chandra can survive the shareholder approval process at the AGM, given Tata Trusts’ substantial shareholding and the question surrounding the Ratan Tata Trust’s ability to vote.
And the fourth is the listing issue, where the powers of the board, Tata Trusts’ shareholding, the SP Group’s position and the RBI’s direction all intersect.
Hegde and Gaggar therefore arrive at different preliminary readings of the same corporate dispute. Hegde believes the reappointment runs against the Articles of Association, while Gaggar believes the board had a basis to proceed when the nominee directors disagreed.
The immediate legal question, therefore, is whether the Articles allowed the board to proceed despite the disagreement among the nominee directors. The answer could determine what happens next — at the AGM and potentially in court.