What is the story about?
Shares of Symbiotec Pharmalab Ltd. gained on Monday, October 26, after brokerage firm Motilal Oswal initiated coverage on the stock indicating an upside of 23%.
The brokerage has initiated a "buy" rating with a target price of ₹1,430 per share.
Motilal Oswal said Symbiotec Pharmalab has evolved from a steroidal active pharmaceutical ingredient (API) manufacturer into an integrated platform spanning API fermentation-led CDMO, and complex injectables, backed by manufacturing investments and backward integration.
It said the company is a leading corticosteroid/hormone API supplier, with a total addressable market (TAM) of $800 million, and is expanding into fermentation-based and high-value complex APIs having TAM of $92 billion and 10.4% compound annual growth rate (CAGR) over the calendar years 2024-2029.
Motilal Oswal said the company is already on a path to provide chemistry and fermentation-based capabilities and capacities as a CDMO platform in precision fermentation, industrial biotechnology and biologics, targeting a TAM of $50 billion. It has invested in building a manufacturing facility to forward integrate into double chamber vials, which not only enables better profitability but also enhances traction in the most heavily regulated market (the US).
Its long-standing customer relationships, regulatory capabilities and contracted business support growth visibility, commercialization of new capacities and higher utilization remain the key execution drivers, the brokerage said.
Symbiotec Pharmalab posted a revenue, EBITDA, PAT CAGR of 15%, 51% and 69% reaching ₹870 crore, ₹240 crore and ₹110 crore, respectively, over FY23-26, Motilal Oswal said.
Motilal Oswal expects the company's revenue to grow at a 33% CAGR to ₹2,030 crore, EBITDA to also grow at a 33% CAGR to ₹560 crore, and PAT to grow to ₹300 crore over financial year 2026-2029, led by new product launches, scale up of CDMO & injectable operations, and operating leverage.
It values the stock at 35 times its 12-month forward earnings to arrive at its target price, factoring in the company's established API base and earnings potential from the newer businesses.
In a bull-case scenario, Motilal Oswal has a target price of ₹1,690 per share on the stock, an upside of 45%.
It assumes a 12-month forward earnings per share (EPS) of ₹44.5 and assigns a 38x price-to-earnings multiple.
The bull case factors in faster earnings growth, driven by accelerated commercialization of new API and fermentation capacities, stronger traction in CDMO contracts, faster scale-up of complex injectables and improved operating leverage.
In a bear-case scenario, the brokerage has a target price of ₹1,000 per share.
It assumes a 12-month forward EPS of ₹32.5 and assigns a lower 31x price-to-earnings multiple.
The bear case factors in delayed commercialization of new capacities, slower ramp-up of CDMO and complex injectables, weaker-than-expected API growth, and higher operating costs affecting profitability.
Motilal Oswal lists the following as key risks for the stock:
Stock reaction
Apart of Motilal Oswal, ICICI Direct is the only other analyst that has coverage on the stock, with a "buy" rating and target price of ₹1,540 per share, indicating an upside 32.3% from its previous closing price.
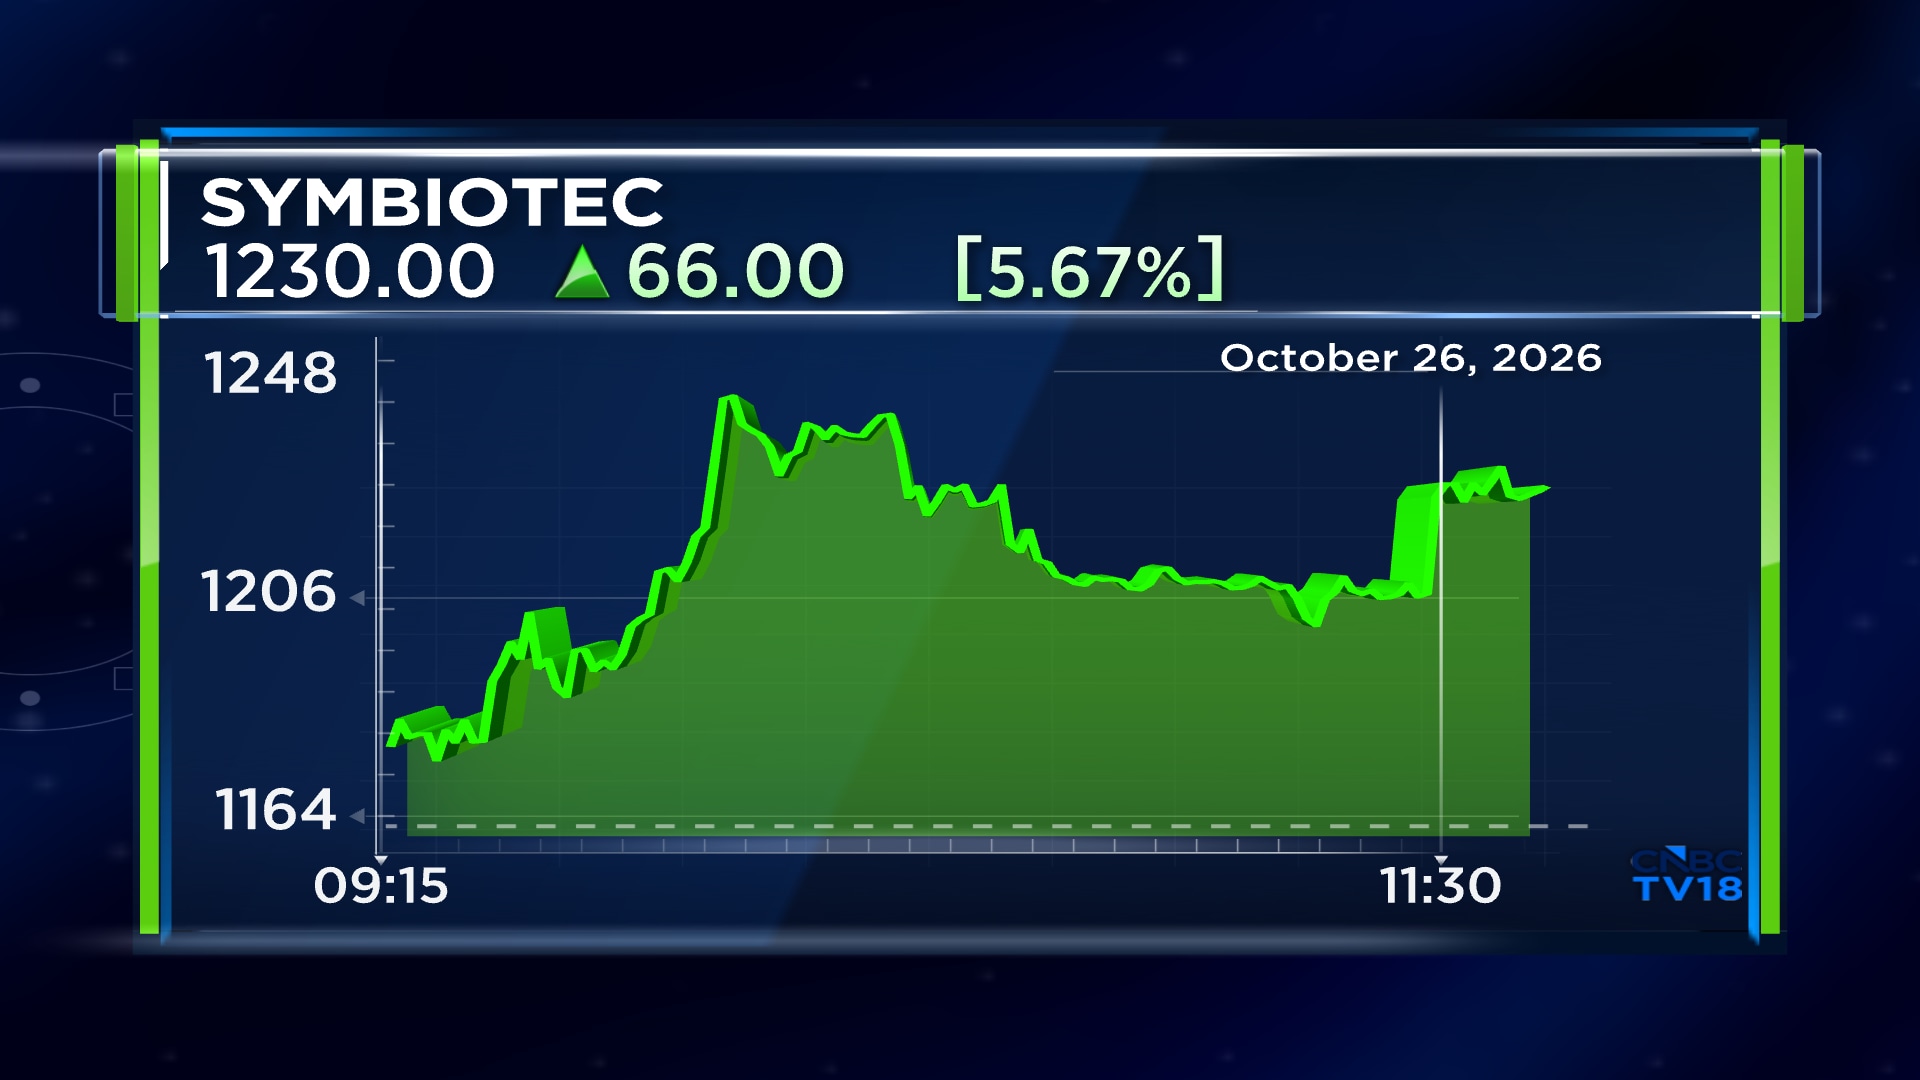
Shares of Symbiotec Pharmalab gained 7.4% to hit an intraday high of ₹1,250.1 apiece on Monday. The stock is currently trading 4.6% higher at ₹1,218.1. The stocks is up 23% from its issue price of ₹988.
Also Read: Apollo Micro shares jump 9% after reiterating growth guidance, exports upside on Q2 results
The brokerage has initiated a "buy" rating with a target price of ₹1,430 per share.
Motilal Oswal said Symbiotec Pharmalab has evolved from a steroidal active pharmaceutical ingredient (API) manufacturer into an integrated platform spanning API fermentation-led CDMO, and complex injectables, backed by manufacturing investments and backward integration.
It said the company is a leading corticosteroid/hormone API supplier, with a total addressable market (TAM) of $800 million, and is expanding into fermentation-based and high-value complex APIs having TAM of $92 billion and 10.4% compound annual growth rate (CAGR) over the calendar years 2024-2029.
Motilal Oswal said the company is already on a path to provide chemistry and fermentation-based capabilities and capacities as a CDMO platform in precision fermentation, industrial biotechnology and biologics, targeting a TAM of $50 billion. It has invested in building a manufacturing facility to forward integrate into double chamber vials, which not only enables better profitability but also enhances traction in the most heavily regulated market (the US).
Its long-standing customer relationships, regulatory capabilities and contracted business support growth visibility, commercialization of new capacities and higher utilization remain the key execution drivers, the brokerage said.
Symbiotec Pharmalab posted a revenue, EBITDA, PAT CAGR of 15%, 51% and 69% reaching ₹870 crore, ₹240 crore and ₹110 crore, respectively, over FY23-26, Motilal Oswal said.
Motilal Oswal expects the company's revenue to grow at a 33% CAGR to ₹2,030 crore, EBITDA to also grow at a 33% CAGR to ₹560 crore, and PAT to grow to ₹300 crore over financial year 2026-2029, led by new product launches, scale up of CDMO & injectable operations, and operating leverage.
It values the stock at 35 times its 12-month forward earnings to arrive at its target price, factoring in the company's established API base and earnings potential from the newer businesses.
Motilal Oswal Bull Case Projects 45% Upside
In a bull-case scenario, Motilal Oswal has a target price of ₹1,690 per share on the stock, an upside of 45%.
It assumes a 12-month forward earnings per share (EPS) of ₹44.5 and assigns a 38x price-to-earnings multiple.
The bull case factors in faster earnings growth, driven by accelerated commercialization of new API and fermentation capacities, stronger traction in CDMO contracts, faster scale-up of complex injectables and improved operating leverage.
Bear Case Scenario Sees Significant Downside
In a bear-case scenario, the brokerage has a target price of ₹1,000 per share.
It assumes a 12-month forward EPS of ₹32.5 and assigns a lower 31x price-to-earnings multiple.
The bear case factors in delayed commercialization of new capacities, slower ramp-up of CDMO and complex injectables, weaker-than-expected API growth, and higher operating costs affecting profitability.
What Are The Key Risks For Symbiotec Pharmalabs?
Motilal Oswal lists the following as key risks for the stock:
- High dependence on APIs and a concentrated product portfolio.
- Delays in scaling CDMO, biologics, complex injectables.
- Geogaphical concentration of manufacturing facilities.
- Intensifying competition.
Stock reaction
Apart of Motilal Oswal, ICICI Direct is the only other analyst that has coverage on the stock, with a "buy" rating and target price of ₹1,540 per share, indicating an upside 32.3% from its previous closing price.
Shares of Symbiotec Pharmalab gained 7.4% to hit an intraday high of ₹1,250.1 apiece on Monday. The stock is currently trading 4.6% higher at ₹1,218.1. The stocks is up 23% from its issue price of ₹988.
Also Read: Apollo Micro shares jump 9% after reiterating growth guidance, exports upside on Q2 results