What is the story about?
Shares of Indian Oil Corporation (IOC) gained as much as 5% on Monday, November 2, after the state-run oil marketing company reported a sharp improvement in its September-quarter earnings, with net profit and operating profit significantly ahead of market estimates.
Strong refining performance, inventory gains and lower-than-expected fuel marketing losses and liquefied petroleum gas (LPG) under-recoveries supported the results.
IOC reported a standalone net profit of ₹21,630 crore for Q2 FY27 , compared with the CNBC-TV18 poll estimate of ₹4,062 crore. Earnings before interest, tax, depreciation and amortisation (EBITDA) stood at ₹30,297 crore, nearly three times the poll estimate of ₹10,194 crore. Revenue came in at ₹2.50 lakh crore, against the estimate of ₹2.42 lakh crore.
Sequentially, revenue declined 4.6% from ₹2.62 lakh crore in Q1 FY27. However, EBITDA surged to ₹30,297 crore from ₹1,947 crore, while EBITDA margin expanded to 12% from 0.7%. The company reported a net loss of ₹2,661 crore in the June quarter.
IOC's refining throughput stood at 18.1 million tonnes in Q2 FY27, up 3% year-on-year. Marketing sales increased 4% to 25.2 million tonnes during the quarter.
Nomura maintained its ‘Buy’ rating on IOC, saying strong gross refining margins (GRMs) and inventory gains drove the second-quarter earnings beat.
Its target price of ₹185 implies an upside of 42.2% from IOC’s Friday closing price of ₹130.15.
The global investment firm said the beat was largely attributable to inventory gains of ₹6,950 crore, along with lower-than-estimated fuel marketing losses and LPG under-recoveries during the quarter.
Nomura estimated refining GRM at $36.7 per barrel, compared with its estimate of $38 per barrel. IOC has not separately reported its GRM for the quarter. The reported net profit of ₹21,600 crore was significantly ahead of Nomura’s estimate of ₹7,500 crore and the consensus estimate of ₹5,900 crore.
It believes IOC stands to benefit the most among oil marketing companies (OMCs) from the ongoing refining upcycle. However, it expects capital expenditure intensity to remain high due to investments in petrochemicals and renewable energy expansion, while leverage is expected to remain comfortable.
Bloomberg's analyst recommendation data shows a consensus rating of 3.81 for IOC. Of 32 analyst recommendations, 21 are ‘Buy’, five are ‘Hold ’, and six are ‘Sell’.
The stock's 12-month consensus target price is ₹159.20, against a last price of ₹130.15, indicating a potential return of 22.3%.
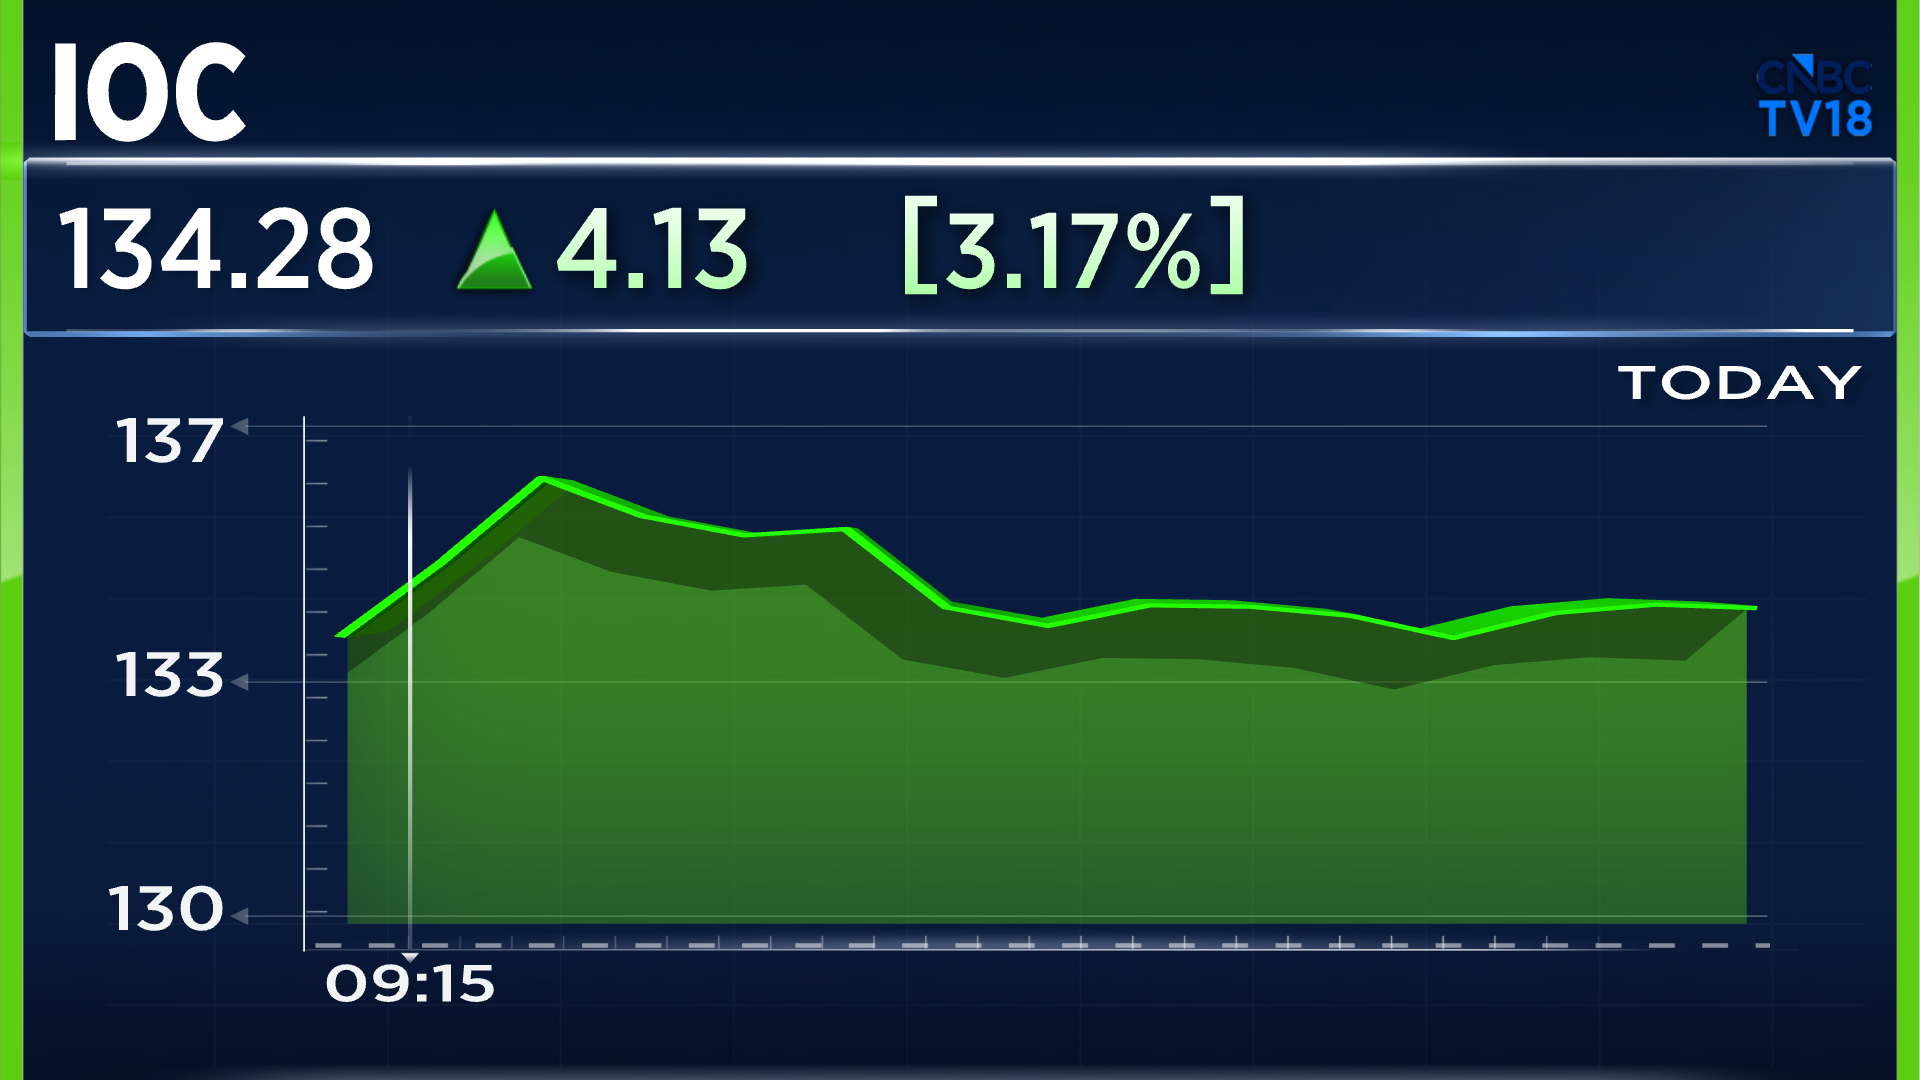
Shares of IOC rose up to 4.8% to an intraday high of ₹136.40 on Monday, in reaction to the results announcement on Friday. The stock was trading 2.8% up at ₹133.80 as of 9.25 am. It has declined more than 20% over the last 12 months.
Strong refining performance, inventory gains and lower-than-expected fuel marketing losses and liquefied petroleum gas (LPG) under-recoveries supported the results.
IOC reported a standalone net profit of ₹21,630 crore for Q2 FY27 , compared with the CNBC-TV18 poll estimate of ₹4,062 crore. Earnings before interest, tax, depreciation and amortisation (EBITDA) stood at ₹30,297 crore, nearly three times the poll estimate of ₹10,194 crore. Revenue came in at ₹2.50 lakh crore, against the estimate of ₹2.42 lakh crore.
Sequentially, revenue declined 4.6% from ₹2.62 lakh crore in Q1 FY27. However, EBITDA surged to ₹30,297 crore from ₹1,947 crore, while EBITDA margin expanded to 12% from 0.7%. The company reported a net loss of ₹2,661 crore in the June quarter.
IOC's refining throughput stood at 18.1 million tonnes in Q2 FY27, up 3% year-on-year. Marketing sales increased 4% to 25.2 million tonnes during the quarter.
Nomura on IOC: Buy, target price ₹185
Nomura maintained its ‘Buy’ rating on IOC, saying strong gross refining margins (GRMs) and inventory gains drove the second-quarter earnings beat.
Its target price of ₹185 implies an upside of 42.2% from IOC’s Friday closing price of ₹130.15.
The global investment firm said the beat was largely attributable to inventory gains of ₹6,950 crore, along with lower-than-estimated fuel marketing losses and LPG under-recoveries during the quarter.
Nomura estimated refining GRM at $36.7 per barrel, compared with its estimate of $38 per barrel. IOC has not separately reported its GRM for the quarter. The reported net profit of ₹21,600 crore was significantly ahead of Nomura’s estimate of ₹7,500 crore and the consensus estimate of ₹5,900 crore.
It believes IOC stands to benefit the most among oil marketing companies (OMCs) from the ongoing refining upcycle. However, it expects capital expenditure intensity to remain high due to investments in petrochemicals and renewable energy expansion, while leverage is expected to remain comfortable.
Analysts view and stock movement
Bloomberg's analyst recommendation data shows a consensus rating of 3.81 for IOC. Of 32 analyst recommendations, 21 are ‘Buy’, five are ‘Hold ’, and six are ‘Sell’.
The stock's 12-month consensus target price is ₹159.20, against a last price of ₹130.15, indicating a potential return of 22.3%.
Shares of IOC rose up to 4.8% to an intraday high of ₹136.40 on Monday, in reaction to the results announcement on Friday. The stock was trading 2.8% up at ₹133.80 as of 9.25 am. It has declined more than 20% over the last 12 months.