What is the story about?
Adyen is stepping up its India bet, seven years after establishing a presence in the country, with the global payments company continuing to focus on building more localised infrastructure and expanding its capabilities for businesses operating in and from India.
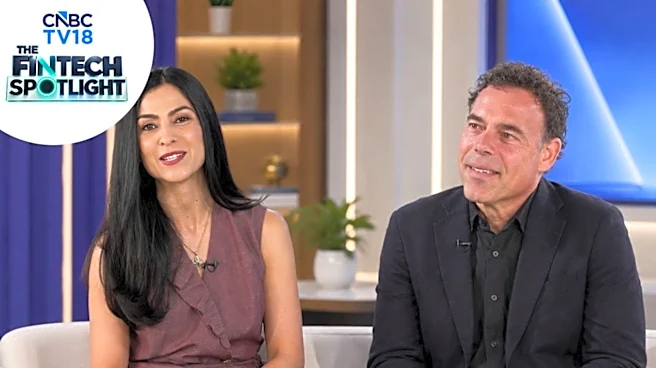
Speaking to CNBC-TV18 at the Global Fintech Fest (GFF) 2026 in Mumbai, Adyen’s Global Chief Commercial Officer Roelant Prins said India has become a strategic part of the company’s ambitions around global commerce, with the company taking a long-term approach to the market. “We’re very much building in India for India,” Prins said, pointing to investments across technology, product, account management and licensing.
Adyen entered India in 2018 and has since established a technology hub in Bengaluru and local payment-processing capabilities. The company’s local strategy gained further momentum as it received authorisation from the Reserve Bank of India in 2024 to operate as a payment aggregator for domestic and cross-border transactions. Its local acquiring solution went live in mid-2024, supporting payments in Indian rupees through UPI, RuPay, and international card networks.
The company’s India proposition is aimed at both global businesses entering the country and Indian companies looking to expand internationally. For Prins, the opportunity is closely linked to the evolution of India’s digital payments ecosystem.
UPI as a global blueprint
Prins said the company’s experience with UPI has offered a front-row view of the rapid transformation in India’s payments market. Having first observed the system taking shape in 2017-18, he described its subsequent development as incredible in the global payments landscape. "We haven’t seen anything like it," he said, calling UPI a potential global blueprint for real-time account-to-account payments.
For Adyen, supporting the Indian market therefore means going beyond simply plugging a local payment method into a global platform. The company has been integrating UPI and other domestic payment rails while building local capabilities around them.
That localisation is becoming increasingly important as the direction of commerce becomes more global in both directions, with international businesses entering India and Indian companies expanding overseas.
Prins said companies looking to enter new markets cannot simply take their domestic payments playbook with them. "Every country has its own specific ways that people pay," Prins said. "You cannot take your local playbook and simply apply it to the markets you are entering." Payment preferences, regulations and consumer behaviour vary significantly across markets, making local payment infrastructure an important part of international expansion, he added.
The next frontier: Agentic commerce
At GFF 2026, agentic commerce emerged as one of the next major shifts for the payments industry with AI systems increasingly able to search, make decisions and eventually transact on behalf of consumers.
Adyen launched its Adyen Agentic platform earlier this year in the US, describing it as an infrastructure layer designed to allow businesses to connect with emerging AI commerce platforms through a single integration. But Prins struck a measured tone on the pace of adoption.
Transactions carried out through agents remain small today, he said, even though the potential is significant. A future where machines interact with machines and initiate transactions could fundamentally change commerce, but the infrastructure required to make that happen is still being built.
The biggest issue, according to Prins, is not simply technology but trust. “Payments are all about trust,” he said, adding that agentic commerce will need to address questions around identity, fraud and whether an AI agent is acting within the consumer’s intent.
That concern is also becoming more immediate for the wider payments industry. Adyen’s own recent research on agentic-commerce fraud has highlighted that traditional fraud systems were designed around verifying human customers and their authority to transact, while AI agents introduce new questions around whether the agent itself is legitimate and whether it is acting within authorised boundaries.
A long-term India play
Beyond UPI and AI, Prins said Adyen’s broader strategy is centred on building financial infrastructure that can support the next phase of global commerce.
The group processed more than €803.8 billion in payments in the first six months of 2026, according to Prins, and is looking to build further capabilities around payments, banking functionality and data.
Prins said the company will continue investing in local infrastructure and teams, acknowledging that changing fundamental financial infrastructure takes time. "You need to be willing to take the long-term approach," he said.
And as India’s role in global commerce grows, Prins expects the market to become increasingly important to the international businesses it serves. For now, the company is preparing for that growth by expanding its local capabilities while simultaneously looking beyond today’s payment rails to what comes next.
At GFF 2026, that next chapter was increasingly defined by one question: as payments become more intelligent and increasingly autonomous, how will the industry build enough trust to let machines transact on our behalf?
Speaking to CNBC-TV18 at the Global Fintech Fest (GFF) 2026 in Mumbai, Adyen’s Global Chief Commercial Officer Roelant Prins said India has become a strategic part of the company’s ambitions around global commerce, with the company taking a long-term approach to the market. “We’re very much building in India for India,” Prins said, pointing to investments across technology, product, account management and licensing.
Adyen entered India in 2018 and has since established a technology hub in Bengaluru and local payment-processing capabilities. The company’s local strategy gained further momentum as it received authorisation from the Reserve Bank of India in 2024 to operate as a payment aggregator for domestic and cross-border transactions. Its local acquiring solution went live in mid-2024, supporting payments in Indian rupees through UPI, RuPay, and international card networks.
The company’s India proposition is aimed at both global businesses entering the country and Indian companies looking to expand internationally. For Prins, the opportunity is closely linked to the evolution of India’s digital payments ecosystem.
UPI as a global blueprint
Prins said the company’s experience with UPI has offered a front-row view of the rapid transformation in India’s payments market. Having first observed the system taking shape in 2017-18, he described its subsequent development as incredible in the global payments landscape. "We haven’t seen anything like it," he said, calling UPI a potential global blueprint for real-time account-to-account payments.
For Adyen, supporting the Indian market therefore means going beyond simply plugging a local payment method into a global platform. The company has been integrating UPI and other domestic payment rails while building local capabilities around them.
That localisation is becoming increasingly important as the direction of commerce becomes more global in both directions, with international businesses entering India and Indian companies expanding overseas.
Prins said companies looking to enter new markets cannot simply take their domestic payments playbook with them. "Every country has its own specific ways that people pay," Prins said. "You cannot take your local playbook and simply apply it to the markets you are entering." Payment preferences, regulations and consumer behaviour vary significantly across markets, making local payment infrastructure an important part of international expansion, he added.
The next frontier: Agentic commerce
At GFF 2026, agentic commerce emerged as one of the next major shifts for the payments industry with AI systems increasingly able to search, make decisions and eventually transact on behalf of consumers.
Adyen launched its Adyen Agentic platform earlier this year in the US, describing it as an infrastructure layer designed to allow businesses to connect with emerging AI commerce platforms through a single integration. But Prins struck a measured tone on the pace of adoption.
Transactions carried out through agents remain small today, he said, even though the potential is significant. A future where machines interact with machines and initiate transactions could fundamentally change commerce, but the infrastructure required to make that happen is still being built.
The biggest issue, according to Prins, is not simply technology but trust. “Payments are all about trust,” he said, adding that agentic commerce will need to address questions around identity, fraud and whether an AI agent is acting within the consumer’s intent.
That concern is also becoming more immediate for the wider payments industry. Adyen’s own recent research on agentic-commerce fraud has highlighted that traditional fraud systems were designed around verifying human customers and their authority to transact, while AI agents introduce new questions around whether the agent itself is legitimate and whether it is acting within authorised boundaries.
A long-term India play
Beyond UPI and AI, Prins said Adyen’s broader strategy is centred on building financial infrastructure that can support the next phase of global commerce.
The group processed more than €803.8 billion in payments in the first six months of 2026, according to Prins, and is looking to build further capabilities around payments, banking functionality and data.
Prins said the company will continue investing in local infrastructure and teams, acknowledging that changing fundamental financial infrastructure takes time. "You need to be willing to take the long-term approach," he said.
And as India’s role in global commerce grows, Prins expects the market to become increasingly important to the international businesses it serves. For now, the company is preparing for that growth by expanding its local capabilities while simultaneously looking beyond today’s payment rails to what comes next.
At GFF 2026, that next chapter was increasingly defined by one question: as payments become more intelligent and increasingly autonomous, how will the industry build enough trust to let machines transact on our behalf?