What is the story about?
Shares of GE Vernova T&D India Ltd. gain nearly 5% on Monday, November 2, after the company reported better-than-expected earnings in the second quarter.
Strong execution led to its revenue growth of 32% year-on-year during the September quarter. Better execution also aided its profitability. The company's EBITDA margin expansion was primarily led by gross margin expansion and operating leverage.
The company's profit after tax (PAT) increased 44.15% to ₹431 crore from ₹299 crore last year. It was also 11.7% higher than the CNBC-TV18 poll of ₹385.7 crore.
Revenue for the quarter stood at ₹2,027 crore, also marginally higher than the CNBC-TV18 poll of ₹1,970 crore
Earnings before interest, taxes, depreciation and amortization (EBITDA) increased 38.8% to ₹549.7 crore from ₹396 crore. A CNBC-TV18 poll had projected the figure to be ₹501 crore.
Its EBITDA margin expanded to 27.1% from 25.7% in the year-ago period, higher than the 25.4% poll expectation.
GE Vernova T&D's order inflow during the quarter stood at ₹2,440 crore compared to ₹1,140 crore in the previous year and ₹1,601 crore in the same quarter last year. This took the company's order backlog to ₹21,440 crore, compared to ₹20,930 crore earlier.
The company's management, in its post-earnings conference call, said it has maintained its FY27 EBITDA margin guidance of mid-20s. It also expects over 30% annual execution growth over the next three to four years on the back of the strong backlog and the Barmer HVDC order.
The management expects to book Power Grid's Barmer HVDC project in the third quarter of this fiscal.
It has also maintained its base order inflow target of ₹7,200 crore to ₹8,000 crore for FY27. It expects STATCOM and data centre orders to pick up from the fourth quarter.
The management said FY28 will see bidding for 2-3 HVDC projects. It added that exports accounted for 21% of its second quarter order inflows and 32% of its revenue.
Motilal Oswal has maintained its "buy" rating on GE Vernova T&D, and a price target of ₹5,100, indicating an upside potential of 27% from current levels, stating that the company's results were ahead of their estimates as well.
The brokerage expects domestic ordering to remain healthy and export orders from parent and non-parent entities to materialize in the coming quarters. It also expects revenue contribution from existing HDFC projects to commence mainly from financial year 2028 and 2029.
As a result, Motilal Oswal has marginally raised its estimates by 7% and 1% respectively for financial year 2027 and 2028, to factor in the performance of the first half.
Nomura has a "buy" recommendation and target price of ₹6,090 per share on the stock. This indicates an upside of 44.7% from its previous closing price of ₹4,210 apiece.
It said the second quarter was a significant beat on estimates in a relatively flawless quarter. It preferred play on grid expansions and digitalization story with estimated 30% earnings compound annual growth rate (CAGR) over FY26-29.
It has raised its estimated FY27-29 earnings per share (EPS) by 1-4%.
Nomura said GE Vernova's EBITDA grew 39% from last year, beating estimates by 13%.
It reported a robust operating income in the second quarter, and the first half of FY27's export OI was nearly as much as the FY26 one.
The management is aiming for a 30% revenue CAGR over the next three to four years, which is in-line with estimates.
Nomura said the stock currently trades at estimates of 47x and 36x for FY28 and FY29 EPS, respectively.
Citi has a "buy" rating and a target price of ₹5,400 per share, indicating an upside of 28.3% from its previous closing price.
It said the company delivered a strong second quarter, with order inflows of 2,440 crore, significantly ahead of estimates, driven by robust domestic ordering and strong export order growth.
It said the revenue of 2,030 crore was broadly in-line, while EBITDA margins surprised positively at 27.1%, expanding 200 basis points sequentially and coming 200 basis points ahead of estimates, due to favourable execution.
The management remains constructive on the second half's order inflows, supported by a strong tariff based competitive bidding (TCBC) tender pipeline, while remaining FY27 EBITDA margin guidance is of 25%.
The key monitorables are — sustainability of domestic order inflow momentum given the strong tender pipeline and export order traction amid the uncertain India-Us tariff environment.
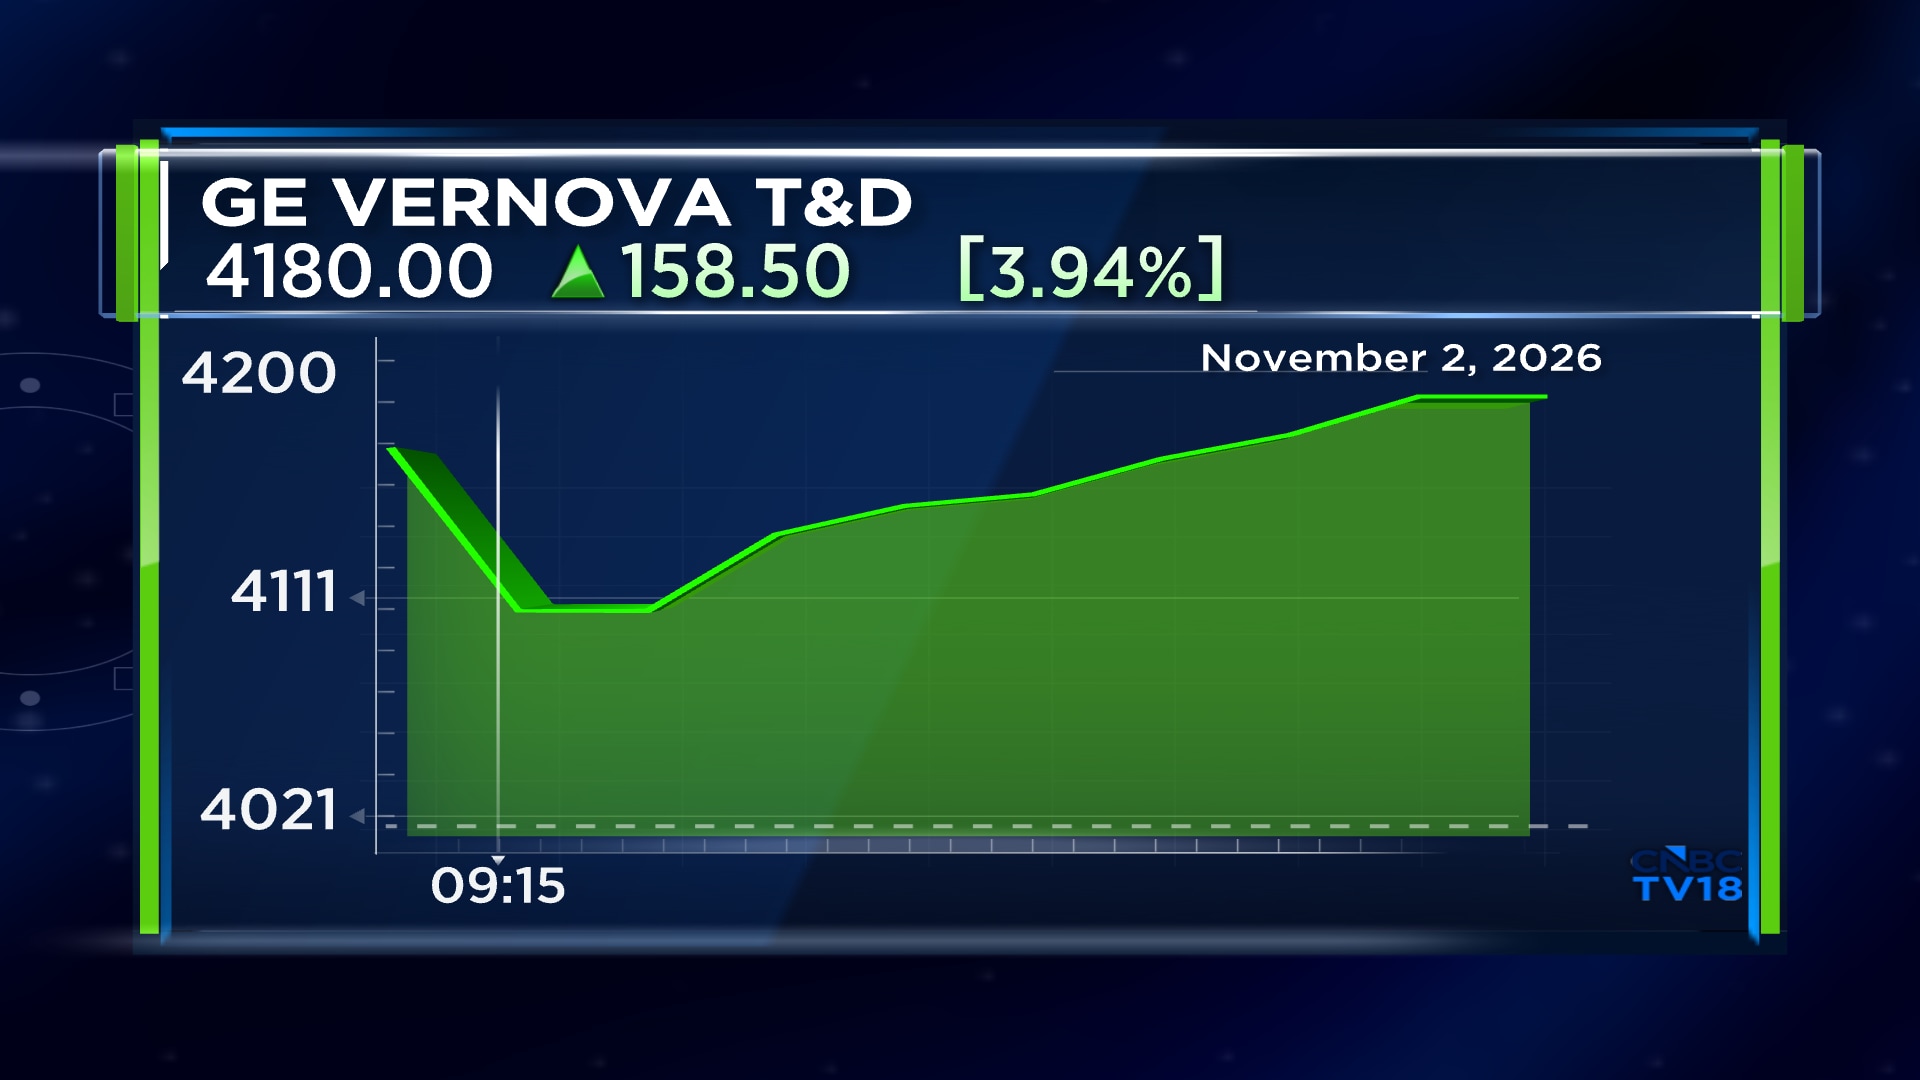
Shares of GE Vernova T&D India opened 5% up on Monday. The stock was up 3.9% at ₹4,175.4 apiece at 9.22 am. it has gained 31.7% this year, so far.
Also Read: Coal India October Business Update: Production and offtake rise nearly 19%
Strong execution led to its revenue growth of 32% year-on-year during the September quarter. Better execution also aided its profitability. The company's EBITDA margin expansion was primarily led by gross margin expansion and operating leverage.
The company's profit after tax (PAT) increased 44.15% to ₹431 crore from ₹299 crore last year. It was also 11.7% higher than the CNBC-TV18 poll of ₹385.7 crore.
Revenue for the quarter stood at ₹2,027 crore, also marginally higher than the CNBC-TV18 poll of ₹1,970 crore
Earnings before interest, taxes, depreciation and amortization (EBITDA) increased 38.8% to ₹549.7 crore from ₹396 crore. A CNBC-TV18 poll had projected the figure to be ₹501 crore.
Its EBITDA margin expanded to 27.1% from 25.7% in the year-ago period, higher than the 25.4% poll expectation.
GE Vernova T&D's order inflow during the quarter stood at ₹2,440 crore compared to ₹1,140 crore in the previous year and ₹1,601 crore in the same quarter last year. This took the company's order backlog to ₹21,440 crore, compared to ₹20,930 crore earlier.
The company's management, in its post-earnings conference call, said it has maintained its FY27 EBITDA margin guidance of mid-20s. It also expects over 30% annual execution growth over the next three to four years on the back of the strong backlog and the Barmer HVDC order.
The management expects to book Power Grid's Barmer HVDC project in the third quarter of this fiscal.
It has also maintained its base order inflow target of ₹7,200 crore to ₹8,000 crore for FY27. It expects STATCOM and data centre orders to pick up from the fourth quarter.
The management said FY28 will see bidding for 2-3 HVDC projects. It added that exports accounted for 21% of its second quarter order inflows and 32% of its revenue.
Motilal Oswal Sees 27% Upside For GE Vernova T&D
Motilal Oswal has maintained its "buy" rating on GE Vernova T&D, and a price target of ₹5,100, indicating an upside potential of 27% from current levels, stating that the company's results were ahead of their estimates as well.
The brokerage expects domestic ordering to remain healthy and export orders from parent and non-parent entities to materialize in the coming quarters. It also expects revenue contribution from existing HDFC projects to commence mainly from financial year 2028 and 2029.
As a result, Motilal Oswal has marginally raised its estimates by 7% and 1% respectively for financial year 2027 and 2028, to factor in the performance of the first half.
Nomura
Nomura has a "buy" recommendation and target price of ₹6,090 per share on the stock. This indicates an upside of 44.7% from its previous closing price of ₹4,210 apiece.
It said the second quarter was a significant beat on estimates in a relatively flawless quarter. It preferred play on grid expansions and digitalization story with estimated 30% earnings compound annual growth rate (CAGR) over FY26-29.
It has raised its estimated FY27-29 earnings per share (EPS) by 1-4%.
Nomura said GE Vernova's EBITDA grew 39% from last year, beating estimates by 13%.
It reported a robust operating income in the second quarter, and the first half of FY27's export OI was nearly as much as the FY26 one.
The management is aiming for a 30% revenue CAGR over the next three to four years, which is in-line with estimates.
Nomura said the stock currently trades at estimates of 47x and 36x for FY28 and FY29 EPS, respectively.
Citi
Citi has a "buy" rating and a target price of ₹5,400 per share, indicating an upside of 28.3% from its previous closing price.
It said the company delivered a strong second quarter, with order inflows of 2,440 crore, significantly ahead of estimates, driven by robust domestic ordering and strong export order growth.
It said the revenue of 2,030 crore was broadly in-line, while EBITDA margins surprised positively at 27.1%, expanding 200 basis points sequentially and coming 200 basis points ahead of estimates, due to favourable execution.
The management remains constructive on the second half's order inflows, supported by a strong tariff based competitive bidding (TCBC) tender pipeline, while remaining FY27 EBITDA margin guidance is of 25%.
The key monitorables are — sustainability of domestic order inflow momentum given the strong tender pipeline and export order traction amid the uncertain India-Us tariff environment.
Shares of GE Vernova T&D India opened 5% up on Monday. The stock was up 3.9% at ₹4,175.4 apiece at 9.22 am. it has gained 31.7% this year, so far.
Also Read: Coal India October Business Update: Production and offtake rise nearly 19%