What is the story about?
Indian companies have benefited from strong domestic growth for years, helping several businesses become large-cap companies. But many of these companies have not yet gained the kind of global relevance that could attract greater international investor interest.
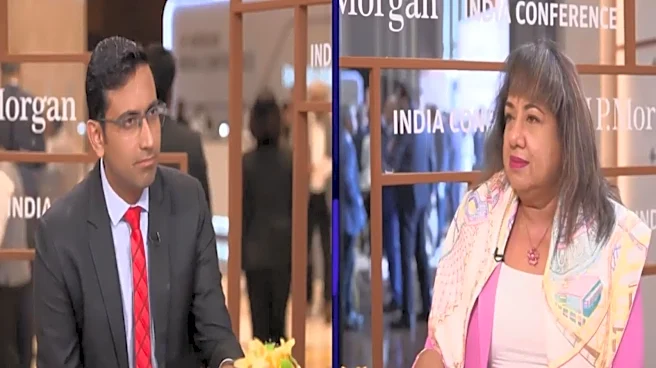
According to Anu Aiyengar, Global Chair of Investment Banking at JPMorgan, greater cross-border activity and the creation of global brands could help change that.
Speaking to CNBC-TV18 on the sidelines of the J.P. Morgan India Conference 2026, Aiyengar said Indian companies have strong balance sheets, significant cash and continued growth opportunities. However, she believes more large Indian companies need to look beyond the domestic market.
Her argument comes against the backdrop of a global M&A market where companies are increasingly pursuing scale, strategic capabilities and risk mitigation despite geopolitical uncertainty.
Why haven't Indian large-caps gained greater global relevance?
Aiyengar said the past 15 years of domestic growth have helped many Indian businesses become large-cap companies.
The issue, however, is that this growth has largely been driven by the domestic market.
“If you look at what happened before 2010, you actually did see some cross-border activity,” she said.
According to Aiyengar, the rest of the world has subsequently seen a significant increase in cross-border M&A, while Indian companies have not participated to the same extent.
She also pointed to a broader issue of global visibility.
“They are not in the global conversation in a way that they should be,” Aiyengar said.
This matters because global investors compare Indian companies with businesses across markets. Simply becoming a large company in India does not necessarily give it the same global relevance as a company with an international presence and recognised brands.
Why does outbound M&A matter?
Aiyengar believes outbound acquisitions could provide Indian large-caps with a route to greater global relevance.
She cited the $11.75-billion Sun Pharma deal as an example of a large Indian company making a major acquisition outside India. But she argued that transactions of this scale should become more common.
“An Indian company making an acquisition of $10 billion-plus outside India should not be the exception,” she said.
Her argument is that Indian companies have the financial capacity to pursue larger transactions. Strong corporate earnings, balance sheets and regulatory reform have changed the financial position of Indian businesses compared with a decade ago.
“Most companies do have the financial wherewithal to do billion-plus transactions. That was not the case 10 years ago,” Aiyengar said.
The question, therefore, is not simply whether Indian companies can finance large acquisitions. It is whether they use that capacity to build businesses with a greater global footprint.
How can global brands help?
For Aiyengar, outbound M&A is closely linked to the need to create globally relevant businesses and brands.
Indian companies still have significant growth opportunities in the domestic market, but she believes that alone may not be enough to attract the attention of global investors.
“While there is still growth opportunity in India, and by no means are you capped at it, in order to capture the imagination of global investors and become relevant globally, I think you need global brands,” she said.
The emphasis on global brands is therefore part of a broader argument about relevance.
A company that remains focused primarily on India's domestic market may continue to grow, but an acquisition strategy that adds international capabilities, brands or markets could give it a more global profile.
Aiyengar sees that as one way large-cap Indian companies could potentially attract greater international investor interest and achieve a rerating.
Why is cross-border M&A growing globally?
The push towards cross-border M&A is not unique to India.
Aiyengar said that of the $4 trillion of global M&A activity in the first eight months of the year, around $1 trillion was cross-border, or 25%.
That activity is taking place despite geopolitical tensions, wars and conflicts, supply-chain disruptions, higher oil prices, demographic changes and a more protectionist regulatory environment.
In fact, Aiyengar believes some of these challenges are themselves creating reasons for companies to transact.
Businesses are increasingly looking for quality, safety and scale. They are also assessing how geopolitical and supply-chain risks could affect their operations.
This is creating strategic reasons for companies to pursue acquisitions rather than simply waiting for a more stable macroeconomic environment.
How is AI changing dealmaking?
AI is another major factor behind the increase in strategic activity, although Aiyengar does not see it as the only driver.
Companies have to decide what technology capabilities they need, how much capital they need to invest and whether they should develop capabilities internally or acquire them.
That can generate activity across debt, equity and M&A markets.
Aiyengar said the same principle applies to energy. Higher oil prices can leave some companies with more cash to deploy, while others may look for ways to hedge their exposure.
The common thread is strategic decision-making.
Companies are looking at M&A not only as a way to expand, but also as a means of managing risk, acquiring capabilities and creating value.
Why haven't higher interest rates stopped dealmaking?
Higher interest rates have traditionally acted as a constraint on transactions, particularly leveraged buyouts. But Aiyengar said the current increase in financing costs has not so far become a major impediment to companies pursuing strategic objectives.
Financing and capital remain available, although the cost has risen.
The broader concern for private equity, she said, has been the difficulty of monetising assets acquired in 2020 and 2021, rather than simply higher interest rates.
At the same time, companies are taking a longer-term view of capital allocation.
Aiyengar said businesses may accept a higher capital requirement or even a dilutive transaction if it helps strengthen their balance sheet and reduce risk at a time of high macroeconomic uncertainty.
What could this mean for India's large-cap companies?
Aiyengar's argument is that Indian companies have already built significant domestic scale. The next step could be to use that financial strength to become more globally relevant.
More outbound acquisitions could help companies gain international capabilities and brands, while greater cross-border activity could increase their visibility among global investors.
This is also where India's capital markets could play a role.
Aiyengar said multinational companies are looking at their India stakes in different ways, including monetising them, listing businesses or bringing in partners. A listed Indian business can also provide “currency” that can subsequently be used for acquisitions and further growth.
India, she said, remains an important growth market, while valuations can be attractive relative to global valuations.
Where else does Aiyengar see opportunities in India?
While cross-border activity is one area she is optimistic about, Aiyengar also highlighted manufacturing as an area that could attract more attention.
AI and digital infrastructure remain major themes, but she believes manufacturing is currently underestimated.
The connection between the two is important. The infrastructure required to support AI growth can itself require specialised, customised and sophisticated manufacturing capabilities.
Aiyengar also highlighted the growing number of companies being created in India's small- and mid-cap segment and in cities and towns that may be less familiar to global investors.
She said she regularly meets new companies and young founders when she visits India, suggesting that the opportunity is expanding beyond India's traditional corporate centers.
The bigger picture
Aiyengar's broader argument is that India's next phase of corporate growth could involve a shift from domestic scale to global relevance.
Indian companies have accumulated stronger balance sheets and greater financial capacity over the past decade. The opportunity, according to Aiyengar, is to use that strength to pursue more cross-border acquisitions, build global brands and become more relevant to international investors.
For large-cap companies, outbound M&A could therefore become more than a growth strategy. It could be a way to build the global relevance that Aiyengar believes Indian businesses currently lack.
According to Anu Aiyengar, Global Chair of Investment Banking at JPMorgan, greater cross-border activity and the creation of global brands could help change that.
Speaking to CNBC-TV18 on the sidelines of the J.P. Morgan India Conference 2026, Aiyengar said Indian companies have strong balance sheets, significant cash and continued growth opportunities. However, she believes more large Indian companies need to look beyond the domestic market.
Her argument comes against the backdrop of a global M&A market where companies are increasingly pursuing scale, strategic capabilities and risk mitigation despite geopolitical uncertainty.
Why haven't Indian large-caps gained greater global relevance?
Aiyengar said the past 15 years of domestic growth have helped many Indian businesses become large-cap companies.
The issue, however, is that this growth has largely been driven by the domestic market.
“If you look at what happened before 2010, you actually did see some cross-border activity,” she said.
According to Aiyengar, the rest of the world has subsequently seen a significant increase in cross-border M&A, while Indian companies have not participated to the same extent.
She also pointed to a broader issue of global visibility.
“They are not in the global conversation in a way that they should be,” Aiyengar said.
This matters because global investors compare Indian companies with businesses across markets. Simply becoming a large company in India does not necessarily give it the same global relevance as a company with an international presence and recognised brands.
Why does outbound M&A matter?
Aiyengar believes outbound acquisitions could provide Indian large-caps with a route to greater global relevance.
She cited the $11.75-billion Sun Pharma deal as an example of a large Indian company making a major acquisition outside India. But she argued that transactions of this scale should become more common.
“An Indian company making an acquisition of $10 billion-plus outside India should not be the exception,” she said.
Her argument is that Indian companies have the financial capacity to pursue larger transactions. Strong corporate earnings, balance sheets and regulatory reform have changed the financial position of Indian businesses compared with a decade ago.
“Most companies do have the financial wherewithal to do billion-plus transactions. That was not the case 10 years ago,” Aiyengar said.
The question, therefore, is not simply whether Indian companies can finance large acquisitions. It is whether they use that capacity to build businesses with a greater global footprint.
How can global brands help?
For Aiyengar, outbound M&A is closely linked to the need to create globally relevant businesses and brands.
Indian companies still have significant growth opportunities in the domestic market, but she believes that alone may not be enough to attract the attention of global investors.
“While there is still growth opportunity in India, and by no means are you capped at it, in order to capture the imagination of global investors and become relevant globally, I think you need global brands,” she said.
The emphasis on global brands is therefore part of a broader argument about relevance.
A company that remains focused primarily on India's domestic market may continue to grow, but an acquisition strategy that adds international capabilities, brands or markets could give it a more global profile.
Aiyengar sees that as one way large-cap Indian companies could potentially attract greater international investor interest and achieve a rerating.
Why is cross-border M&A growing globally?
The push towards cross-border M&A is not unique to India.
Aiyengar said that of the $4 trillion of global M&A activity in the first eight months of the year, around $1 trillion was cross-border, or 25%.
That activity is taking place despite geopolitical tensions, wars and conflicts, supply-chain disruptions, higher oil prices, demographic changes and a more protectionist regulatory environment.
In fact, Aiyengar believes some of these challenges are themselves creating reasons for companies to transact.
Businesses are increasingly looking for quality, safety and scale. They are also assessing how geopolitical and supply-chain risks could affect their operations.
This is creating strategic reasons for companies to pursue acquisitions rather than simply waiting for a more stable macroeconomic environment.
How is AI changing dealmaking?
AI is another major factor behind the increase in strategic activity, although Aiyengar does not see it as the only driver.
Companies have to decide what technology capabilities they need, how much capital they need to invest and whether they should develop capabilities internally or acquire them.
That can generate activity across debt, equity and M&A markets.
Aiyengar said the same principle applies to energy. Higher oil prices can leave some companies with more cash to deploy, while others may look for ways to hedge their exposure.
The common thread is strategic decision-making.
Companies are looking at M&A not only as a way to expand, but also as a means of managing risk, acquiring capabilities and creating value.
Why haven't higher interest rates stopped dealmaking?
Higher interest rates have traditionally acted as a constraint on transactions, particularly leveraged buyouts. But Aiyengar said the current increase in financing costs has not so far become a major impediment to companies pursuing strategic objectives.
Financing and capital remain available, although the cost has risen.
The broader concern for private equity, she said, has been the difficulty of monetising assets acquired in 2020 and 2021, rather than simply higher interest rates.
At the same time, companies are taking a longer-term view of capital allocation.
Aiyengar said businesses may accept a higher capital requirement or even a dilutive transaction if it helps strengthen their balance sheet and reduce risk at a time of high macroeconomic uncertainty.
What could this mean for India's large-cap companies?
Aiyengar's argument is that Indian companies have already built significant domestic scale. The next step could be to use that financial strength to become more globally relevant.
More outbound acquisitions could help companies gain international capabilities and brands, while greater cross-border activity could increase their visibility among global investors.
This is also where India's capital markets could play a role.
Aiyengar said multinational companies are looking at their India stakes in different ways, including monetising them, listing businesses or bringing in partners. A listed Indian business can also provide “currency” that can subsequently be used for acquisitions and further growth.
India, she said, remains an important growth market, while valuations can be attractive relative to global valuations.
Where else does Aiyengar see opportunities in India?
While cross-border activity is one area she is optimistic about, Aiyengar also highlighted manufacturing as an area that could attract more attention.
AI and digital infrastructure remain major themes, but she believes manufacturing is currently underestimated.
The connection between the two is important. The infrastructure required to support AI growth can itself require specialised, customised and sophisticated manufacturing capabilities.
Aiyengar also highlighted the growing number of companies being created in India's small- and mid-cap segment and in cities and towns that may be less familiar to global investors.
She said she regularly meets new companies and young founders when she visits India, suggesting that the opportunity is expanding beyond India's traditional corporate centers.
The bigger picture
Aiyengar's broader argument is that India's next phase of corporate growth could involve a shift from domestic scale to global relevance.
Indian companies have accumulated stronger balance sheets and greater financial capacity over the past decade. The opportunity, according to Aiyengar, is to use that strength to pursue more cross-border acquisitions, build global brands and become more relevant to international investors.
For large-cap companies, outbound M&A could therefore become more than a growth strategy. It could be a way to build the global relevance that Aiyengar believes Indian businesses currently lack.