

What's Happening?
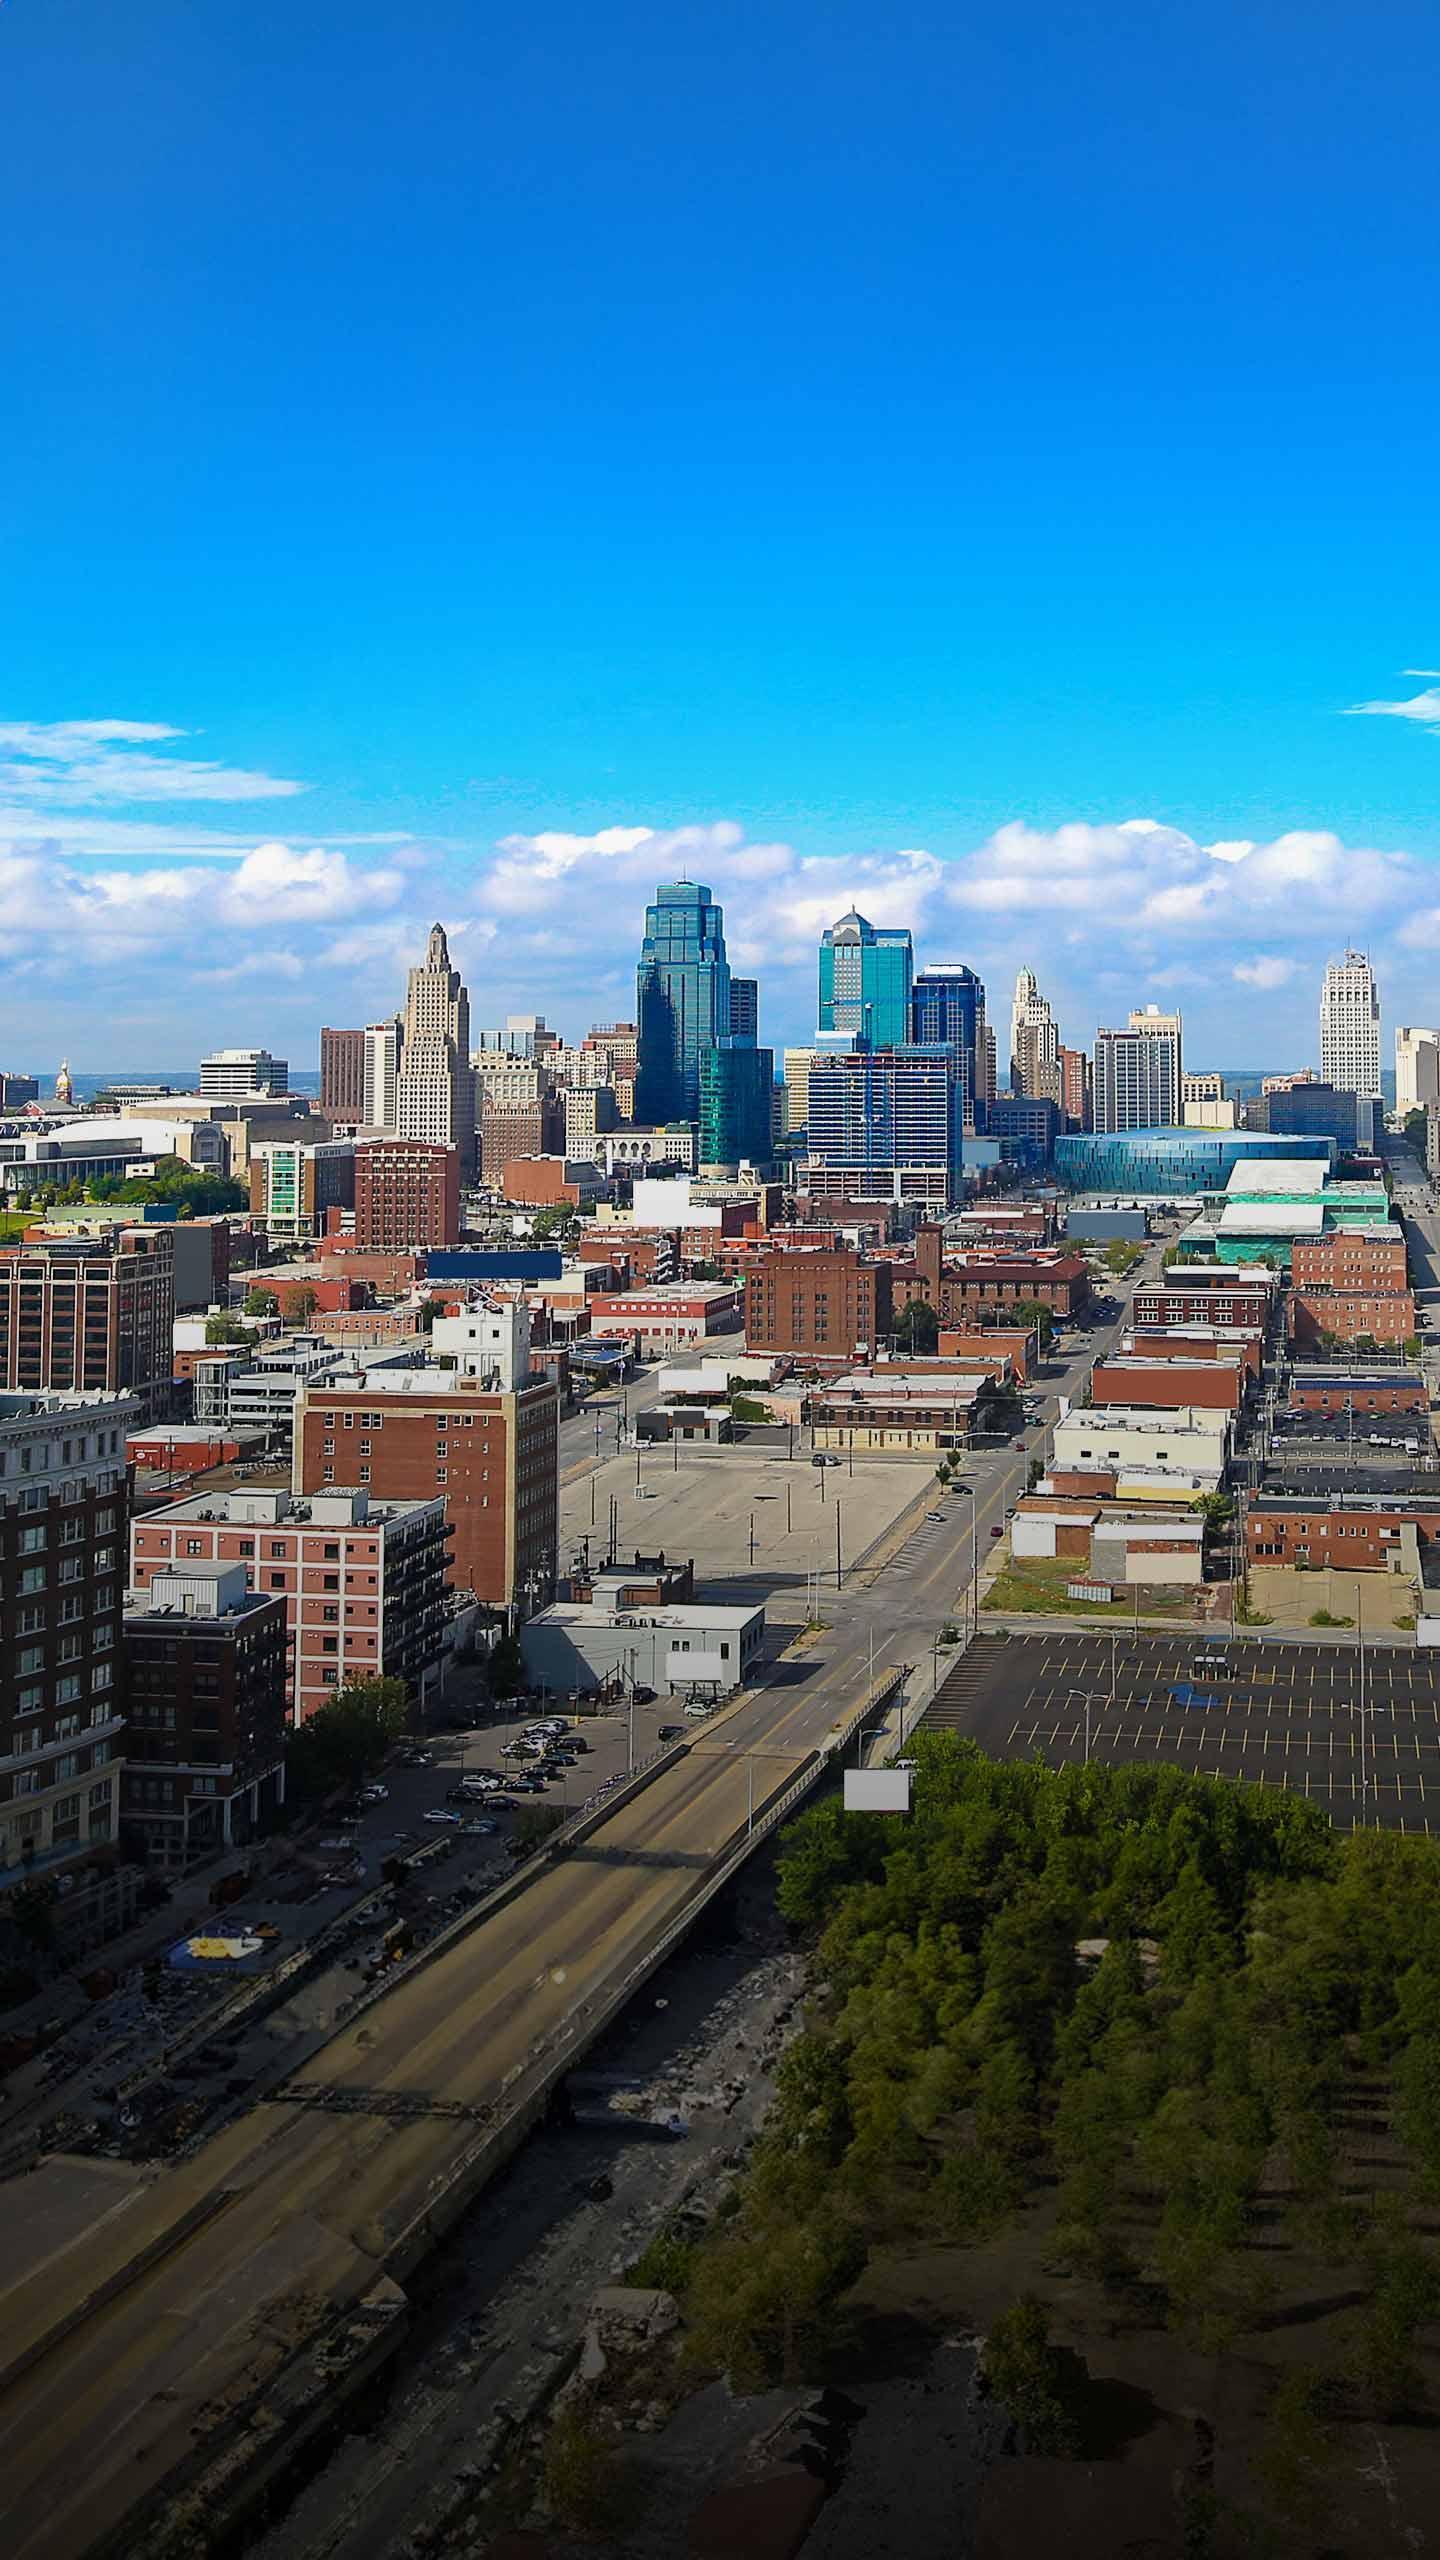
Kansas City's office market experienced a significant increase in its vacancy rate, rising by 160 basis points from Q2 to reach 15.1% in Q3 2026, according to Newmark Zimmer. This surge is primarily attributed
to negative absorption of 1.2 million square feet, largely tied to previously announced contractions by Oracle/Cerner. Despite this, the year-over-year office vacancy rate is slightly down by 20 basis points. In contrast, the industrial market in Kansas City demonstrated robust performance, posting the lowest industrial vacancy rate among the top 30 U.S. industrial markets at 3.7% in the same quarter. Industrial demand saw 5.8 million square feet of net absorption in Q3, marking the tenth consecutive positive quarter. Average asking rents for industrial spaces reached a record $6.49 per square foot NNN, an 8.5% increase year-over-year. The office market also saw average asking rents increase by 1.9% year-over-year to $23.76 per square foot. Class A office asking rents have risen by 11.7% since Q3 2023, with no new multi-tenant office buildings currently under construction.
Why It's Important?
The divergent trends in Kansas City's commercial real estate market highlight a significant shift in demand and investment priorities within the U.S. economy. The sharp increase in office vacancy, despite a slight year-over-year decrease, underscores the ongoing challenges faced by the office sector, particularly with large corporate contractions impacting absorption. This situation could lead to increased financial pressure on office building owners, potentially affecting property values and loan performance for financial institutions with exposure to this segment. Conversely, the booming industrial market, driven by strong demand and record-low vacancy rates, reflects the continued growth in e-commerce, logistics, and data center operations. This sector's strength provides a counterbalance to the office market's struggles, attracting significant investment and supporting job growth in related industries. The 'flight to quality' within the office market, where Class A properties maintain higher rents and no new construction is underway, suggests a bifurcation where premium spaces remain competitive while older, less desirable offices face increasing obsolescence. This dynamic will influence future development, investment strategies, and urban planning in Kansas City and potentially other U.S. metropolitan areas.
What's Next?
For the Kansas City office market, the immediate future will likely involve continued efforts by property owners to adapt to reduced demand and higher vacancy rates, particularly for Class B and older properties. With significant office debt maturing in 2027, there may be increased pressure for recapitalization or repositioning of assets. Investors are expected to favor well-located, high-quality office buildings, betting on a 'flight to quality.' In the industrial sector, the tight market conditions are projected to continue, with vacancy rates potentially falling further to 3.4% to 3.5% by Q2 2027, and asking rents expected to rise. This will likely lead to more speculative construction to meet demand, though lease-up on new buildings will vary. Overall, the Kansas City market will continue to see a strong divide between the thriving industrial sector and the challenged office sector, requiring tailored strategies from developers, investors, and tenants.
Beyond the Headlines
The contrasting fortunes of Kansas City's office and industrial real estate markets reflect broader economic and societal shifts. The office market's struggles are indicative of the lasting impact of hybrid work models and corporate downsizing, challenging traditional notions of urban office hubs. This could lead to a re-evaluation of urban development strategies, potentially encouraging conversions of older office buildings to residential or mixed-use spaces. The robust industrial market, on the other hand, highlights the increasing importance of supply chain resilience, e-commerce infrastructure, and technological advancements like data centers. This trend could further decentralize economic activity and create new employment opportunities in logistics and manufacturing. The disparity also raises questions about equitable development and access to opportunities, as different sectors of the economy experience vastly different growth trajectories. Understanding these underlying forces is crucial for long-term planning and ensuring sustainable economic development in U.S. cities.