
What's Happening?
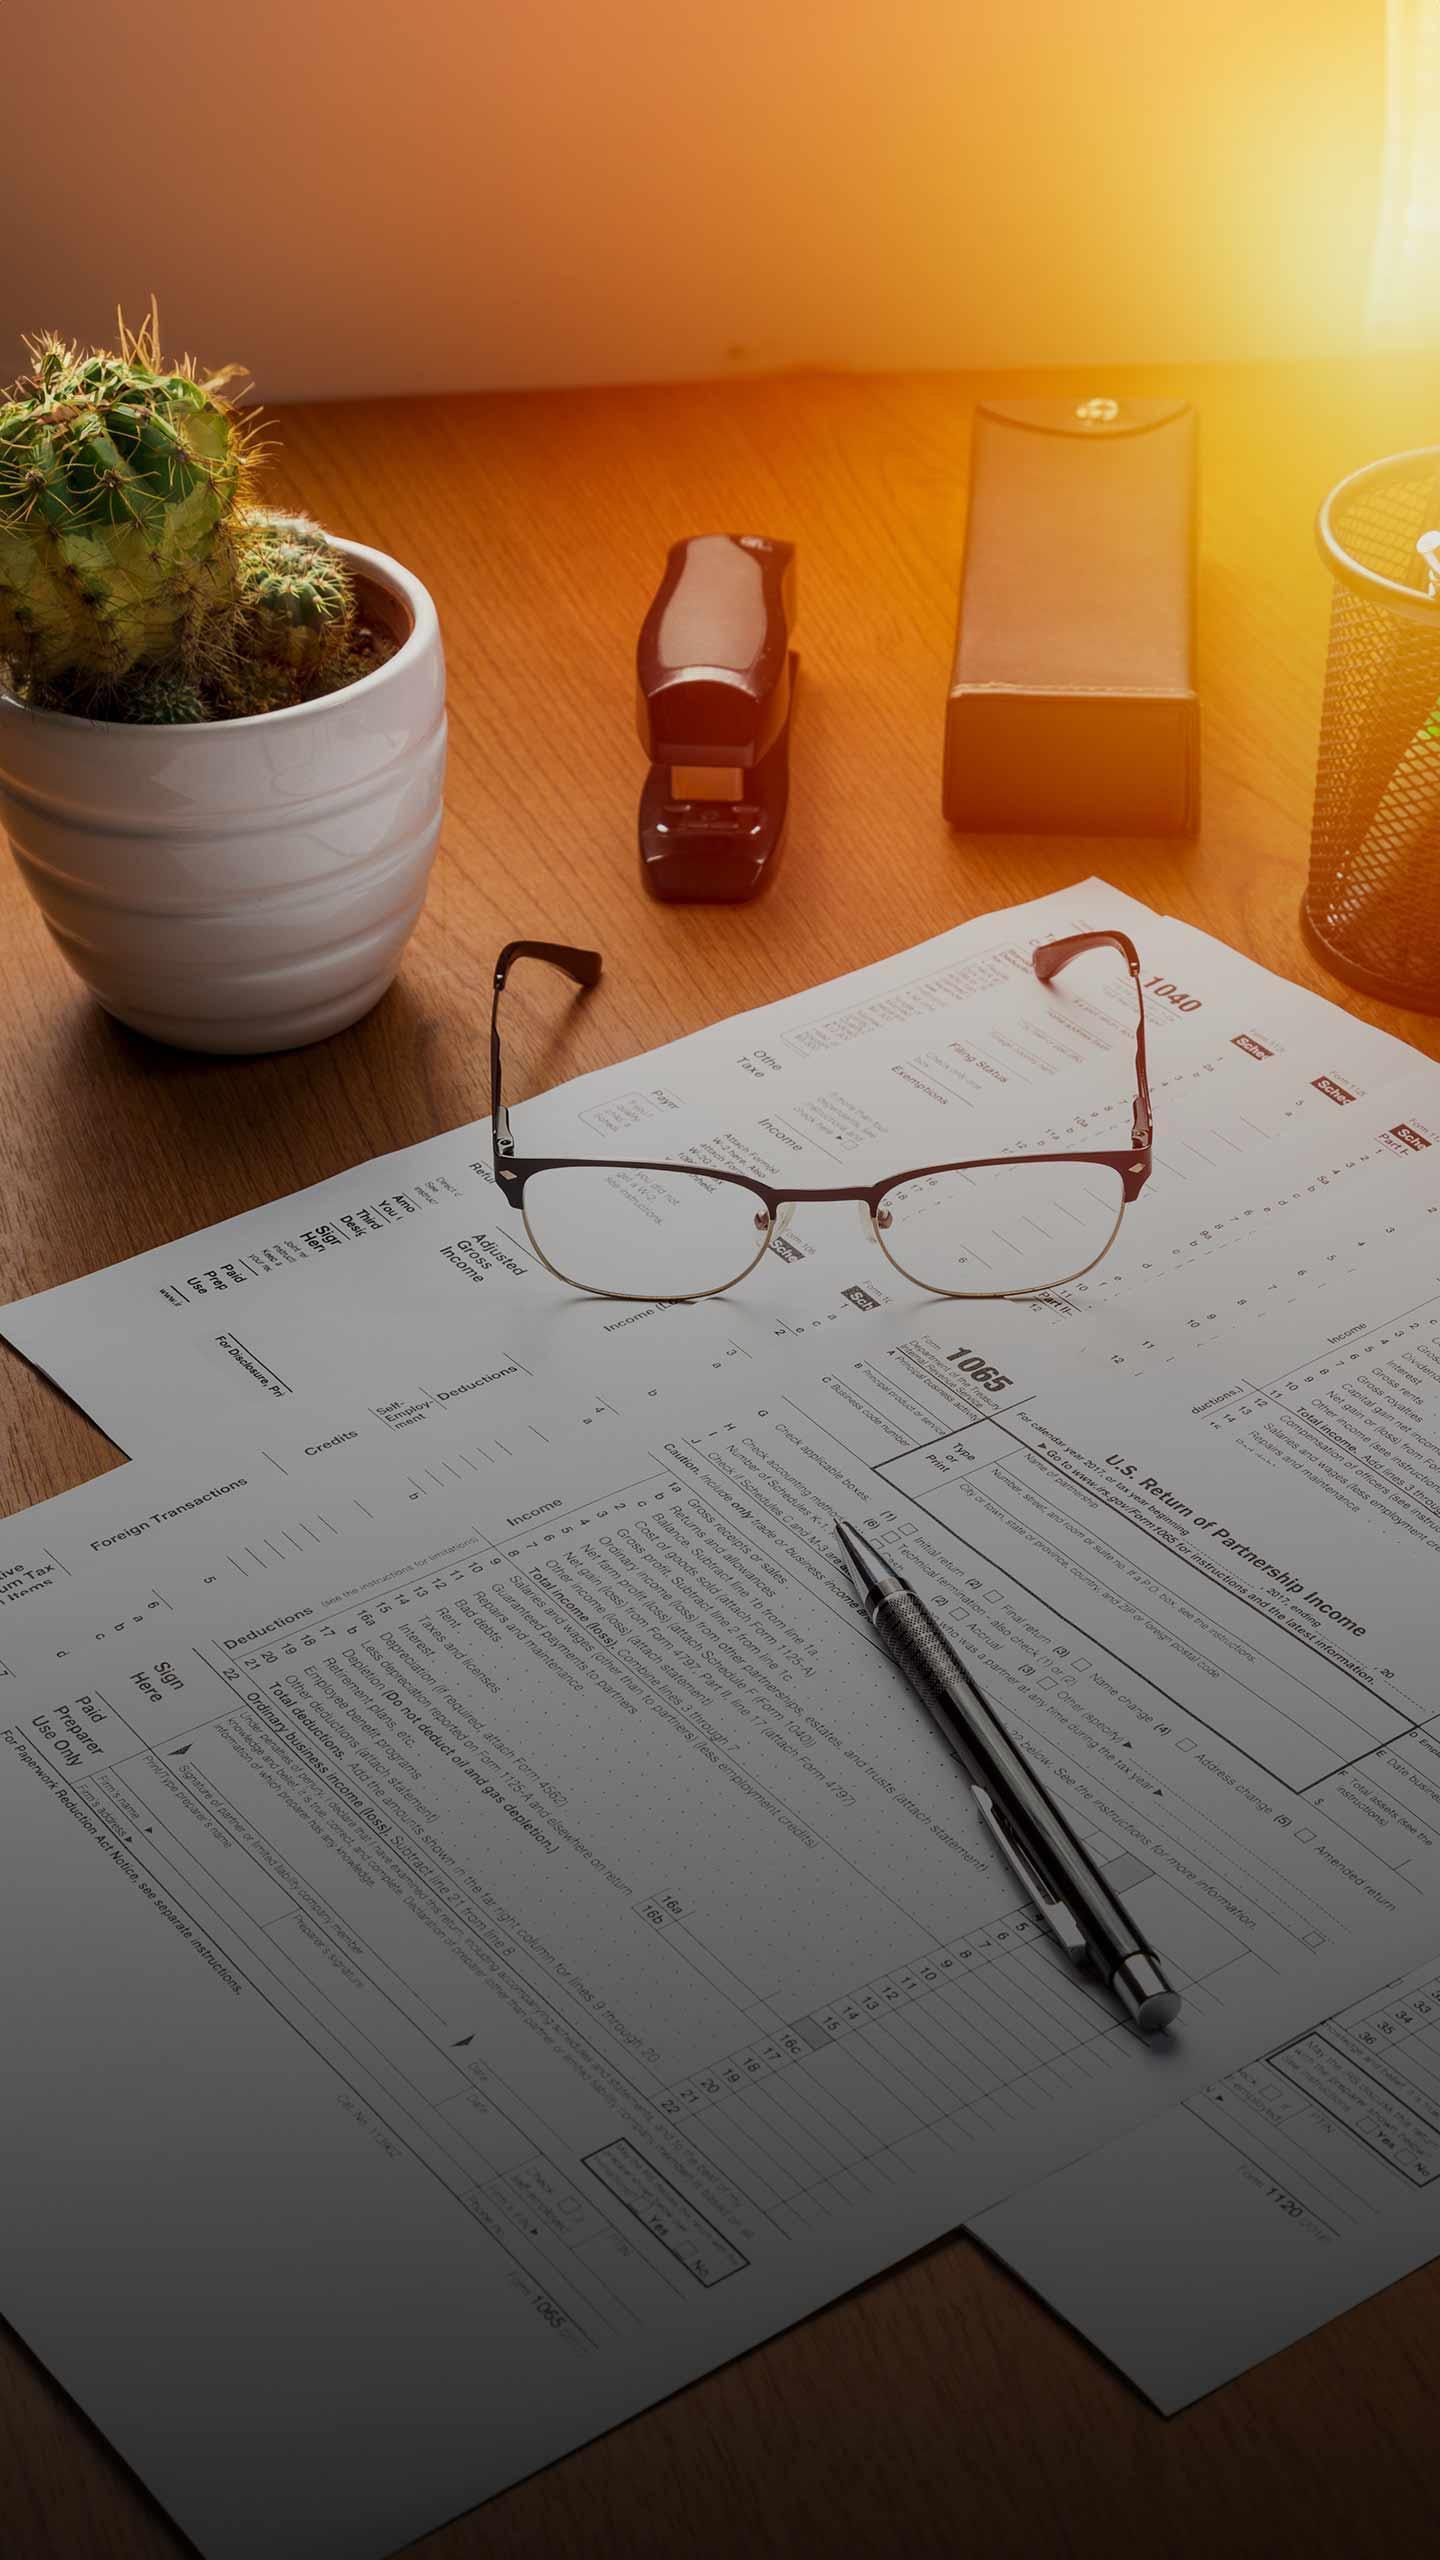
The Internal Revenue Service (IRS) has clarified the application of a de minimis exemption for U.S. partnership tax returns, specifically Form 1065. This exemption may apply to foreign partnerships with
U.S. partners, allowing them to bypass certain filing duties. The conditions for this exemption are that U.S.-source income remains at or below $20,000, and less than 1% of the partnership's items are allocable to U.S. partners. This clarification is particularly relevant for Australian businesses and investors with U.S. partnership interests, who often face complexities in navigating these tax regulations. The Form 1065 is an information return that reports a partnership's financial activity to the IRS, with income and deductions passing through to the partners, who then report these on their individual returns. The IRS emphasizes that while the partnership itself generally does not pay income tax, partners can still owe tax on undistributed income.
Why It's Important?
This clarification is important for U.S. tax compliance, especially for foreign partnerships with minor U.S. involvement. By defining clear thresholds for the de minimis exemption, the IRS aims to reduce the administrative burden on partnerships that have minimal U.S.-source income or U.S. partners. This can lead to cost savings and simplified compliance procedures for eligible entities, preventing unnecessary filings and potential penalties for non-compliance. For U.S. partners in such foreign entities, understanding this exemption is crucial to ensure accurate reporting of their allocated income and deductions. The distinction between tax reporting and actual cash distribution is also highlighted, reminding partners that tax obligations can arise even without direct cash receipts. The rules also underscore the importance of accurate record-keeping and timely filing to avoid penalties, which can be substantial.
What's Next?
Partnerships, particularly those with international components, should review their U.S.-source income and the allocation of partnership items to U.S. partners to determine if they qualify for this de minimis exemption. While the exemption can simplify filing requirements, it does not negate the need for careful assessment of tax obligations. Entities that meet the criteria may be able to avoid filing Form 1065, but they must ensure they meet all conditions. The IRS also notes that additional international forms may still apply even if the de minimis exception is met. Partnerships should also be aware of the strict deadlines for filing Form 1065 and Schedule K-1, as late filings incur significant penalties. Consulting with qualified tax advisors is recommended to navigate these complex regulations and ensure full compliance.
Beyond the Headlines
The de minimis exemption reflects a broader effort by tax authorities to balance regulatory oversight with practical administrative efficiency. By setting thresholds for minor activities, the IRS acknowledges that the cost of compliance for very small amounts of income or limited U.S. involvement can outweigh the benefits of full reporting. This approach can encourage foreign investment and cross-border business by reducing perceived bureaucratic hurdles. However, the precise nature of these exemptions and their interaction with other tax laws, such as those governing foreign partner withholding, requires careful interpretation. The ongoing evolution of international tax regulations means that businesses must remain vigilant and proactive in understanding their obligations to avoid unintended tax consequences.