
What's Happening?
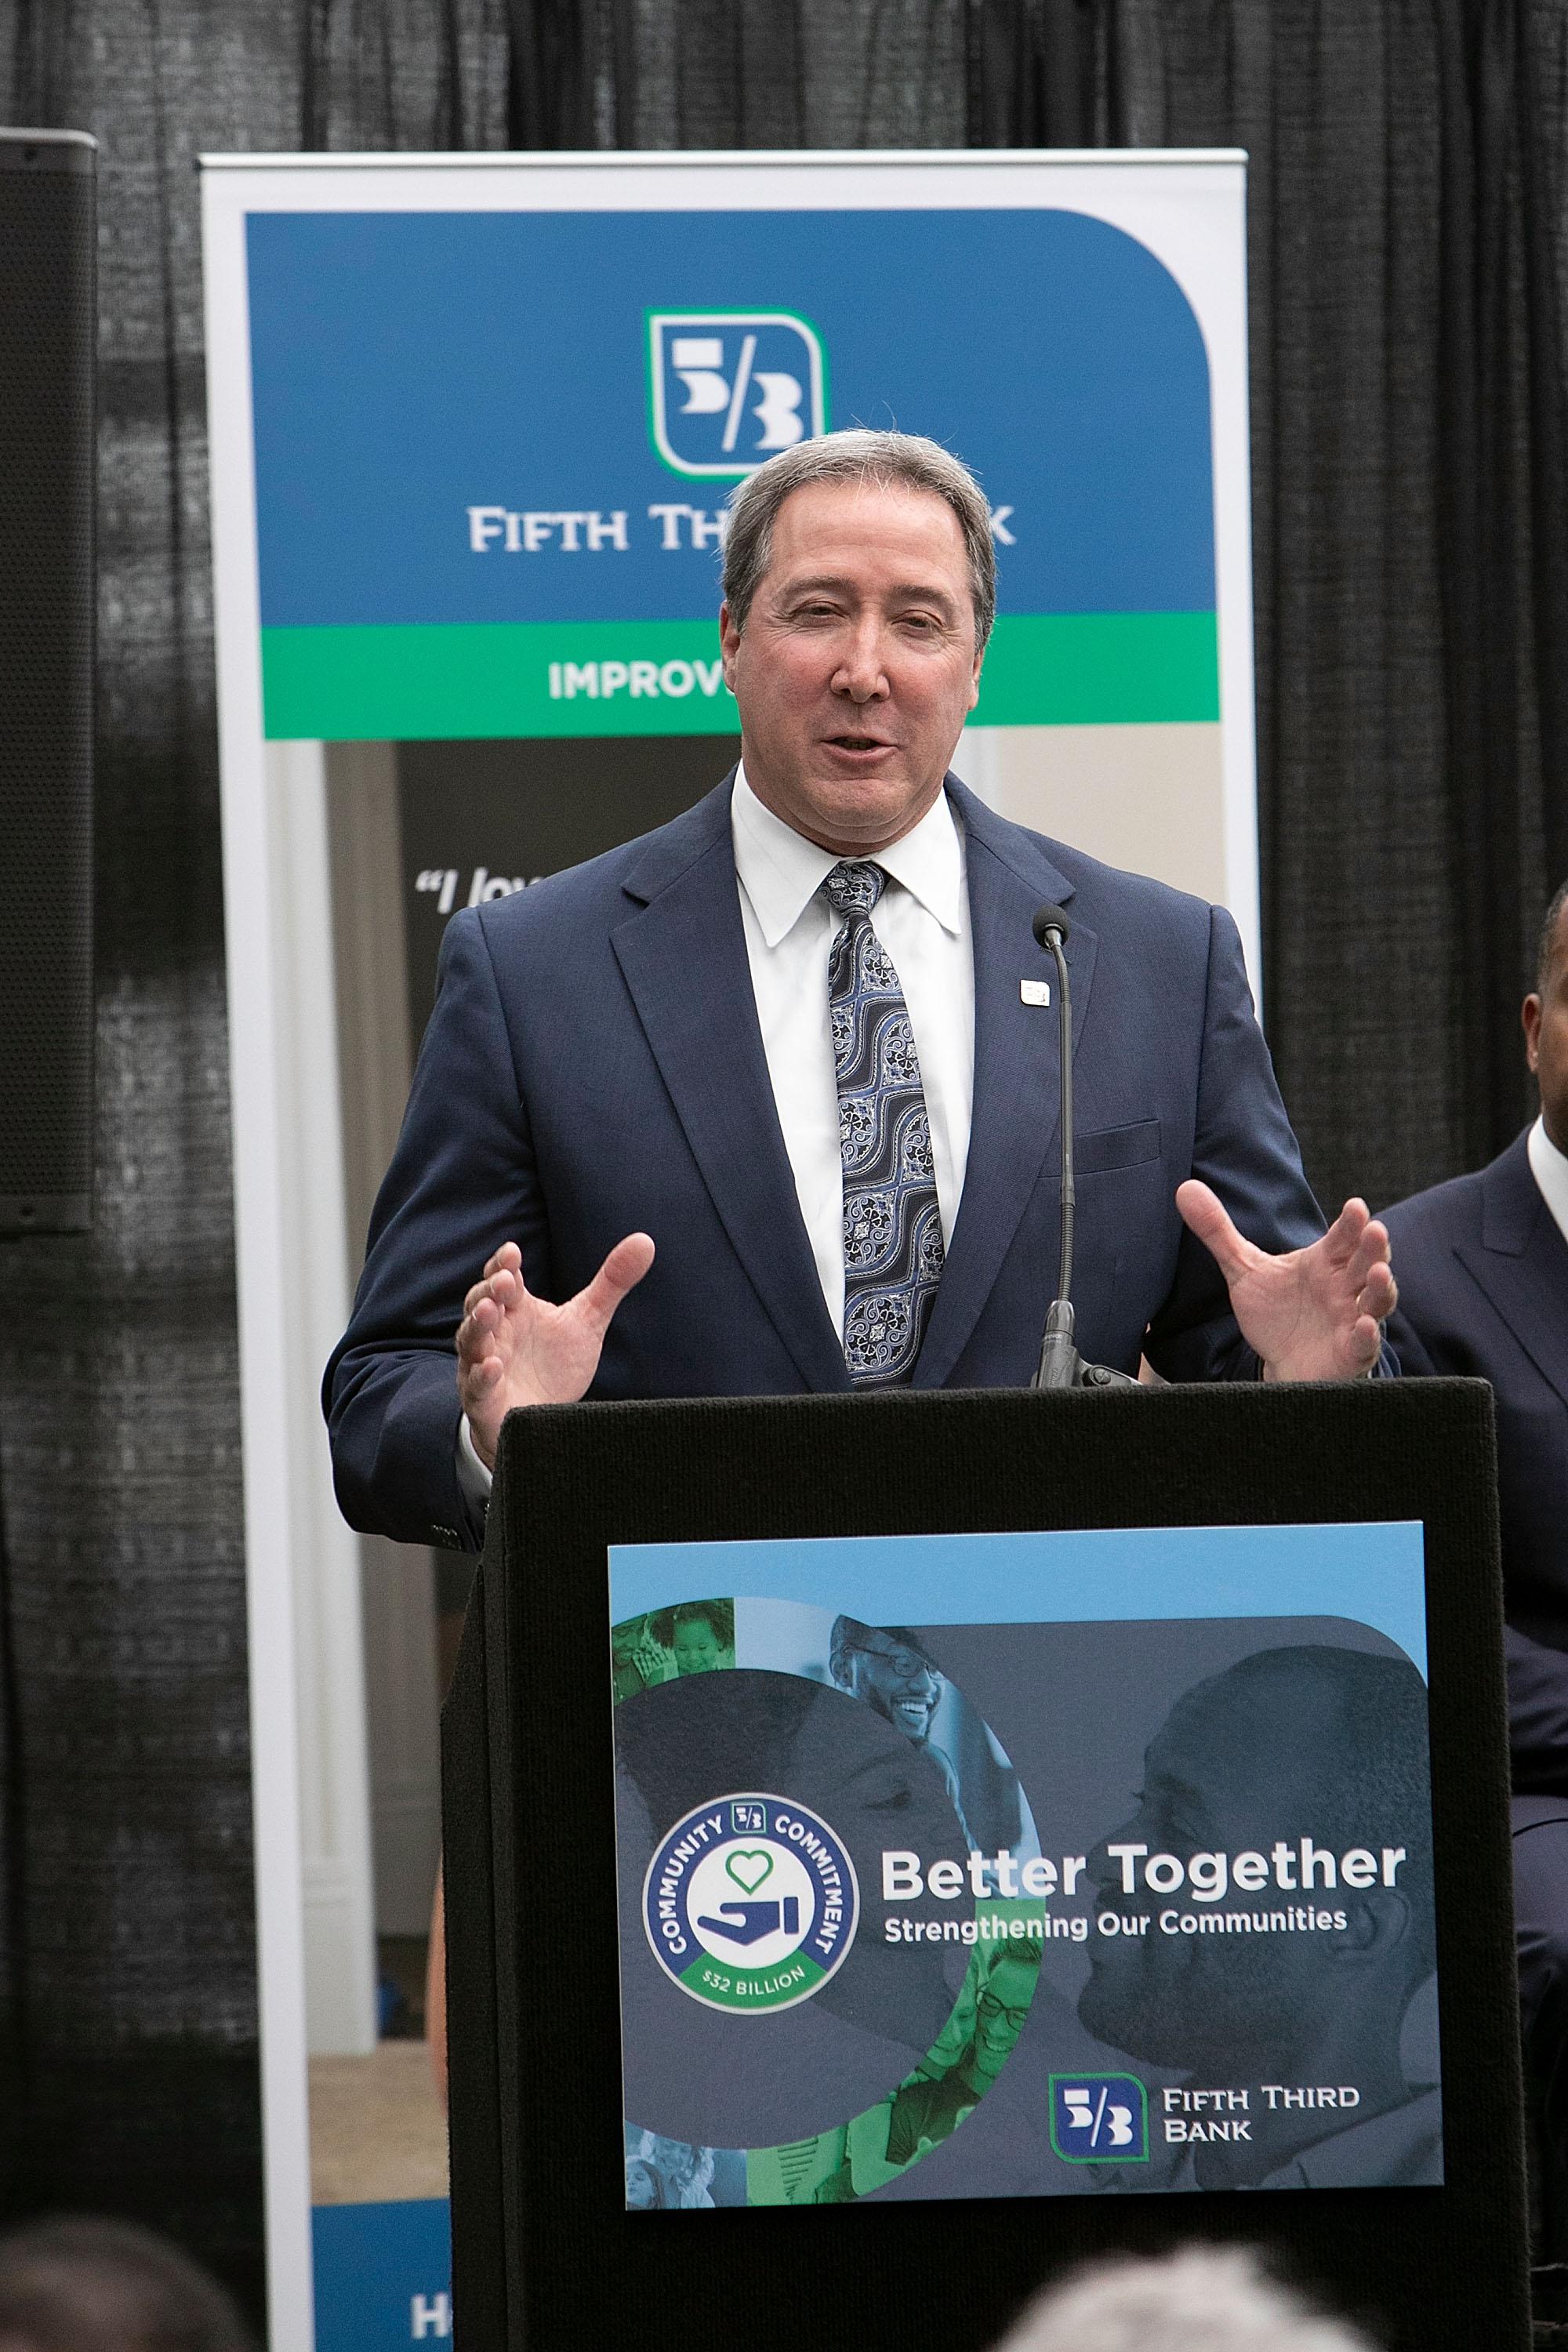
Fifth Third Bancorp (NYSE:FITB) has released its quarterly results, marking the first full reporting period since the acquisition of Comerica. This acquisition has significantly expanded Fifth Third's
asset base, positioning it among the largest banks in the U.S. The recent earnings report detailed substantial increases in net interest income, loans, and deposits compared to the previous year, primarily attributed to the integration of Comerica. Analysts are closely examining the sequential improvements from the prior quarter, which show a rise in net interest income, a decrease in noninterest expense, and stable credit metrics. A key highlight from the report is the successful and rapid completion of the systems conversion for Comerica, which was finalized less than a year after the deal's announcement. This technological integration is often considered the most challenging aspect of bank mergers due to its direct impact on customer experience and operational processes. The company reported strong client and banker retention throughout this transition, indicating a successful integration process. However, the reported earnings per share were affected by merger-related charges, litigation expenses, and technology asset impairments, though adjusted figures presented a more favorable financial picture.
Why It's Important?
This earnings release provides a crucial case study for the banking industry on the efficacy of large-scale mergers and acquisitions. The successful integration of Comerica by Fifth Third Bancorp demonstrates that significant consolidation can yield positive financial outcomes, such as increased earnings power and operational synergies, without substantial client attrition. The rapid completion of the systems conversion is particularly noteworthy, as it addresses a major risk factor in bank mergers, which often face public outages and customer dissatisfaction during such transitions. The report's details on deposit growth, particularly in Comerica's historical markets, suggest that Fifth Third is effectively leveraging its expanded footprint. For investors and market observers, the ability of Fifth Third to manage merger charges while still showing sequential improvements in core financial metrics offers insights into the potential for value creation in banking consolidation. The focus on fee-generating businesses like commercial payments and wealth management also signals a strategic shift towards more stable revenue streams, less susceptible to interest rate fluctuations, which could enhance the bank's resilience in varying economic cycles.
What's Next?
In the coming quarters, market watchers will closely monitor several key indicators for Fifth Third Bancorp. Analysts will be looking for continued trends in noninterest expense, deposit costs, and the growth of fee income from commercial payments and wealth management divisions. Retention data for both clients and bankers will remain a critical measure of the merger's long-term success. Any resumption of share retirements would also be a significant signal regarding capital allocation strategies. The company's outlined plan to expand its branch network, particularly in growth regions like Texas, will be observed for its execution and impact on deposit gathering and relationship building, although branch expansion is typically a long-term investment. Furthermore, the broader competitive landscape and the ongoing wave of bank consolidation will influence Fifth Third's strategic decisions. The company's ability to continue demonstrating synergies and cost controls while navigating potential risks such as interest rate fluctuations, economic strength, and regulatory changes will be crucial for its sustained performance and market perception.
Beyond the Headlines
The successful integration of Comerica by Fifth Third Bancorp extends beyond immediate financial metrics, offering deeper implications for the banking sector. This case highlights the increasing importance of technological agility and efficient project management in large-scale corporate integrations. The ability to complete a complex systems conversion quickly and smoothly sets a benchmark for future mergers, potentially influencing regulatory expectations and industry best practices. Furthermore, the emphasis on expanding fee-based businesses like commercial payments and wealth management reflects a broader strategic shift within the banking industry to diversify revenue streams and reduce reliance on traditional interest income, which is highly sensitive to economic cycles. This move towards a more balanced revenue portfolio could lead to greater stability and predictability for large financial institutions. The consolidation wave, exemplified by this acquisition, also raises questions about market concentration and competition, potentially impacting smaller regional banks and the overall accessibility of banking services in certain areas. The long-term success of such mergers will likely shape future regulatory approaches to banking consolidation and influence the competitive dynamics of the U.S. financial landscape.