
What's Happening?
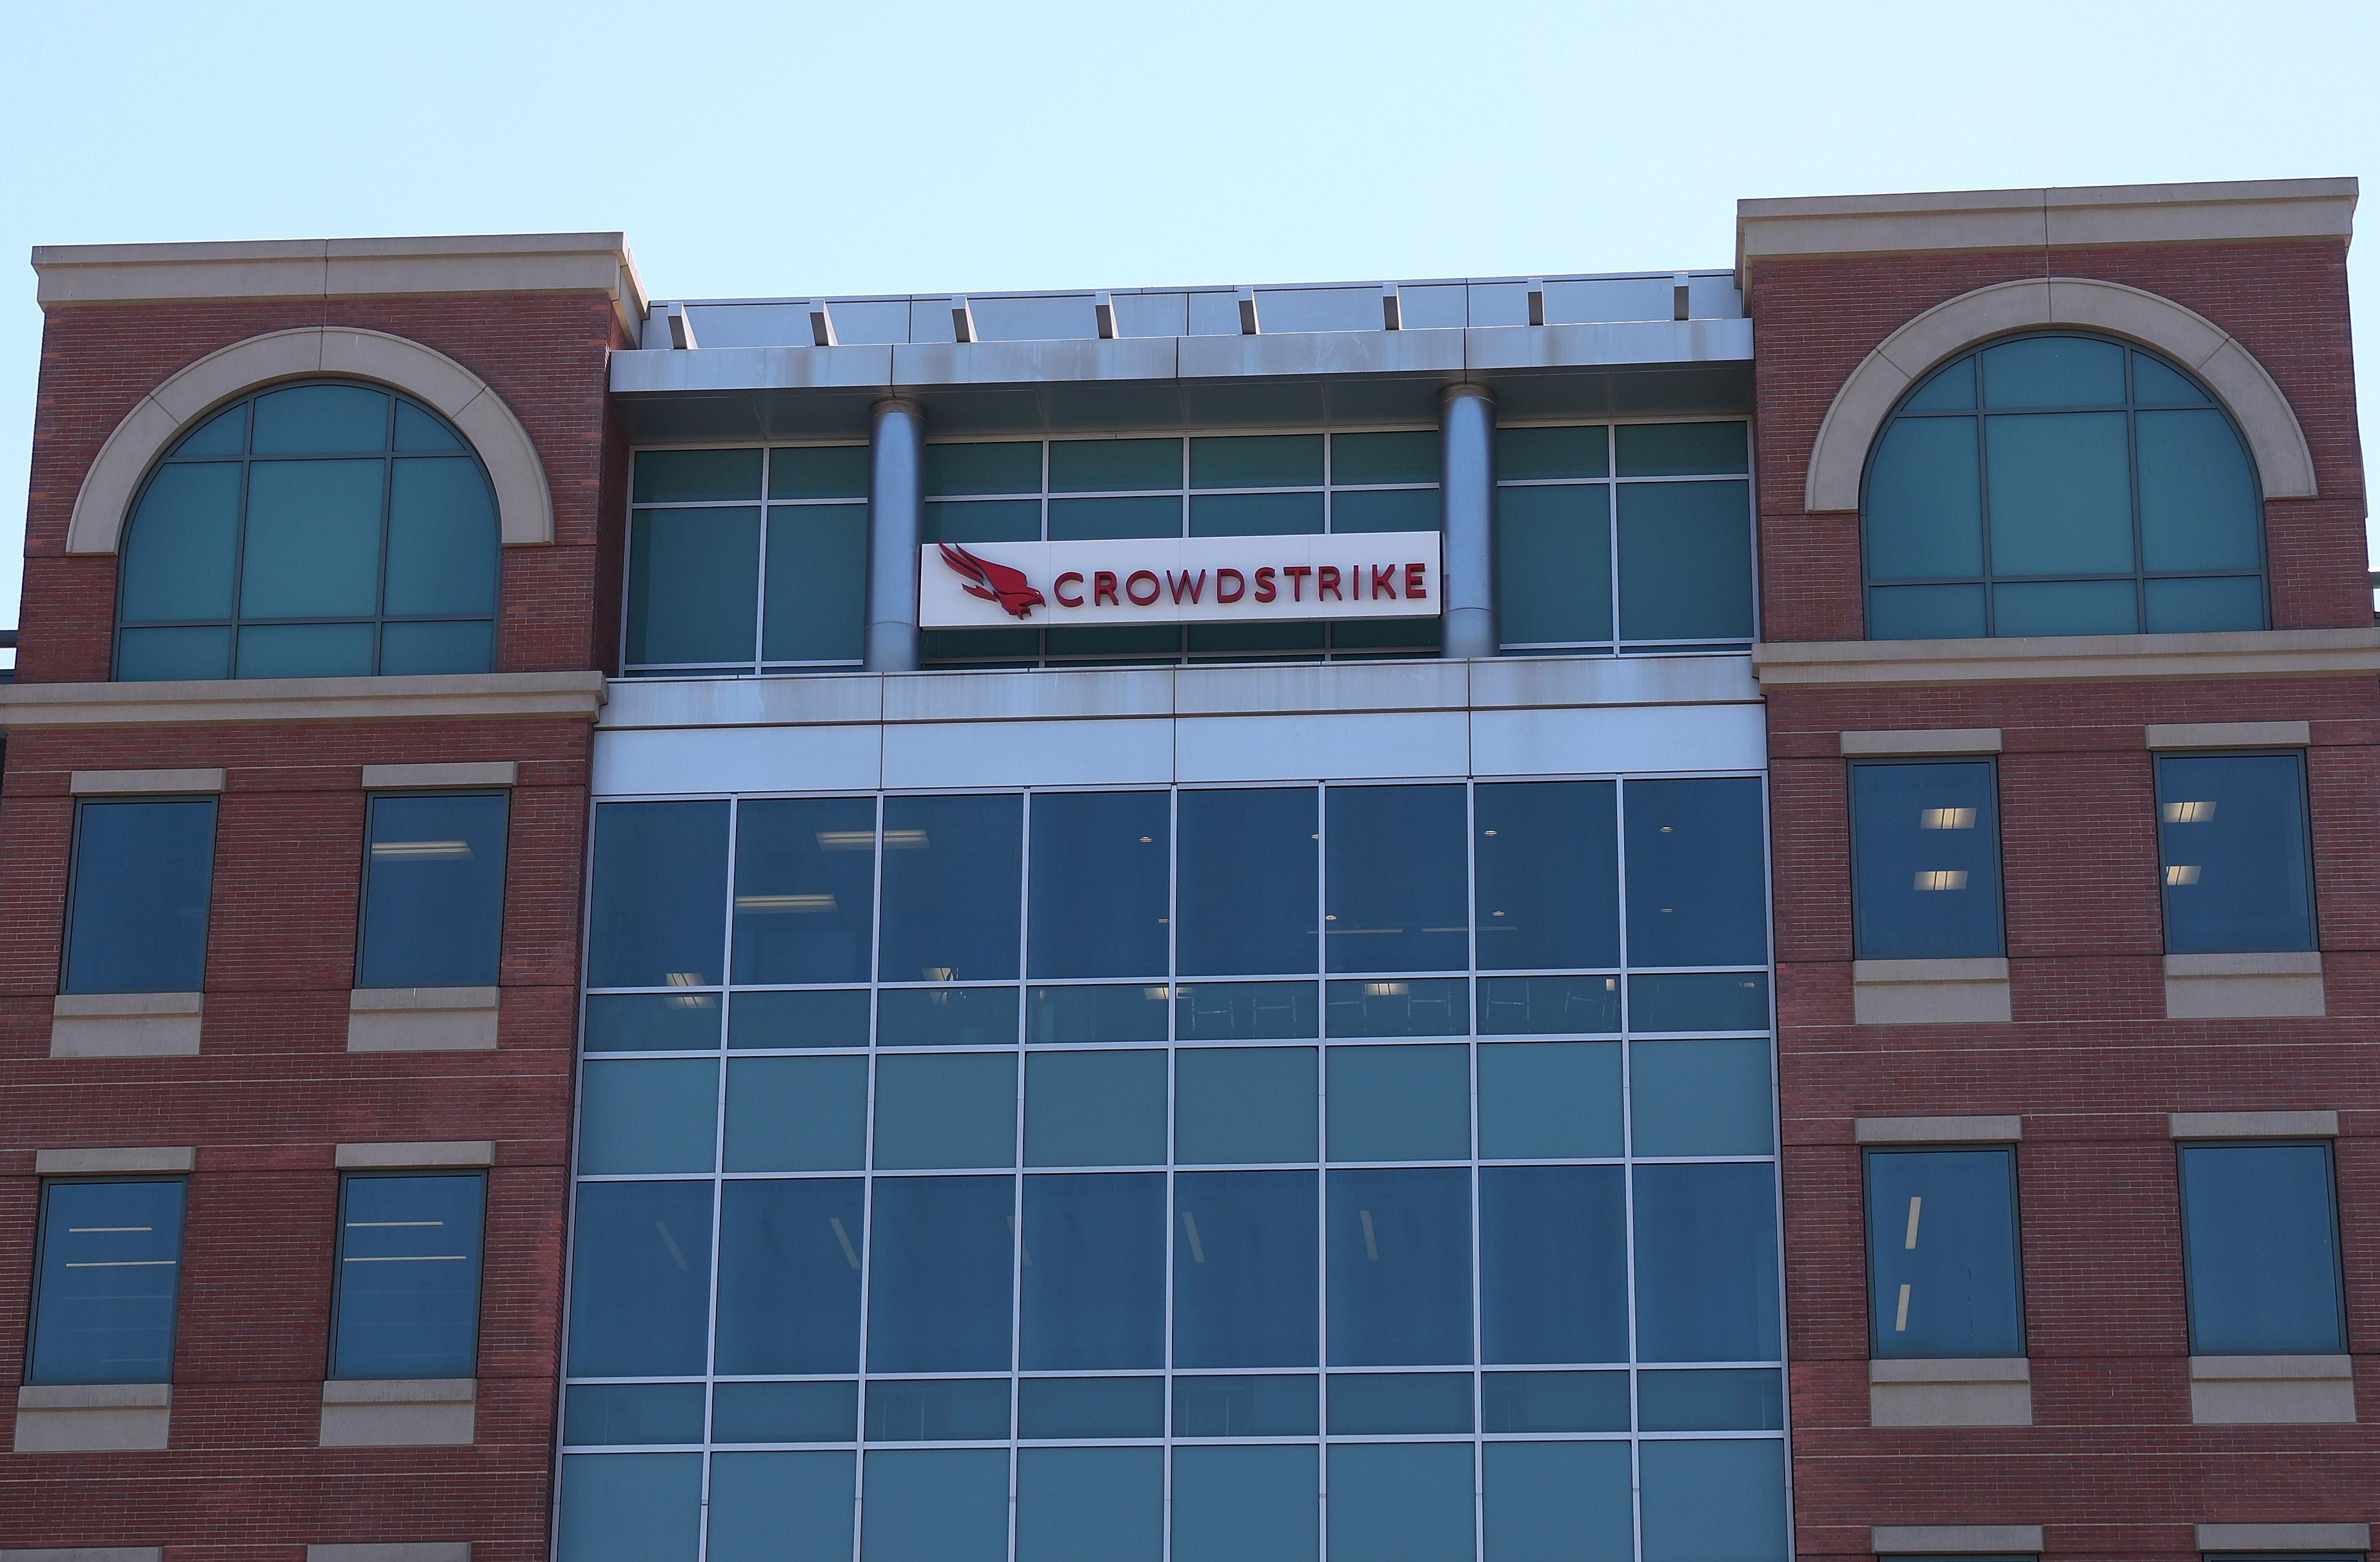
CrowdStrike (CRWD) experienced mixed investment activity from large funds in the quarter ending September 30, following its four-for-one stock split in July. While 13 big funds bought the stock, at least
12 sold, according to their 13F filings. WT Asset Management made the largest new buy, a $149 million position, while Blue Sparrow sold its entire $23 million stake. Despite strong demand for CrowdStrike's services, with net new annual recurring revenue (ARR) hitting a record $332.8 million in the quarter ending July 31, the stock trades at 155 times forward earnings, significantly above its five-year average of 110 times. Analysts' earnings estimates have shown minimal movement over the past year, with none of the next three years' figures rising more than 5%. The stock has fallen 17% since September 30, and its price target, while nearly doubled in a year to $251, largely reflects a higher multiple rather than increased earnings estimates.
Why It's Important?
The divergent actions of large institutional investors in CrowdStrike highlight a critical debate over the company's valuation and future growth prospects. While the strong demand for cybersecurity solutions and CrowdStrike's record ARR growth indicate a robust business, its high forward earnings multiple raises concerns about sustainability and potential overvaluation. The lack of significant upward revision in analysts' earnings estimates, despite the rising price target, suggests that much of the stock's appreciation is driven by multiple expansion rather than fundamental earnings growth. This situation creates a challenging environment for investors, as the stock's performance becomes highly sensitive to future earnings reports and market sentiment. For the U.S. cybersecurity industry, CrowdStrike's trajectory could influence investment trends and competitive dynamics, particularly as the demand for advanced security solutions continues to grow.
What's Next?
CrowdStrike's report for the quarter ending October 31, expected in early December, will be a crucial test for the stock. Management has guided for net new ARR of $343 million to $347 million for this quarter. A result exceeding $350 million, coupled with another full-year guidance raise, could provide analysts with a reason to increase their earnings estimates, potentially justifying the current high valuation. Conversely, a result within the guided range, without an updated full-year outlook, would imply a significant challenge for the January quarter to meet expectations. Investors will be closely watching these figures for signs of continued strong growth that could support the stock's premium multiple.
Beyond the Headlines
The mixed sentiment among big funds regarding CrowdStrike underscores a broader market tension between growth potential and valuation discipline, especially in the high-flying technology sector. The company's reliance on stock-based compensation, which amounted to $1.10 billion in the year ending January 2026—equal to 88.9% of its free cash flow—raises questions about the quality of its earnings and its ability to generate sustainable cash flow for shareholders. This practice, common in high-growth tech companies, can dilute shareholder value and impact long-term profitability. The debate over CrowdStrike's valuation also reflects the ongoing challenge for investors to accurately price companies in rapidly evolving sectors like cybersecurity, where future growth is often projected far into the future.