

By Saqib Iqbal Ahmed
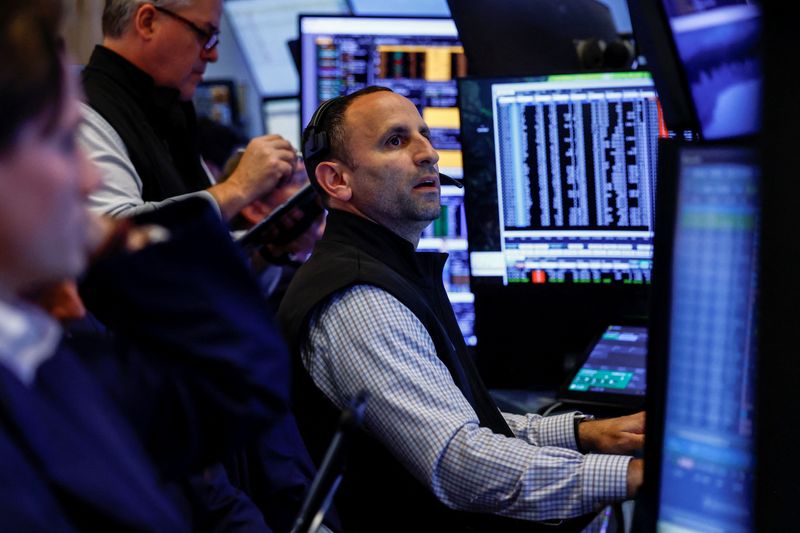
NEW YORK, Nov 5 (Reuters) - Retail investors ran for the exit, Wall Street's fear gauge spiked and traders rushed to hedge as the AI trade unraveled on Thursday, sending the market
into a tailspin.
Steep losses in chip and data center-related stocks dragged down major stock indexes on fears the Democratic sweep in the US midterm elections could stall AI spending.
The selloff spurred retail traders to offload more than $1 billion and prompted hefty hedging activity in the equity options market as investors braced for further weakness. Wall Street’s most closely watched gauge of market anxiety, the Cboe Volatility Index, logged its biggest intraday jump in more than 18 months.
"The steamroller showed up today," said Jim Carroll, senior wealth adviser and portfolio manager at Ballast Rock Private Wealth in Charleston, South Carolina.
Analysts said much of the selling may reflect an unwind of the previous session's sharp rally and of the crowded AI trade that has driven markets for months, as well as investors cutting risk ahead of expected volatility-driven selling by funds and strategies.
The VIX, an options-based indicator that reflects demand for protection against drops in the stock market, jumped 11.75 points to an eight-month high of 28.36, a day after markets rallied following Democrats' sweeping midterm victory.
The index closed at 28.18, with the Nasdaq Composite falling 5.5% as investors fretted that a changing of the guard in Washington might slow the pace of AI infrastructure development.
At its session high, the VIX had logged its largest one-day rise since the days immediately after US President Donald Trump unveiled sweeping new import tariffs on "Liberation Day" in April 2025.
REACTION TO VOLATILITY
Thursday's stock market selloff was in sharp contrast to the upbeat market reaction the day before, when investors largely brushed aside the perceived threat to the AI trade from the Democrats' strong showing in the election.
"This is what happens when you have a big rally partly predicated on the idea that volatility would be decreasing ... it made no sense yesterday," said Steve Sosnick, chief strategist at Interactive Brokers.
"Yesterday there was the perception that no one needed protection and now it's 'Oh my god, we need it'," he added.
Analysts attributed some of the market decline to investors looking to get ahead of selling from strategies that react to stock market volatility.
Leveraged and inverse exchange-traded funds, along with some systematic strategies, typically rebalance their exposure near the market close, which can amplify late-day moves in either direction.
Leveraged exchange-traded funds were expected to sell about $47 billion of stocks into the close as they rebalance, according to an intraday note from Nomura. That would make it the second-largest amount in Nomura's data going back to July 2006, with most of it coming from tech and AI-focused funds.
"You have people saying ... look at what's going to happen at the end of the day, we need to get out before that," Ballast Rock's Carroll said.
Hedge funds too were feeling the pain.
According to a Goldman Sachs prime brokerage report sent to clients on November 5, large multi-strategy hedge funds were down "significantly" due to their outsized exposure to large AI stocks. Technology, media, and telecommunications-focused funds were down 2.6% from year-ago levels, Goldman added.
Much now depends on whether investors' attitude toward the AI trade undergoes a lasting change, analysts said.
"If the re-evaluation of the AI investment theme is secular and not just a trading type of rebalance, that's problematic," said Sosnick.
RETAIL ROUT
Retail traders added to the selling pressure on the market.
"Retail investors are on track for their largest day of selling across single stocks since the Covid crash," Viraj Patel, global macro strategist at Vanda Research, said in a note. With less than an hour to go to the close, he estimated $338 million of single stocks had been sold on net.
"On a typical sell-off, retail buy the dip. Today, that bid has effectively disappeared from individual names," Patel said.
Including ETFs, retail investors sold $1.3 billion, the most over the last year, JPMorgan data through 11:30 a.m. ET showed.
In the options market, the stock market drop boosted demand for hedges, with put premium — the price investors pay to buy contracts that protect against a market drop — running at about two times what is typical across the index products, according to data from options analytics service Mercury Alerts.
Options activity was a mix of traders looking for fresh protection in semiconductors and AI names alongside those taking profits on existing hedges, said Chris Murphy, co-head of derivative strategy at Susquehanna Financial.
Options activity showed some dip-buying, but outright call buying was limited, according to Mercury Alerts founder Harmeet Goindi.
"That reads like people using the higher volatility to sell downside and own upside into next year, rather than chasing a bounce today," Goindi said.
(Reporting by Saqib Iqbal Ahmed; Additional reporting by Laura Matthews and Anirban Sen; editing by Megan Davies, Kirsten Donovan and Nia Williams)