
By Stephen Culp and Utkarsh Hathi
Nov 18 (Reuters) - US stocks were mixed on Wednesday as investors digested Nvidia results ahead of Anthropic's initial public offering pricing, while weighing hawkish sentiment
reflected in US Federal Reserve minutes.
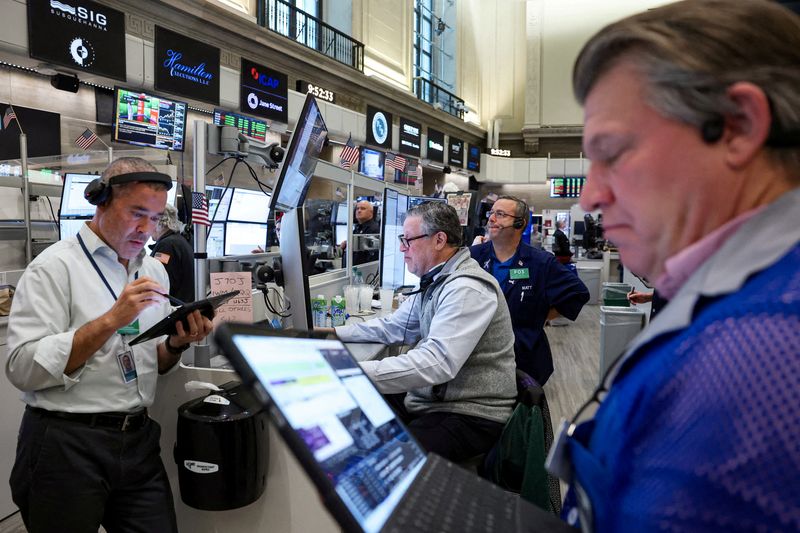
After the three major US stock indexes wavered earlier in the session, by mid-afternoon the Nasdaq turned higher, the Dow was down, while the S&P 500 reversed its modest gains following release of the Fed minutes.
Nvidia's quarterly results released late Tuesday beat analyst expectations, and the AI chipmaker forecast quarterly revenue above estimates. Even so, its shares were down 2.4% amid uncertainties caused by co-founder Jensen Huang's sudden departure last week.
The Philadelphia SE Semiconductor Index, which has handily outperformed the broader market this year, was off 0.7%, underscoring lofty expectations for the sector amid massive spending on AI infrastructure and potential risk associated with the nascent technology.
Anthropic's IPO is expected to price after the market closes on Wednesday. At the top of its $70 to $78 range, the offering would raise about $64.4 billion and value the company at about $1.4 trillion.
Other chipmakers were mixed. Intel was off 1.8%, Micron was down 2%, but Advanced Micro Devices rose 3.2%.
"There's been a lot of dark clouds of uncertainty over technology, chip stocks and AI in general," said Ryan Detrick, chief market strategist at Carson Group in Omaha. "It's important to remember the market's not totally falling apart here. It clearly is top-heavy with tech, but there are other groups that are actually doing pretty well under the surface."
Target jumped 6.3% after the discount retailer provided an upbeat holiday outlook. Results from its larger rival Walmart are expected on Thursday.
TJX surged 10.6% after forecasting upbeat annual sales, banking on strong demand ahead of the holiday shopping season.
Take-Two Interactive shares rose 7.7% ahead of the rollout of its Grand Theft Auto VI video game.
On the sector level, consumer discretionary was a clear outperformer, with a boost from a 3.8% gain in Amazon shares.
The Dow Jones Industrial Average fell 555.11 points, or 1.09%, to 50,204.31, the S&P 500 lost 19.48 points, or 0.27%, to 7,321.05 and the Nasdaq Composite gained 82.36 points, or 0.34%, to 24,410.75.
FOCUS ON THE FED
Minutes from the Fed's October policy meeting showed the central bank remained focused on inflation risks, recognizing the need for further rate hikes if the economy progresses as expected. A few policymakers argued the case for a 50-basis-point rate hike "if incoming inflation data were unfavorable."
Consumer and producer price data released after the October meeting showed hotter-than-expected price growth.
Fed Governor Christopher Waller took a hawkish stance on Wednesday, saying the central bank needs to be more aggressive in responding to inflation. This follows John Williams' comments on Tuesday, in which the New York Fed president said that while he favors tighter monetary policy, there was no need for "dramatic action."
Financial markets are pricing in a 94.7% probability of a 25-basis-point interest rate hike at the conclusion of the Fed's December meeting, according to CME's FedWatch tool.
Housing data released on Wednesday showed mortgage rates climbing, building permits faltering, and pending home sales dropping to a record low.
Declining issues outnumbered advancers by a 1.09-to-1 ratio on the NYSE. There were 33 new highs and 551 new lows on the NYSE.
On the Nasdaq, 2,345 stocks rose and 2,330 fell as advancing issues outnumbered decliners by a 1.01-to-1 ratio.
The S&P 500 posted 4 new 52-week highs and 8 new lows, while the Nasdaq Composite recorded 28 new highs and 369 new lows.
(Reporting by Stephen Culp; Additional reporting by Utkarsh Hathi and Ragini Mathur in Bengaluru; Editing by Rod Nickel)