
What's Happening?
The Centers for Medicare & Medicaid Services (CMS) has issued an interim final rule placing a temporary moratorium on new agent and broker registrations for the federally facilitated Affordable Care Act (ACA) exchanges for the 2027 plan year. This moratorium does
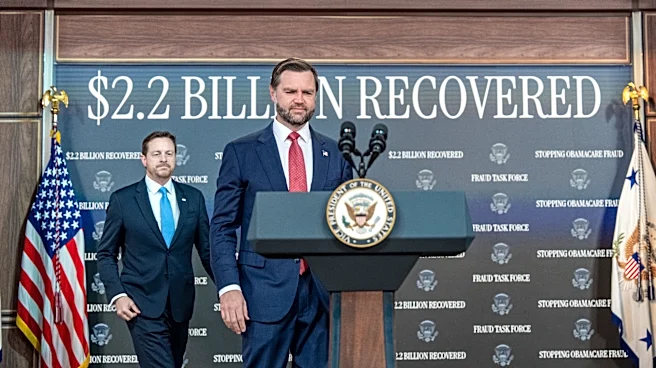
not impact registrations on state-based exchanges. CMS stated that this pause is necessary to implement enhanced program-integrity safeguards aimed at preventing noncompliance, fraud, waste, and abuse by agents and brokers. The agency cited instances of unauthorized enrollment activity, misuse of consumer personally identifiable information, and other conduct that threatens consumers and the integrity of the exchanges. CMS has observed a substantial increase in allegations and confirmed instances of such noncompliant practices, particularly involving newly registered agents and brokers. In Plan Year 2026, CMS issued final terminations to 160 agents and brokers for noncompliant behavior, with 11% being newly registered. Additionally, in July and August 2026, 569 Notices of Intent to Terminate Exchange agreements were issued to agents and brokers who submitted statistically implausible rates of applications without identifying applicant information. On August 31, CMS canceled approximately 315,000 Plan Year 2026 policies covering over 760,000 individuals due to unverified citizenship or immigration documentation.
Why It's Important?
This temporary moratorium by CMS is a significant move to address widespread fraud and abuse within the federally facilitated ACA exchanges. The reported increase in unauthorized enrollments and misuse of consumer data undermines the integrity of the healthcare marketplace and directly harms consumers. The cancellation of over 315,000 policies due to unverified documentation highlights the scale of the problem and the potential for significant financial waste and disruption for individuals. While intended to protect consumers and the system, the moratorium has drawn strong opposition from agent organizations like the National Association of Insurance and Financial Advisors (NAIFA) and the National Association of Benefits and Insurance Professionals (NABIP). These organizations argue that a blanket moratorium unfairly penalizes legitimate agents and brokers, restricts consumer access to assistance, and may not effectively target the actual perpetrators of fraud. The debate centers on finding a balance between robust fraud prevention and ensuring accessible, professional guidance for individuals navigating complex healthcare options.
What's Next?
The temporary moratorium on new ACA agent registrations will be in effect for the 2027 plan year, during which CMS plans to implement enhanced identity-verification, authentication, monitoring, and other program-integrity controls. Agent organizations are actively mobilizing against the moratorium, advocating for more targeted approaches to combat fraud rather than a broad ban on new registrations. They are urging CMS to consider alternative strategies, such as those employed in the Medicare enrollment framework, which include carrier-based certification, testing, training, and documentation requirements. This suggests ongoing dialogue and potential negotiations between CMS and industry stakeholders. The outcome could lead to revised regulations for agent and broker conduct, more stringent vetting processes, and potentially new technological safeguards to prevent fraudulent activities. Businesses that recruit, hire, and train new agents for the ACA marketplace face immediate financial consequences and uncertainty, as their investments for the upcoming enrollment season may be jeopardized. The situation will likely influence how consumers access and receive assistance with ACA plans in the future.
Beyond the Headlines
This CMS action reveals deeper systemic issues within the ACA marketplace, particularly concerning the balance between expanding access to healthcare and maintaining program integrity. The prevalence of fraud and unauthorized enrollments points to vulnerabilities in the current system that bad actors can exploit, potentially driven by incentives or lack of oversight. The strong reaction from agent organizations highlights the economic impact of such policies on legitimate businesses and professionals, raising questions about the unintended consequences of broad regulatory measures. This situation could also spark a broader discussion about the role of technology in preventing fraud, the effectiveness of current identity verification processes, and the need for continuous adaptation in regulatory frameworks to counter evolving fraudulent schemes. Ultimately, the long-term implications could include a more robust, albeit potentially more complex, system for agent and broker participation in the ACA exchanges, aiming to protect consumers while ensuring efficient access to health coverage. It also underscores the ongoing challenge of managing large-scale government programs susceptible to exploitation.