



What's Happening?
A new statewide report, part of California’s Fifth Climate Change Assessment, led by UC San Diego researchers Gordon McCord and Teevrat Garg, outlines the significant economic impacts of climate change on California. The report, titled 'Climate Impacts
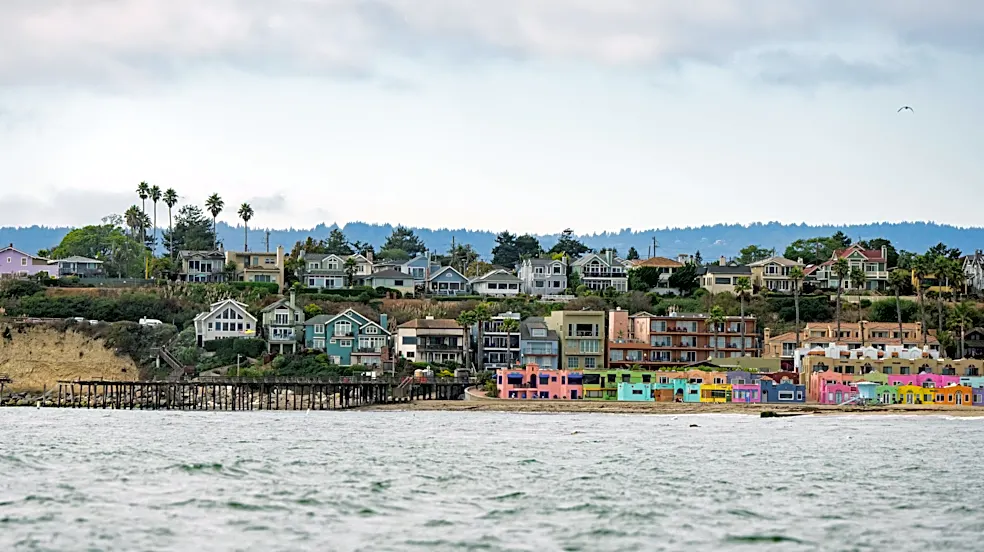
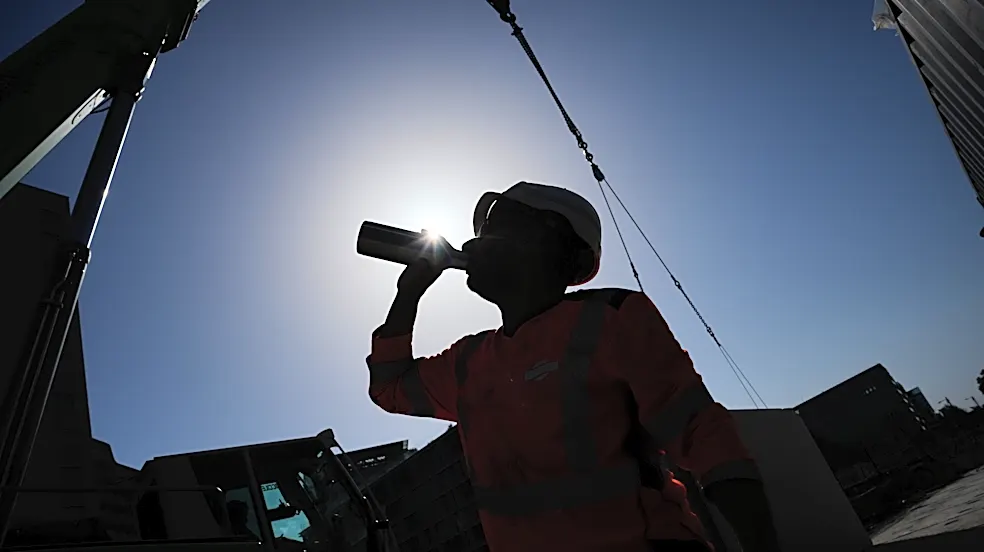
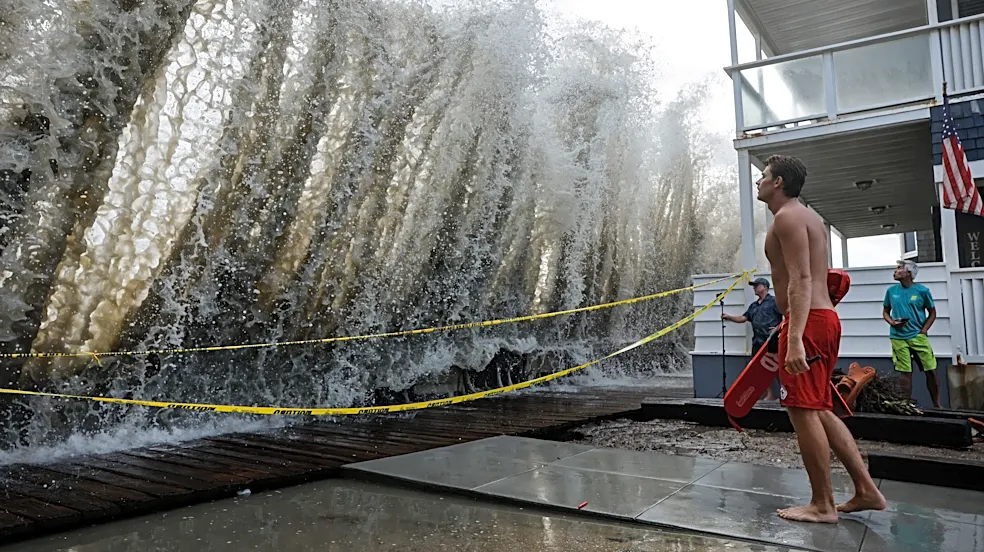
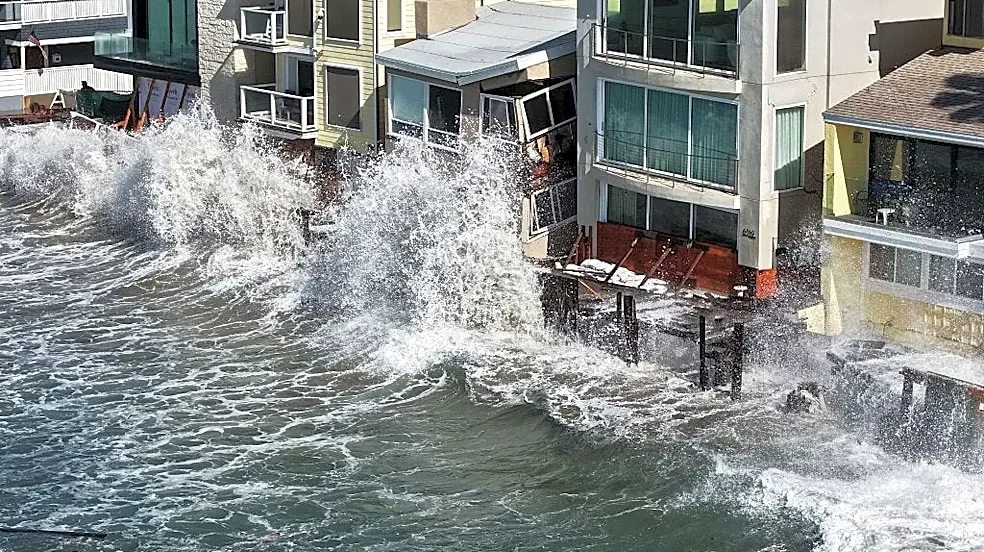
to the Economy,' highlights rising costs across various sectors, including health-related illnesses and deaths, lost work hours, and increased insurance and utility bills. It emphasizes that these costs are unevenly distributed, disproportionately affecting inland counties, low-income households, outdoor workers, tribal and rural communities, older adults, young children, and individuals with pre-existing conditions. Key findings project approximately 560 additional heat-related deaths annually by 2050, costing around $7.7 billion, and 5,060 additional deaths from wildfire smoke, amounting to about $68.8 billion annually under a high-warming scenario. Droughts are expected to cause $2.7 billion to $5.1 billion in direct agricultural losses each year by the early 2040s, and a 20-inch sea-level rise could inundate $17.9 billion worth of residential and commercial buildings by 2050.
Why It's Important?
This report is crucial for California as it quantifies the tangible economic and human costs of climate change, moving beyond abstract discussions to concrete financial and societal impacts. The uneven distribution of these burdens underscores existing social inequalities, indicating that vulnerable populations will bear the brunt of climate-related harms. For industries, the projections of agricultural losses, increased insurance premiums, and stress on power supply signal significant operational and financial challenges. The report's emphasis on interconnectedness—where disruptions in one sector, like agriculture, lead to higher food prices for households and businesses—highlights the systemic nature of climate risks. This comprehensive assessment provides policymakers, communities, and the public with critical data to inform decisions on adaptation and resilience investments, aiming to mitigate future costs and protect the most exposed populations.
What's Next?
The findings from this report are intended to guide policymakers in California in making more informed decisions regarding climate adaptation and resilience strategies. The report's authors, including Julie Kalansky and Tom Corringham, stress the need for sustained support to implement the knowledge gained from this assessment. This could involve prioritizing investments in areas most affected by extreme heat, wildfire smoke, and sea-level rise. For households, the report suggests a future of higher food, energy, and water costs, rising insurance premiums, and increased health expenses, necessitating personal and community-level preparations. The growth of property insured through the California FAIR Plan, the state’s insurer of last resort, from $50 billion in 2018 to $750 billion by March 2026, indicates a growing market response to escalating climate risks, suggesting further shifts in insurance availability and cost.
Beyond the Headlines
The report's detailed breakdown of climate costs reveals deeper implications beyond immediate economic figures. The disproportionate impact on low-income households, outdoor workers, and tribal communities raises significant ethical questions about environmental justice and equitable resource allocation in climate adaptation efforts. The projected increase in heat-related illnesses and deaths, alongside those from wildfire smoke, highlights a growing public health crisis that will strain healthcare systems and impact overall societal well-being. The report also implicitly calls for a re-evaluation of urban planning and infrastructure development to account for future climate scenarios, such as increased temperatures in San Diego and an uncertain precipitation future. The shift in the insurance market, with the state becoming a larger insurer of last resort, points to a potential long-term systemic change in how climate risks are underwritten and managed, possibly leading to greater government intervention in risk management.