

What's Happening?
Despite significant U.S. government intervention and private sector efforts, achieving a genuinely independent American mine-to-magnet rare earth ecosystem by 2030 is considered highly improbable, with even 2032 being ambitious. The more realistic objective
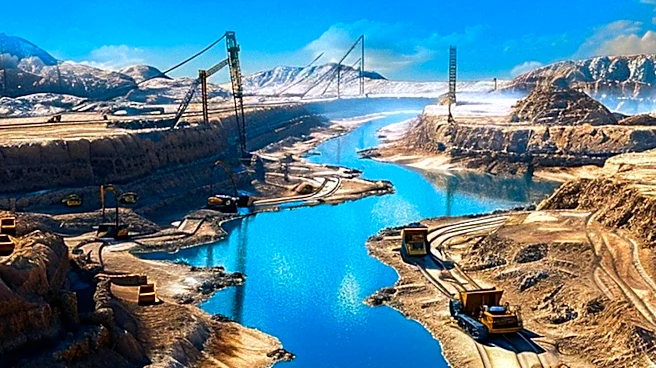
is to establish resilient U.S.-allied interdependence by the mid-2030s. While the U.S. possesses a deep industrial, scientific, and capital ecosystem, and companies like MP Materials are integrating mining with metals, alloys, and magnets in Texas, the process of ramping up plants, separating heavy rare earths, achieving specification-grade metals, and qualifying materials for customers requires substantial time and effort. China currently dominates the global rare earth supply chain, controlling over 70% of extraction and 90% of processing, a lead built on decades of accumulated industrial capability.
Why It's Important?
The current global rare earth supply chain presents a critical vulnerability for the U.S. and its allies. The heavy reliance on China for processing and manufacturing magnet metals, which are essential for defense, electric vehicles, and high-tech industries, poses significant economic and national security risks. The recognition that full independence by 2030 is unlikely underscores the complexity and time-intensive nature of building a complete industrial ecosystem from mining to finished magnets. Shifting the focus to 'resilient U.S.-allied interdependence' acknowledges that a collaborative approach with allies, leveraging their respective strengths in mining, processing, and technology, is a more pragmatic and achievable goal. This strategy aims to diversify supply sources, mitigate risks, and ensure a stable flow of critical materials for U.S. industries.
What's Next?
The U.S. will continue to invest in and support domestic rare earth projects, such as MP Materials' integration efforts and the development of processing facilities. Concurrently, there will be an increased emphasis on strengthening alliances with countries that have significant rare earth reserves and processing capabilities, such as Australia, Brazil, and Canada. These collaborations will focus on creating a diversified and secure supply chain where different nations specialize in various stages of the rare earth value chain. The coming years will see efforts to ramp up production, improve processing technologies, and establish robust customer qualification processes. The goal is to build a network of reliable suppliers and processors among allied nations to collectively reduce dependence on any single source.
Beyond the Headlines
The challenge of establishing a robust rare earth supply chain highlights a fundamental shift in global economic and geopolitical strategy. It moves beyond simply possessing raw materials to emphasizing the industrial capability to transform those materials into high-value products. This 'Great Powers Era 2.0' recognizes that industrial knowledge, infrastructure, and skilled labor are as crucial as geological reserves. The U.S. strategy of allied interdependence reflects a pragmatic understanding that no single nation can quickly replicate China's decades-long accumulation of industrial capacity. This approach could foster deeper economic and technological integration among allies, creating a more resilient global economy and potentially reshaping international trade relationships around critical minerals and advanced manufacturing.