



What's Happening?
In January 2026, the Social Security Administration implemented a 2.8% cost-of-living adjustment (COLA) for beneficiaries, increasing the average retired worker's check by approximately $56 per month. However, inflationary pressures have largely negated
this increase for many retirees. For instance, the standard monthly Medicare Part B premium for 2026 rose by nearly 10% to $202.90, consuming about 32% of the COLA. The Medicare Part B annual deductible also increased by $26 to $283. Furthermore, the Consumer Price Index for All Urban Consumers (CPI-U) increased by 3.4% over the 12 months ending July 2026, surpassing the 2.8% COLA. Retirees are particularly affected by shelter costs, which rose by 3.2%, exceeding the COLA. The COLA calculation, based on the CPI-W (Consumer Price Index for Urban Wage Earners and Clerical Workers), does not accurately reflect the spending patterns of retirees, who allocate a larger portion of their expenses to healthcare and housing.
Why It's Important?
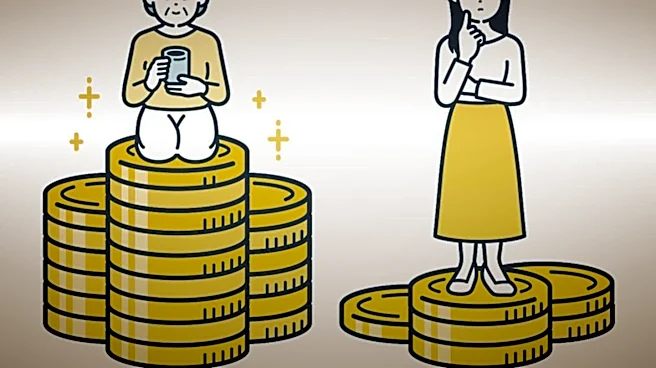
The discrepancy between the Social Security COLA and the actual rising costs faced by retirees highlights a critical challenge for the financial security of older Americans. With Medicare Part B premiums and deductibles consuming a significant portion of the COLA, many retirees are left with minimal or no real increase in their purchasing power. This situation disproportionately affects seniors, who typically have fixed incomes and higher healthcare and housing expenses compared to the working-age population reflected in the CPI-W. The inability of the COLA to keep pace with inflation means that the financial burden on retirees continues to grow, potentially leading to reduced quality of life and increased reliance on other forms of assistance. This issue also raises questions about the adequacy of the current COLA calculation methodology and its fairness to the retiree demographic.
What's Next?
The Senior Citizens League projects a 3.6% COLA for 2027, to be announced in October 2026. While this estimate is higher than the 2026 adjustment, its effectiveness in covering increased living costs for seniors will depend on future inflation rates. There is an ongoing discussion about reforming the COLA calculation to better reflect the spending patterns of retirees, potentially by using an index that gives more weight to healthcare and housing costs. Without such reforms, retirees may continue to see their Social Security benefits eroded by inflation. Advocacy groups are likely to continue pushing for legislative changes to ensure that Social Security provides a more accurate and adequate cost-of-living adjustment for its beneficiaries, addressing the financial vulnerabilities of older Americans.
Beyond the Headlines
The persistent gap between Social Security COLAs and actual retiree expenses points to a systemic issue in how the U.S. supports its aging population. Beyond the immediate financial strain, this situation can lead to increased stress, reduced access to essential services, and a decline in overall well-being for seniors. The reliance on the CPI-W, which is geared towards a younger, working demographic, underscores a fundamental mismatch in economic measurement and policy application. This could prompt a broader re-evaluation of economic indicators used for social programs, potentially leading to the adoption of a more tailored index for retirees, such as the CPI-E (Consumer Price Index for the Elderly). Such a shift would not only provide more accurate adjustments but also acknowledge the unique economic realities faced by older adults, fostering a more equitable and sustainable social safety net.