


What's Happening?
Nevada has implemented Assembly Bill 376, a new law that permits property insurers to exclude wildfire coverage from standard homeowner policies. This legislation, which became effective on January 1, 2026, allows insurance carriers two new options: they
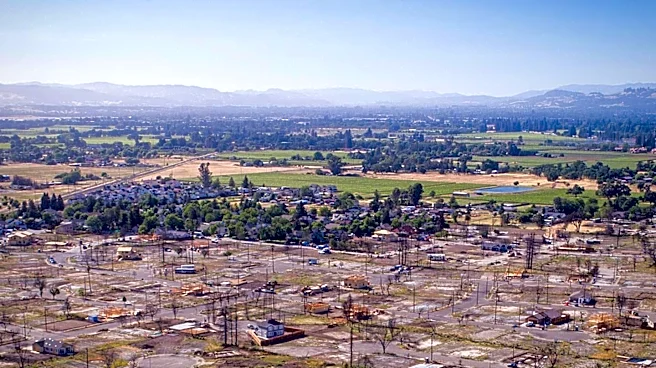
can either exclude wildfire coverage and offer it as a separate policy, or exclude it entirely without offering an alternative. This makes Nevada the first state to explicitly allow such exclusions. The bill passed unanimously in June 2025 and was signed by Governor Joe Lombardo. This change comes as Nevada experiences a record-setting wildfire season, with six wildfires scorching Reno/Sparks hillsides as of October 4, 2026, including the Hawk Fire which burned over 15,000 acres and destroyed 32 homes. Homeowners in areas like Cold Springs have directly experienced the impact of these fires, highlighting the growing risk.
Why It's Important?
This legislative change significantly alters the landscape of homeowner insurance in Nevada, potentially leaving many residents vulnerable to substantial financial losses from wildfires. Unlike California and over 30 other states, Nevada lacks a FAIR Plan, which serves as an insurer of last resort for homeowners unable to secure coverage in the standard market. The absence of such a plan, combined with the new law, means consumers struggling to obtain coverage may have fewer options. According to Janet Ruiz, senior director of strategic communication for The Insurance Information Institute, this framework reflects increasing pressure in wildfire-prone states to maintain private market participation while addressing escalating catastrophe risks. Homeowners' insurance rates in Nevada have already climbed 24% from 2023 to 2025, driven by the increasing frequency and severity of wildfire losses, rising rebuilding costs, and inflation.
What's Next?
Nevada's AB 376 is structured as a four-year 'sandbox' program, allowing authorized insurers to test innovative property and casualty insurance products with relaxed regulatory compliance. Homeowners are urged to carefully review their insurance policies, especially renewal notices, for any changes regarding wildfire coverage. If wildfire coverage is excluded, consumers should contact their insurer or agent to explore options, such as wildfire mitigation efforts on their property or standalone wildfire policies. Experts recommend shopping around for insurance, ideally seeking an all-in-one policy that includes wildfire coverage, as this is generally less expensive than purchasing two separate policies. There is also a growing call for homeowners to advocate for the creation of a FAIR Plan in Nevada to prevent a potential crisis of insurability.
Beyond the Headlines
The new law in Nevada highlights a broader national challenge in managing insurance risks associated with climate change and increasing natural disasters. The explicit allowance for insurers to exclude wildfire coverage could set a precedent for other states facing similar pressures, potentially shifting more financial burden onto homeowners. This situation also underscores the critical importance of individual property-level risk mitigation. With roughly half of Nevada homes located in the wildland-urban interface (WUI), which grew faster in Nevada than any other state between 1990 and 2020, the need for defensible space and home hardening measures becomes paramount. Documenting these efforts, through photos and invoices, can be crucial for homeowners when seeking or renewing insurance, as insurers increasingly evaluate individual property characteristics beyond community-level risk.