


What's Happening?
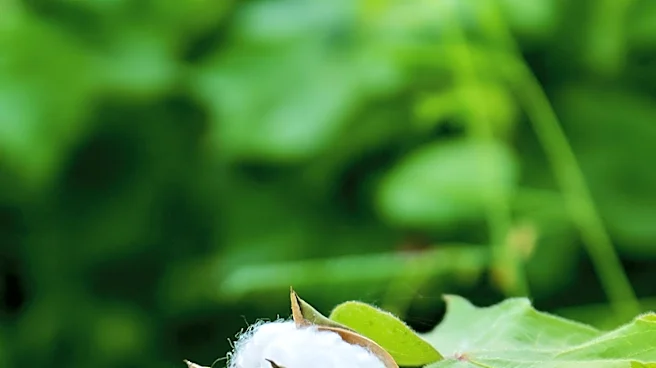
The U.S. cotton crop is experiencing a significant contraction, leading to an 18-month high in cotton prices. This is primarily due to record heat in West Texas, which has raised concerns about cotton yields and abandonment. Declining crop conditions
indicate that the Texas crop may underperform, with only 18% rated good-to-excellent and 49% rated poor-to-very-poor. The USDA forecasts a 5% year-over-year decline in the U.S. cotton crop to 13.2 million 480-pound bales, with yields dropping 9% year-over-year to 776 pounds per acre. Similar supply losses are affecting other agricultural commodities, with U.S. rice acreage falling 25% year-over-year, leading to the smallest harvest since 1990. Sugar prices are also climbing due to tightening production prospects, including the lowest sugar beet plantings since 1950 and pest infestations affecting sugarcane growers in Florida.
Why It's Important?
The shrinking U.S. cotton crop and rising prices have significant implications for the U.S. textile industry, consumers, and the broader agricultural sector. Higher cotton prices can increase production costs for clothing and apparel manufacturers, potentially leading to higher retail prices for consumers. This comes at a time when inflation-weary consumers are already trading down or delaying spending. The resilience of U.S. cotton export sales, aided by higher crude oil prices making synthetic fibers more expensive, provides some buffer for the industry. However, the overall decline in crop yields highlights the vulnerability of agricultural production to climate-related events like extreme heat and drought. The situation also underscores the interconnectedness of global commodity markets, as U.S. supply issues can influence international prices and trade dynamics. The challenges faced by cotton, rice, and sugar producers collectively point to broader concerns about food security and agricultural sustainability in the face of environmental pressures.
What's Next?
The market will closely monitor U.S. harvest yields for cotton in the coming quarter, as well as the response of Brazilian farmers to higher cotton prices, which could influence global supply. For rice, concerns are growing about potential acreage reductions in Brazil, a major U.S. export competitor, and the impact of El Niño on global production, particularly in India and Southeast Asia. These factors could further tighten global rice supplies. For sugar, the widening spread between U.S. and world raw sugar prices is expected to continue pulling imports into the U.S., despite existing tariffs. The long-term outlook for these commodities will depend on weather patterns, global demand, and agricultural policies. Farmers may need to adapt to changing climate conditions through new cultivation techniques or crop diversification. Consumers should anticipate potential price increases for goods reliant on these agricultural inputs.
Beyond the Headlines
The challenges facing the U.S. cotton, rice, and sugar crops highlight the profound impact of climate change and extreme weather events on agricultural systems. The record heat in West Texas and the influence of El Niño on global rice production are stark reminders of the increasing volatility in agricultural output. This situation raises deeper questions about the resilience of global food supply chains and the need for sustainable agricultural practices. The economic consequences extend beyond immediate price fluctuations, potentially affecting rural economies, employment in agricultural sectors, and international trade relations. Furthermore, the reliance on imports to offset domestic supply shortages, as seen with sugar, underscores the complexities of balancing domestic production with global market dynamics and trade policies. Addressing these issues will require a multi-faceted approach involving climate adaptation strategies, agricultural research, and international cooperation to ensure long-term food and fiber security.