
What's Happening?
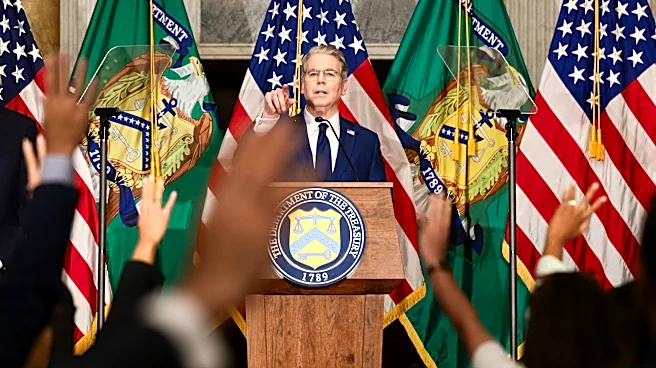
U.S. Secretary of the Treasury Scott Bessent, alongside other senior U.S. officials, announced several new initiatives in Minnesota aimed at combating widespread fraud. These measures are part of the White
House Task Force to Eliminate Fraud, with the Treasury Department working to safeguard American taxpayer dollars and restore integrity to federal benefits programs. Secretary Bessent stated that under President Trump and Vice President Vance's leadership, the Treasury has already prevented nearly $190 million in funds linked to overseas fraud and returned over $100 million to U.S. victims. The initiatives follow Bessent's earlier visit to the Twin Cities, where he met with financial institutions, fraud victims, and state leaders, and conducted training sessions for law enforcement on fraud detection and investigation. The Treasury continues to provide crucial data to federal, state, and local law enforcement to generate leads and dismantle fraud schemes. Recent actions include the sentencing of Salim Said to 30 years in prison for his role in the Feeding Our Future fraud scheme, which exploited a federal child nutrition program during the COVID-19 pandemic.
Why It's Important?
These new fraud prevention measures are critical for protecting federal funds and ensuring the integrity of government programs. The scale of fraud, as highlighted by the billions of dollars wasted in Minnesota, underscores the necessity of robust enforcement and preventative actions. By targeting various forms of illicit activity, from exploitation of child nutrition programs to cross-border payment schemes and misuse of charities, the Treasury aims to mitigate significant financial losses for taxpayers. The involvement of the White House Task Force emphasizes a coordinated federal effort to address these issues comprehensively. Successful prosecution, such as the 30-year sentence for Salim Said, serves as a deterrent and demonstrates the government's commitment to holding perpetrators accountable. Furthermore, by alerting financial institutions to suspicious activities, the Treasury is strengthening the financial system's defenses against money laundering and terrorist financing, which can have broader national security implications.
What's Next?
The Treasury Department will continue its efforts as part of the White House Task Force to Eliminate Fraud, focusing on implementing the announced initiatives and developing further strategies to combat fraud nationwide. Financial institutions are expected to increase their vigilance regarding suspicious cross-border payments involving money services businesses (MSBs) and activities related to charities and non-profit organizations, following alerts issued by FinCEN. Law enforcement agencies will likely leverage the data and training provided by the Treasury to enhance their investigative capabilities and pursue more fraud cases. The ongoing collaboration between federal, state, and local authorities is anticipated to lead to more arrests and prosecutions, further deterring fraudulent activities. The success of these measures will be gauged by the reduction in fraudulent losses and the restoration of public trust in federal benefit programs.
Beyond the Headlines
The broader implications of these anti-fraud initiatives extend to reinforcing public trust in government and financial systems. Rampant fraud erodes confidence in public institutions and diverts essential resources from legitimate beneficiaries. By actively combating fraud, the government aims to demonstrate its commitment to accountability and responsible stewardship of taxpayer money. The focus on various fraud types, including those exploiting charities, highlights the evolving tactics of illicit actors and the need for adaptive countermeasures. This comprehensive approach also underscores the interconnectedness of financial crime, from local schemes to international money laundering, necessitating a multi-faceted response. The emphasis on collaboration between government agencies and financial institutions sets a precedent for a more integrated defense against financial malfeasance, potentially leading to long-term improvements in financial security and regulatory frameworks.