



What's Happening?
Massachusetts law, specifically Section 3 of Chapter 60B, outlines exemptions from excise taxes for certain vessels and fishing equipment. The excise tax does not apply to vessels owned by the Commonwealth or its political subdivisions, law enforcement
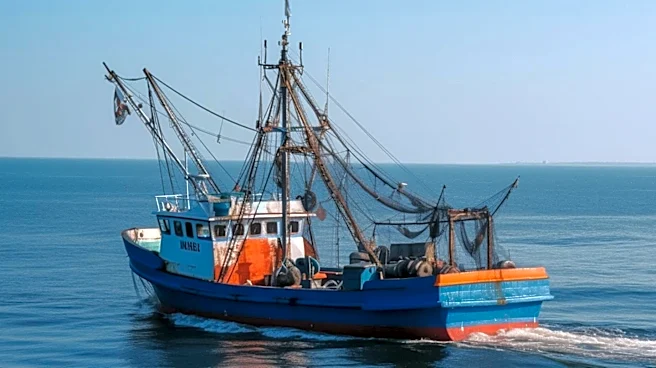
vessels, or vessels currently under construction. Ferries are also exempt. Significantly, boats, fishing gear, and nets actively used by their owner exclusively for commercial fishing are exempt, provided their total value is $10,000 or less. Additionally, other vessels with a value of $1,000 or less are also exempt from this excise tax. These exemptions ensure that the specified vessels and equipment are not subjected to other taxes under Section four of Chapter fifty-nine.
Why It's Important?
This Massachusetts law is important for the state's commercial fishing industry and small vessel owners. By exempting commercial fishing gear and vessels valued at $10,000 or less, the state provides a financial relief to small-scale commercial fishermen, potentially reducing their operational costs. This can help sustain local fishing businesses, which are often vital to coastal communities and local economies. For owners of very low-value vessels, the exemption of those under $1,000 also lessens the tax burden, making boat ownership more accessible and affordable. This policy reflects an effort to support specific economic sectors and individual citizens by mitigating tax liabilities on essential tools for livelihood and low-cost personal assets.
What's Next?
The existing exemptions are part of established Massachusetts General Law, indicating a continued framework for supporting commercial fishing and small vessel owners. Stakeholders in the commercial fishing industry and owners of low-value vessels can continue to benefit from these tax exclusions. Any future changes to these exemptions would likely require legislative action, potentially involving discussions on the economic impact on the fishing industry, state revenue, and the administrative burden of such taxes. Advocacy groups for commercial fishermen and recreational boaters may monitor these provisions to ensure their continued protection or to propose adjustments based on evolving economic conditions or industry needs.
Beyond the Headlines
Beyond the direct financial relief, these exemptions highlight a broader policy approach to foster specific industries and support economic activity at the local level. The commercial fishing exemption, in particular, acknowledges the often-precarious nature of the fishing industry, which is subject to environmental factors, market fluctuations, and regulatory changes. By reducing tax burdens on essential equipment, the state implicitly recognizes the cultural and economic value of its fishing heritage. The exemption for low-value vessels also touches upon issues of accessibility and equity, ensuring that basic boat ownership is not unduly burdened by taxation, which can be particularly impactful for lower-income individuals or those using older, less valuable equipment.