
What's Happening?
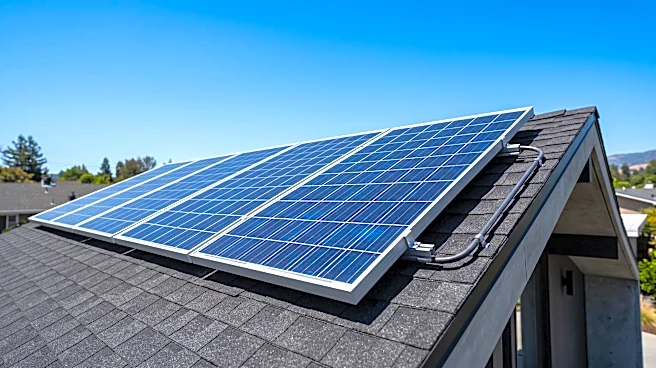
The New York State Energy Research and Development Authority (NYSERDA) has unveiled new solar incentive blocks under its NY-Sun Sustainable Future Program (SFP). This initiative is supported by a $200 million allocation from the state’s 2026-27 budget,
aimed at boosting distributed solar energy. The new framework specifically targets nonresidential projects in Upstate New York and Long Island, as well as statewide Affordable Solar Residential Incentive (ASRI) developments for low-to-moderate income households. For Upstate nonresidential projects up to 1 MW, a new 35 MW block is opening with a base incentive of $0.40 per watt, marking a $0.15 increase from the previous Block 10 rate. Long Island is receiving its first nonresidential incentive block since 2019, a 30 MW block for projects up to 5 MW, offering $0.25 per watt. Additionally, new 10 MW ASRI blocks are being introduced for each region, providing $0.60 per watt for Upstate installations and $0.40 per watt for Con Edison and Long Island regions. An extra $0.20 per watt adder is available for ASRI households that completed insulation and air-sealing projects through the Empower+ program since July 2023. NYSERDA has clarified that no new funding is being allocated for market-rate residential solar.
Why It's Important?
These new incentive blocks are crucial for advancing New York's renewable energy goals, particularly in expanding solar capacity for businesses and supporting energy affordability for lower-income households. The increased incentives for Upstate nonresidential projects could stimulate significant investment and development in that region, fostering economic growth and job creation within the solar industry. The reintroduction of nonresidential incentives for Long Island, after a five-year hiatus, is expected to reignite solar development in that area. By focusing on ASRI, NYSERDA is addressing energy equity, ensuring that the benefits of solar energy, such as reduced electricity bills, are accessible to low-to-moderate income communities. This targeted approach helps mitigate the financial barriers that often prevent these households from adopting solar technology. The absence of new funding for market-rate residential solar suggests a strategic shift towards supporting specific market segments and larger-scale projects, potentially influencing the types of solar installations that will dominate the state's energy landscape in the coming years.
What's Next?
The Upstate and Long Island nonresidential blocks are anticipated to open around December 15, coinciding with the start of contractor applications for ASRI. NYSERDA is currently accepting written stakeholder feedback on the ASRI Design until November 30, 2026, indicating a period for public input before final implementation. Project applications for the ASRI blocks are scheduled to open around January 19, 2027. A key development to watch is the determination of incentive amounts for Upstate nonresidential projects between 1 MW and 5 MW, which are currently pending. This delay is linked to a regulatory process by the New York Public Service Commission (PSC) concerning an updated version of the Value of Distributed Energy Resources (VDER). The PSC's decision on VDER will significantly influence the compensation structure for solar project owners, impacting the financial viability and future growth of larger solar installations in the state.
Beyond the Headlines
The strategic allocation of $200 million towards distributed solar, with a clear emphasis on nonresidential and affordable residential sectors, signals New York's commitment to a more decentralized and equitable energy grid. This move could lead to a more resilient energy infrastructure, as distributed solar reduces reliance on centralized power plants and enhances local energy independence. The focus on low-to-moderate income households through ASRI also highlights a broader societal shift towards integrating social equity into climate and energy policies, recognizing that the benefits of renewable energy should be shared across all socioeconomic strata. Furthermore, the ongoing regulatory process by the PSC regarding VDER underscores the complex interplay between policy, market mechanisms, and technological adoption in the renewable energy sector. The outcome of this regulatory review will not only shape the economic landscape for solar developers but also set precedents for how distributed energy resources are valued and integrated into the broader energy market, potentially influencing other states' approaches to solar compensation.